Showing posts with label Lendlease REIT. Show all posts

Monday, 30 March 2026

Capitaland Ascendas REIT Rights Issuance in Midst of US-Iran War-Subscribe Or Wait?

I nearly fainted when I read that there is another upcoming rights issuance exercise from another SREIT that I have held onto for many years, that is, Capitaland Ascendas ("CLAR"). This is coming off from the disastrous rights issuance exercise by Lendlease Global Commercial REIT (LREIT") with only a pathetic 62.2% take up rate. LREIT was thus heavily undersubscribed and the joint underwriters, DBS and friends, were forced to fork out S$74.3mil to take up the excess units that nobody wanted. Now, we have CLAR coming along to join in the fun during the midst of the US-Iran Middle East war. I would say that the timing is awful but then, CLAR is in a better state than LREIT as it is a giant REIT with 222 investment properties as at 31 December 2025 while LREIT on the other hand has only 4 investment properties or 5 if you count in its minor stake in Parkway Parade. To put it simply, CLAR is a very well run government linked blue chip REIT that can weather any storms relative to the smaller REITs. 

1. Should One Subscribe for CLAR?
Personally, I think that the price of CLAR has been quite stable and hovering around the S$2.50 per unit level since its announcement of the rights issuance. This is testament to the strength of CLAR in the eyes of general investors. So, I guess it is a no brainer to subscribe for one's own allotment to prevent dilution. 

The new investment properties to be purchased are also of good quality in particularly, the one at Singapore Loyang. Interestingly, Toll Logistics Group is planning to offload their famous Loyang Off-Shore Supply base to CLAR via a long term 12 years triple net sales-and lease-back agreement. If I recalled correctly, Toll Logistics Group ultimate owner is Japan Post Holding hence the quality of rental income from this distinctive tenant is top-notch.  
Toll Offshore Petroleum Services (TOPS) at Loyang

As for excess subscription, it really boils down to how the Middle East war will turn out over the next one week to judge market sentiment and downside risk. 

2. Key Information Highlights- Retail Investors Rights Issuance Tranche.
In connection with the Preferential Offering, the Manager intends to issue Preferential Offering Units to Eligible Depositors (as defined herein) and Eligible QIBs (as defined herein (collectively, the “Eligible Unitholders”) on a pro rata basis in respect of their existing Units (the “Existing Units”) held as at 5.00 p.m. on 1 April 2026, being the record date in relation to the Advanced Distribution and the Preferential Offering entitlement (the “Record Date”). 

The allotment ratio for the Preferential Offering will be announced by the Manager via SG XNET (pls post the link to this post for those who already saw the announcement released-updated March 31, 2026- 28 Units for every 1,000 units). 

As for the Preferential Offering Issue Price, it has been determined to be at the lower end of S$2.35 per unit.
As at March 30, 2026
As at March 31, 2026

3. Indicative Timeline of Key Events:
Rights application will open on 9am of 7 April 2026 (Tuesday) and end by 5.30 pm of 15 April 2026 (Wednesday). 

Parting Thoughts
I like the new investment properties such as data centre in Japan as well as good quality master tenant from 25 Loyang Crescent that forms the basis of this rights issuance exercise. I will most probably be taking up excess rights on top of my normal allotment.

Monday, 16 March 2026

Purchases During Recent Market Turmoil in Midst Of Donald Trump's War Against Iran.

Hi Folks, this post is more for my personal update & tracking of my own investment during the recent oil crisis sparked off by Donald Trump's war against Iran. Some said that Trump's war against Iran is more of a diversion tactic from his own domestic home base away from the Epstein fiasco and his involvement. From Trump's perspective, he is waging a righteous war to prevent Iran from further enrichment of uranium for building a nuclear bomb that will mean the end of the world. Nevertheless, no matter what is the rationale for igniting the fire of war, it has lead to global devastating consequences with oil price shooting through the roof by almost 100% relative to pre-war oil prices.

1. Investments and Accumulation (Cash + CPF deployment)
During the past week of market turmoil, I have executed the following purchases:

(i) Alibaba (HK 9988)- AI fallout and also fear of intensifying e-Commerce competition led to Alibaba stocks falling from over HKD185 per share in October 2025 to under HKD130 per share which is a close to 30% decline in its share price. I remain optimistic in Alibaba's fast growing cloud business. Bought more Alibaba shares at HKD130 per share and around S$6.5K;

(ii) Lendlease Global Commercial REIT (SGX-JYEU)- Unfortunately, prices did not drop further with substantial discount price to its rights issuance exercise of S$0.558 per unit. It continued to hover around S$0.555 to S$0.560 per unit. Since most of my investments are not held under discount broker like Tiger/Moo Moo, I decided to just save on the brokerage cost by subscribing for the rights under my Maybank Margin account. Have cut down on the excess subscription for sake of rounding up the numbers to at least 100 tranche. Around S$7K for S$0.0558 per unit of Lendlease Global Commercial REIT ("LREIT"). Additionally, end of today I will further subscribe to another S$3.3K worth of LREIT @S$0.558  under my CDP account. I believe that the transformation to Singapore focused retail REIT model and the better aggregate leverage ratio has completed and LREIT's financial performance should stabilise going forward (provided its Management does not do anymore hostile & anti-shareholders stance such as massive diluting existing unit-holders from capital raising exercise via offering rights issuance to only new external shareholders).

(iii) Amova STC Asia REIT ETF (SGX-CFA)- Decided to pump in from my CPF OA account amount of S$10K at price of S$0.801 per unit during the REIT pricing correction and fear of inflation coming back with financing cost spiralling upwards again. 

(iv) Mapletree Industrial Trust (SGX-MIT)- Interestingly, price of MIT has slid to below S$2.00 per unit level again and this represented a high dividend yield of more than 6.5%. From my CPF OA investment account, went on to accumulate another 2,000 units of MIT at price of S$1.97 per unit for S$3,940. 

Total accumulation over the past week: S$16.8K in cash top up and another S$14K from CPF OA. 

2. Parting Thoughts
At this juncture, I don't think anyone is certain of when exactly the war waged by US and the closure of the Straits of Hormuz by Iran will end. So take note that the stock markets might crash even further. Hang in there folks and hope that the senseless war will end soon and the global stock markets will eventually recover. Who dares wins!

Friday, 6 March 2026

Lendlease REIT Upcoming Rights Issuance Becoming A Disaster- A Victim of Donald Trump's War On Iran.

Lendlease Global Commercial REIT ("LREIT") recent rights issuance exercise to raise funds to purchase the remaining 30% stake of PLQ Mall seems to be on the verge of a disaster as the recent closing price is S$0.555 per unit as at the closing of 5 March 2026. This is just below the rights issuance price of S$0.558 per unit.

1. What happens if price remain below S$0.558 per unit during the commencement of the rights issuance on 10 March 2026?
Now this is a very good question. If the price of LREIT continue to decline below the right issuance pricing, then no sane retail or institutional investors will subscribe for it. Instead, to avoid dilution, most investors will just buy from the open market. Nonetheless, the good news is that the joint underwriters trio of DBS, UOB and OCBC will step in to mop up the unsubscribed units at S$0.558 per unit. The process works like this according to the Underwriting Agreement dated 25 February 2026, the process works as follows:

  • Sponsor Commitment: The sponsor, Lendlease Corporation, has provided an irrevocable undertaking to subscribe to its full provisional allotment of units;

  • Underwriter Obligation: For all other units (the "Underwritten Units"), the Joint Underwriters (DBS, OCBC, and UOB) must first procure third-party subscribers;
  • Backstop: If they cannot find enough subscribers, the underwriters themselves must subscribe and pay for all remaining units at the issue price of S$0.558;

  • Funding Assurance: This structure ensures the REIT raises the full S$196.6 million required for the PLQ Mall acquisition and debt reduction, regardless of retail or institutional investor demand.
2. Parting Thoughts
LREIT seems to have become another victim of Donald Trump's war on Iran. For retail investors, such a turn of event for LREIT is ominous. The joint underwriters will eventually need to dispose part of or all of their accumulated units which will lead to further downward selling pressure on its market price.  

Wednesday, 25 February 2026

Lendlease REIT Management Latest Rights Issue Finally Did Justice To Existing Unit-Holders- Full Acquisition of PLQ Mall.

The management of Lendlease REIT ("LREIT") announced this morning that it will acquire the remaining 30% of PLQ Mall and will launch a $196.6 mil rights issue priced at 55.8 cents each. Finally, the management listened after the previous private tranche placement in November 2025 whereby the same PLQ property acquisition leads to dilution of existing loyal unit-holders. I hope that the management continues to offer retail investors preferential rights first before tapping on new investors as a form of basic courtesy.

1. Subscribe or Not?
Personally, I will be taking up the issuance given the very attractive entry price of S$0.558 per unit relative to the market closing rate before the announcement of S$0.60 per unit. This will be a more than 6% distribution yield for the new units. 

The only uncertain risk here is the opening of the RTS which will grant Singaporeans more convenient access to Malaysian shopping malls and the extent of the adverse impact on Singapore retail scene. This is somewhat similar to Hong Kong retail which had went downhill for the past few years as shopper flocked to Shenzhen. But I am optimistic that the impact will be minimal on Singapore retail scene given that our local shopping malls have mostly pivoted to F&B outlets and education centres as tenants to complement retail grocery (NTUC Fairprice, Cold Storage etc). For example, parents will not send their kids over to Malaysia for tuition centres right? Another illustrative will be that, one will not want to expend too excessive time to go over Malaysia just to have McDonalds. 

2. Key Dates For Investors
Existing investors of LREIT, take note that the last date and time for acceptance is 18 March 2026 at 5.30pm and 9.30pm for Electronic Applications through ATM of participating bank.

Parting Thoughts
At the current low offered pricing of the new units at S$0.558 per unit, I think that the best option out there is to take it up. Interestingly, the previous private placement was done at S$0.602 per unit which is 7% more expensive. Most likely, I will also be subscribing for the excess. Also, guess, I no longer need to go to LREIT's 2026 AGM to pick a bone with their CEO and CFO on the unfair treatment of existing unit-holders which is very disrespectful and high handed in their previous fund raising exercise. 

Thursday, 6 November 2025

Disappointing Private Placement Exercise By Lendlease Global Commercial REIT To Acquire Paya Lebar Quarter Mall.

This is another classic anti-existing unit-holders move by another REIT Management on SGX and extremely disappointing. I can still vividly recalled the IPO price of S$0.88 per unit by Lendlease Global Commercial REIT ("LREIT") on September 25, 2019. Unfortunately, its current market price as at November 4, 2025 is just S$0.635 per unit which is a faint shard of its former self at IPO. To add salt to injury, the Management of LREIT did not seek to raise funds first with existing unit-holders via a right issue but instead elected for a private placement. Totally no respect and appreciation to loyal current unit-holders especially those that have subscribed since IPO inception. Consequently, this lead to many loyal unit-holders, who continued to invest in LREIT, to become severely diluted by this acquisition.

1. Disappointing Private Placement By Management of LREIT
The only good news here is that on November 6, 2025 morning, LREIT has announced the results of the private fund raising at an issuance price of S$0.602 per unit, which is just a 3.7% discount to the adjusted weighted average price. Considering that the initial target was between S$0.597 per unit to S$0.616 per unit, the price of S$0.602 through private placement is considered not too low. Nevertheless, this is still an extremely disappointing move by the management of LREIT that ignored loyal retail unit-holders. 


2. General Assessment of PLQ Mall Acquisition
This is a very good retail asset that is located just besides 2 MRT lines. You would need to go down to PLQ Mall to see and experience for yourself. It is currently on 100% full occupancy.  Increasing the share of suburban retail in the portfolio of LREIT should make its earnings more resilient. 

Additionally, this acquisition of 70% of PLQ Mall will be DPU yield accretive by 2.5% post-acquisition.

The bad point of this acquisition exercise  is that the Aggregate Leverage of LREIT will increase from 35.1% to 38.3%  

Parting Thoughts
LREIT is embarking on a Singapore-focused strategy for now with Singapore assets forming close to 90% of its portfolio. Suburban retail will now made up 63% of total portfolio relative to pre-acquisition of 55%. The only remaining problem is with its "Grade A Office" of Sky Complex at Milan which has not been performing well since the loss of a major office tenant. Also, the management of LREIT has not been exactly friendly to existing unit-holders and took the easy way out of opting for a private placement route to raise funds for M&A. Retail investors need to be wary of the current management of LREIT who are only after their self interest at the expense of unit-holders. I will be looking to pare down some of my stakes in LREIT.  

Tuesday, 5 August 2025

Lendlease Global Commercial REIT Makes Big Strategic Mistake to Sell Off JEM's Office to Keppel Ltd.

After a few months since rumour began circulating, Lendlease Global Commercial REIT ("LREIT") finally revealed on August 4, 2025, that it will indeed be divesting Jurong East Mall ("JEM") office for S$462 Mil. The buyer of the office tower is Keppel Ltd.

1. Big Strategic Mistake To Sell off JEM Office.
LREIT should have sold off the underperforming Sky Complex buidling in Milan. Instead it sold off a high yielding office building at JEM with stable government agency tenant. I recalled that they just got a 13% rental reversion after the recent 5 years review in 2024. JEM's area is currently still undergoing transformation and development and LREIT will be missing out on potential future capital appreciation. This is actually the worst time to be selling off the JEM office.
Screen Extract of Rationale of Sales


2. Market Reaction
Strangely, the market reacted positively (August 5, 2025) to the upcoming disposal as there is a +S$8.9Mil gain over book value that LREIT may use to distribute back to unit-holders. Short term view of "get rich quick" distribution among investors seems to be driving the rally in unit price of LREIT to S$0.575 per unit (+1.77%) since the release of the divestment announcement.


Personal Thoughts and Views
As an existing unit-holder of LREIT, I am extremely disappointed with LREIT management team's decision to sacrifice a good asset with 100% occupancy just for short term gains instead of cutting losses with Milan Sky Complex. In addition, we have not seen any concrete executionary results with regard to Sky Complex where occupancy remains in the doldrum at 81.6%. 

Saturday, 28 June 2025

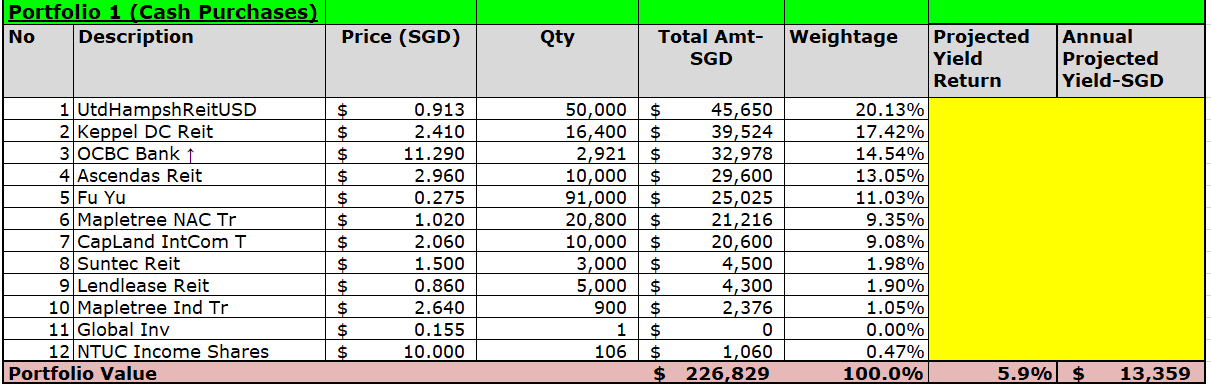
Investment Portfolios Updates (27 June 2025) - Net Investment of S$750K and Projected Annualised Passive Income of S$46K.

Singapore REITs suddenly sprang back to life with the anticpation of 2 more rate cuts in 2nd half of FY2025. More funds also moved from overseas markets into the local SGX. My gross portfolio managed to hit the above S$1.02Mil mark again albeit the see-saw ride from Donald Trump's erratic policies from import tariff fight with other countries (the most recent one is with Canada and sending US airforce to bomb Iran). Net investment (including cash) is approximately S$750K as at 27 June 2025. I guess this is not bad considering that I had cashed out S$10k from my unit trust bond funds for personal expenses usage.

1. Portfolio 1- Stocks Held in SGX Central Depository 

2. Portfolio 2- Margin Purchased Securities
(Note: My margin purchased securities has grown to a sufficient scale to sustain itself and can pay off annual financing charges as well as to gradually pay down the margin loan through dividends generated.) 
Have continued paying down my margin loan from S$272K to S$267K. Going forward, will target to bring the margin loan utilisation down to S$250k hopefully by year end in case Donald Trump screw up the world economies again.

In addition, I have also sold off part of my Keppel Corp stocks (1,000 shares) as its price hit over S$7.35 per share to recycle the capital into Alibaba (9988).

3. Portfolio 3 (with Tiger Brokers and MooMoo) 
(Venture into higher risk as well as capital growth stocks here)
I have added 400 shares of Alibaba when its price drop back to HKD110- HKD113 range over the past few months as it is now a cloud and also AI tech play on top of its usual core E-commerce business.

Also added 10,000 units of Lendlease Commercial REIT in end May 2025 when its price plunged to S$0.480 per unit. Its price has since recovered to S$0.525 per unit as at 27 June 2025.

4. Portfolio 4 (Endowus Unit Trusts & Other Investments)
I have taken out S$10K from my Higher Income Endowus portfolio for personal usage. Also did a bit of rebalancing and direct purchase of PIMCO bond fund as well as Pine Bridge Asia Pacific fixed income fund. 

In addition, decided to buy into the Fidelity APAC Dividend Fund to to reduce US equities exposure in my unit trusts portfolio as US market is way overvalued (near 52 weeks high and extremely high PE ratio for many US firms) right now. 

Parting Thoughts
I am keeping my fingers crossed that there will be at least 2 more rate cuts this year so that interest rates go down and REITs continue to increase their distributions.

Sunday, 25 May 2025

Lendlease REIT Fell Below $0.50 Per Unit- 7.6% Distribution Yield.


The recent Donald Trump madness has caused many SREITs to decline sharply again with US Treasury rates spiking due to lack of market confidence and demand. Equities such as REITs are thus also adversely impacted. For Lendlease Global REIT (“LREIT”), based on the last half year distribution of $0.018 per unit, this will mean an annualized distribution of $0.036 per unit. Since last market traded price is $0.475 per unit as at 23 May 2025, this translates to a high distribution yield of 7.6%

While LREIT is not affiliated with Temasek Holdings such as REITs from the Mapletree and Capitaland stable, it is nevertheless still an attractive retail REIT for further diversification. Its heartland retail mall of JEM and long tenancy of office block in JEM to the Ministry of National Development added further resiliency to its rental income base. I will scoop up more of LREIT if the unit price crash further. Not sure whether it will reach $0.450 or below per unit. I am seriously pondering how low can SREIT decline and despite the global market pessimism, I believe the light will shine one day for REITs.

Interestingly, I noticed that Choon Yuan from InvestMoolah had moved in to accumulate LREIT recently. Personally, I am looking to add on additional retail focused REIT such as LREIT and Mapletree Pan Asia Commercial Trust amidst the current storm if the distribution yield spikes further to near 8%.

Saturday, 15 March 2025

Lendlease Global Commercial REIT At All Time Low in March 2025- Dipping Below S$0.50 Per Unit At One Point.


Lendlease Global Commercial REIT ("LREIT") has dipped below S$0.50 per unit to S$0.485 per unit as at 6 March 2025. This is even lower than the COVID period and also the SREIT price tumble last year- as a matter of fact, this is an all time 5 year crazy low for LREIT. Hence I have taken the opportunity last week to add on 10,000 units @ S$0.485 per unit after going through the below thoughts process as well as risk assessments.  

1. LREIT Badly Battered By High Financing Cost and Empty Commercial Office in Milan
The higher interest cost has been severely affecting the results of LREIT. Moreover, the early termination of lease for a major tenant at its Commercial Office building Sky Complex added to its existing woes. So there is a key risk here if LREIT's leasing team is unable to fill up the vacant space fast enough.

2. Good News From LREIT on Singapore Office 13% Negotiated Rental Increase over 5 years.
On the Singapore JEM office front, there are positive upsides for LREIT With Singapore Office rental to Ministry of National Development at 13% Rental Increase.


3. Incredulous Distribution Yield of 7,42% From LREIT Relative to Risk Free Rate 10 Yr Govt Bond of 2.64%.
Based on 6mths ending 31 December 2024, S$0.018 per unit was distributed. Normalising this would be S$0.036 per unit on S$0.485 per unit which translates to 7.42% distribution yield. This is close to a +5% yield relative to a 10 year government risk free bond.  

In addition, with inflation being tamed in the US as well as worsening marco-economic conditions, probability of more rate cuts will mean higher distribution income in the future for all unit-holders. This is surely good news.

Parting Thoughts
After consideration of the various market factors, I have thus added additional units into LREIT as I thought that the upside in terms of further reduction in financing costs as well as upsides from Singapore properties will more than outweigh the potential downside risk resulting from the Sky Complex tenancy woes.  

(Note: On the CPF Ordinary Account front, I have recently invested S$20K of it into SGX REIT ETF. Will share more details on this in my future post). 

Monday, 15 April 2024

Lendlease Global Commercial REIT- Aggregate Leverage Computation and Good Buy?

Lendlease Global Commercial REIT ("LREIT") market price has remained in the doldrum despite the major JEM acquisition. Today, I will touch on how to compute the Aggregate Leverage ratio stipulated by MAS as well as my personal thoughts on whether LREIT is still a good buy at this juncture. 

Please see below for my latest video on YouTube channel. Going forward, I will be posting various exclusive investment contents only onto my YouTube channel. Please subscribe to my YouTube channel also to get the latest content for sharing.


Tuesday, 19 December 2023

Lendlease Global Commercial REIT Strange Restructuring of Major Office Lease To Reduce Tenant Concentration Risk.

This is really weird and funny. Lendlease Global Commercial REIT ("LREIT") announced on 18th December 2023 that it will be restructuring its long term Milan office lease of Sky Complex with Sky Italia in order to "reduce tenant concentration risk".  I find the header of the announcement extremely misleading and giving the impression that LREIT is the party which decided to review and downsize the major tenant, Sky Italia, on its own initiative. There are many ways to reduce tenant concentration risk such as embarking on future M&A to further reduce the impact of Sky Italia as a major tenant. Chasing after existing tenant to vacate office by a landlord to "reduce tenant concentration risk" when the lease has not expired is virtually unheard of in the market. The only plausible explanation is that the tenant must have approached the management of LREIT to re-negotiate a package deal for reduced footprint since the tenant does indeed hold an option to pre-terminate the lease (till 2032) over the entire Sky Complex in 2026.   
1. Negative impact of upcoming partial exit of major tenant on LREIT
As alluded to the above, a tenant wanting to cut space is bad news for any landlord. It also signalled that there maybe something wrong with the macro-economic environment. The vacancy rate for office real estate in Milan, Italy, varied greatly depending across different city areas from 4% to 16% based on Statista.com. Since Sky Complex is outside the CBD, it may be experiencing a higher vacancy rate issue and will take some time to fill up Building 3 which will be returned to LREIT. 
2. Good news that major tenant, Sky Italia, will compensate LREIT on 2 years worth of rental for Building 3 on top of reinstatement cost.
But not all is bad on the restructuring of the Sky Complex lease. The tenant, Sky Italia, will provide a consideration to LREIT of an amount equivalent to approximately two years of existing annual rent of Building 3 after its reinstatement in 1st quarter of 2024. 

This 2 years of compensation is a critical life line as well as creates much needed breathing space for LREIT while its leasing agents in Milan work on getting new tenants to gradually fill up all the vacant space albeit the possibly weak office commercial market. Any immediate filling up of space will be a bonus to LREIT.
Parting thoughts
Overall, I thought that the deal is a win-win for both LREIT and its tenant, Sky Italia. However, it does worry me on the financial status of Sky Italia since it decided to give up on one building to cut cost. Things may not be as rosy as it seems on the surface and fellow investors may want to closely monitor further developments in Milan. 

Monday, 18 September 2023

Lendlease REIT Offering Attractive 8% Distribution Yield- But Will Not Be Touching It For Now.

Lendlease REIT ("LREIT") unit price has been a disaster for over the past 1 year. From S$0.810 per unit to the current S$0.56 per unit, this is a <-31%> plunge in its market price in a mere 12 months. With a half year distribution of S$0.022453 annualized, this implied an 8% distribution yield. While I would love to add on to LREIT at its current weak unit pricing, there are a few worrying points that is making me hesitate to do any further accumulation. Let me elaborate further below: 
1. Rights Issue Maybe On The Table Due to Further Acquisition of Parkway Parade
LREIT has recently purchased a 10% stakes in Parkway Parade Shopping Mall. A rights issue maybe on the way for it to acquire more stakes or to takeover the remaining stakes. If the price of LREIT continue to remain in doldrums for some time and LREIT’s management called for a rights issue, the rights issue price is obviously going to end up 5% to 10% lower than its recent trading price per unit. In short, its unit price performance might worsen even more. 
 
2. LREIT Already Make Up A Substantial Part of One’s Portfolio
LREIT is currently making up 8% of my overall combined portfolios. For those folks who are in the same predicament as mine, accumulating more units in LREIT may mean even higher concentration risk. For example, black swan event like COVID hit retail malls extremely hard. 

In addition, as alluded to Pt 1, once there is a rights issue, existing unit-holders will need to take part to avoid dilution in their holdings.

3. LREIT Gearing Ratio Exceeded 40%
LREIT’s gearing ratio has hit an uncomfortable 40.6% as at 30 June 2023. In the event that the World entered into a global recession, this may lead to sharp drop in property valuation and in turn leads to breaches in MAS regulatory requirement or banking covenants.

Parting Thoughts
Personally, the S$0.56 per unit pricing as at 18 September 2023 and 8% distribution yield seems rather attractive coupled with the upcoming completion of the redevelopment of Grange Road open air car park into a multi functional event facility as well as having a long list of potential M&A pipelines from its Sponsor. Nevertheless, as aforesaid mentioned, I will probably re-deploy excess funds on hands into Endowus fixed income funds instead to ensure sufficient diversification.

Tuesday, 9 August 2022

Lendlease REIT Excellent Performance Post JEM Acquisition- High Distribution Forward Yield of 6.4%.

Lendlease REIT ("LREIT") announced a beautiful set of 2nd Half 2022 results post acquisition of Jurong East Mall ("JEM"). Its net property income for the same period was S$45.9Mil (increase of +S$19.4Mil or +73%) driven by the additional contributions from JEM as well as post COVID recovery of tenant sales in both 313@Somerset and also JEM itself. The tenant sales actually surpasses the pre-covid level. Distribution yield post JEM acquisition declared is S$0.01312 per unit for 31 March 2022 to 30 June 2022. Annualized yield would thus be S$ 0.05251 per unit which means a 6.4% distribution yield at the last trade price of S$0.82 per unit as at 8 August 2022. This is one of the highest distribution yield among other office and retail REITs on SGX. I also foresee further upside coming from LREIT in the next quarter announcement. A few quick highlights on LREIT:

1. Increasing DPU since listing on SGX

The above depicts the strong financial performance delivered by the management of LREIT for 2H FY2022 as well as for the entire FY2022. Note that its DPU has also been increasing since IPO. Not an easy task given the impact on COVID for the past 2 years. 

2.  25.8% of LREIT is occupied by financially stable tenants- Singapore Government and Sky
The offices portfolio of LREIT in Singapore and Italy are full leased to the Ministry of National Development ("MND") till 2044 and Sky Italia till 2032 respectively.  The MND office at JEM is subject to rental review every 5 years while Sky Complex is subject to annual rental review based on 75% of The Italian National Institute of Statistics consumer price index variation. 
From the diversified tenant base, we can see that the Singapore Government (MNC) and Broadcasting (Sky Italia) tenants made up 25.8% of the total tenants. LREIT thus continues to enjoy strong and stable cashflow from these 2 particular tenants for a long term as alluded to the above.  

3. Future upsides from upcoming Grange Road Carpark redevelopment into event space and potential acquisition of Paya Lebar Quarter Mall 
An independent cinema, hawker stalls and multiple event spaces are set to take over the 48,200 sq ft open-air carpark in Grange Road as part of major efforts to rejuvenate the Orchard Road area spearheaded by LREIT. This will be connected to the existing discovery walk linking up 313@Somerset and bring about increased in footfall and other synergies. 

Another major M&A in the form of Paya Lebar Quarter Mall is also in the future pipeline along with other Singapore properties held by its sponsor, the Lendlease Group.

Parting thoughts
Based on the current pricing of S$0.82 per unit, personally, I think it is very much undervalued by the market given the various upsides as discussed above. It is also giving out a forward distribution yield of 6.4%.

Wednesday, 6 April 2022

Lendlease Rights Issue Part 2- Preferential Tranche Now Open And New Subscription Method Available.

For those who have not subscribed for their Lendlease Global Commercial REIT ("LREIT") preferential rights issue, please take note that the closing date is on 12th April 2022 (Tuesday) 5pm. As I had mentioned in my last post, unit-holders who have no money or refuse to subscribe will be severely diluted by the super low ball price of S$0.72 per unit which is a 20% discount to the January 2022 peak of S$0.90 per unit. Personally, my thoughts are to at least subscribe at S$0.72 first and then sell them off at the higher last traded price of S$0.795 per unit (as at 5th April 2022) upon issuance if cashflow are tight. 

Application options for LREIT Preferential Rights Offerings (for those who held units directly in their own CDP account)
Some folks have emailed me or posted query with regard to the subscription methods. The usual traditional participating banks for ATM application are (i) DBS (including POSB), (ii) OCBC and (iii) UOB.

There is a new payment method via PayNow that had been implemented by SGX-CDP. 
Extract of LREIT Rights application via PayNow

I do not really like the PayNow method as it is not intuitive enough in terms of user-friendliness. Those using it please read carefully on the instruction manual sent out to unit-holders on how to populate the fields after scanning the QR code using your bank payment App for PayNow. The parts that I think may pose some challenges to users:

(i)  One needs to know exactly how to key in the reference field using a mix of security counter code along with the last 8 digit of your CDP account number. Some unit-holders might forgot to key in the Lendlease counter code or key in full CDP account number. The ATM application is clearer on these aspect with the detailed step by step screen;

(ii) You also need to key in the dollar amount of the total amount of rights plus excess in the dollar value field- I am sure there will be some lost souls here who will key the number of units here instead of the dollar amount or just key amount for rights but forgot the "excess" rights one wanted;

(iii) You need to ensure your PayNow daily limits are set at an amount exceeding the amount you need to credit for this exercise.

Parting thoughts:
I will probably still stick to the traditional ATM application for the step by step instruction appearing on the ATM screen to guide one through the application process for the rights plus excess application. I hope that CDP will work on enabling the rights issue to be done via the internet banking interface in future instead of just ATMs. Last but not least, the initial huge decline in price of LREIT upon the announcement of the right issue has somewhat stabilized. It is intriguing to see that there is now an arbitrage situation with significant upsides arising from the rights pricing and most recent ex-dividend market trading price of LREIT. 

(Note: Recently, there is an interesting case of rights issue being priced higher than market trading price. Yup, I am talking about the Mapletree Commercial REIT fund raising exercise to pay for the acquisition of Mapletree North Asia Commercial REIT).

Tuesday, 22 March 2022

Lendlease REIT Rights Issue- What You Need To Know To Avoid Severe Dilution And Boost Your Chance For A Quick Realised Gain.

Talking about when the rubber meets the road from my last post and all hell broke loose indeed. Lendlease Global Commercial REIT ("LREIT") announced on 22 March 2022 the impending kick off of the private placement as well the preferential rights issue of 29 units for every 100 units owned and wow, this is more than double the amount I was expecting. As I read on the fund raising document, I nearly fainted when they revealed the price of the rights issue to be at a whopping 9.6% discount to the weighted average market price- a low ball offer of S$0.72 per unit. Unit-holders who have no money or refuse to subscribe will be severely diluted by the super low ball price of S$0.72 per unit which is a 20% discount to the January 2022 peak of S$0.90 per unit. 
I also expect the market price of LREIT to drop further upon the resumption of trade. Preferential unit-holders need to be aware of the dire predicament that they are in and to come out of the gate storming once the preferential rights issue commenced on 4th April 2022-which is a mere short 2 weeks to raise funds. Also, there is no escape, folks who tried to evade the rights issue by selling most likely will be  facing further decline in the already low price once trading resumes; and those who purchase LREIT recently and refused to subscribe will face heavy dilution in their holdings. LREIT management has screwed everyone by the low price of S$0.72 per unit on top of demanding 29 units subscription for every 100 units owned.
Other key points to note:
1. Those who have lost their ATM card or forgot their ATM password please ensure you go to your bank to rectify the issue before the kick off of the preferential tranche.

2. For those who received from your stock brokers the invitation to participate in the private placement, note that you will not be eligible to participate in the Preferential Offerings if you decided to take part in it to get more units. The most discount for this exercise for the new units will be from the Preferential tranche of S$0.72 per unit whereas the Private Placement tranche will be priced between S$0.725 and S$0.740. 

3. Opening date of the Preferential Offering is on 4th April 2022 (Monday 9am) and ends on 12th April 2022 (Tuesday 5pm)

4. For those who bought units under nominee brokerage accounts instead of your own CDP,  please call up your brokers immediately if you do not receive any e-notification or physical letters to subscribe for the rights issue.

Will market price of LREIT drop below S$0.720 per unit?
Well, you never know. If the Russo-Ukraine war suddenly became a World War 3 with US and its European allies dragged in, then this is definitely a possibility but personally, I think such events will be remote for now. 

Parting thoughts
For long term investors, I think that LREIT offers an attractive dividend yield of over 6.2% and possibility close to 7% forward yield based on the current low ball offer. The recurring tax savings of S$5.6Mil from Jurong East Mall (JEM) being restructured into a REIT and also the redevelopment of the 48,200 sqft car park near 313@somerset into a new multi-functional event space do also provide further potential upsides in the short to mid-term. On a longer term basis, there is the potential yield accretive acquisition in the pipeline of Paya Lebar Quarter (PLQ). 

Thursday, 10 March 2022

Lendlease REIT Plunged 11.6% Since Beginning Of The Year-Curse of the JEM Acquisition.

Ever since the announcement by Lendlease Global Commercial REIT ("LREIT") on 14 February 2022 (Valentine's Day coincident release?) that it will be acquiring the remaining stakes in JEM, its unit price has taken a wallop. No, this is not just the impact of the Ukrainian Russo war or global interest rate hikes, but some investors seems to be upset at certain aspects of the deal such as the upcoming issuance of so many new units which reduces the NAV of LREIT to a mere S$0.80 per unit. For most companies, if they announced a mega deal, prices theoretically should go up but LREIT went all the way down from its S$0.90 per unit at beginning of the year till it hits an all time FY2022 low of S$0.795 per unit on 8th March 2022 a day after the EGM. So what exactly happened to LREIT? A mega-deal now became its Achilles heel and curse? 
1. Main query by some unhappy unitholders to directors of LREIT-NAV  decline to S$0.80 per unit
NAV per share declined to S$0.80, which is not better for unitholders as it means that that acquisition price is too high. The drop is due to the high number of new units to be issued. However, considering the fact that NAV per unit before the acquisition for FY2021 is only S$0.81 per unit, I think one can actually live with this slight drop. It is strange that after the EGM on 7th March 2022, the price did not even bounced up. 

Personally, I thought that the Profit Before Tax is the most important as it will determine the ultimate distribution payout (DPU) to unit-holders-please see paragraph 2 below.


2. Distribution Yield improves by 1% point from 5.2% to 6.22%
This is where it gets very interesting. Price per unit of LREIT is around S$0.90 at the beginning of the year. At a pre-acquisition DPU of S$0.0468, this represented a yield of only +5.2%. However, prices after the EGM hovers around S$0.800- S$0.805 per unit. If we further add in the impact of GEM acquisition, this will boost the DPU to S$0.0501 per unit. This is a yield of +6.22%. For passive income investors, LREIT suddenly seems to be a better deal considering other REITs such as Capitaland Integrated Commercial Trust distribution yield is only around 5%. 

In addition, the GEM acquisition adds much needed diversification into LREIT's only 2 properties of Sky Complex and Somerset 313 @ Orchard. LREIT's new offices of Sky Complex in Italy and GEM Offices now consists of 2 extremely resilient recurring rental income streams from Sky Italia, a subsidiary of Comcast Corporation (one of the world's largest broadcasting and cable television company) and also the Ministry of National Development of Singapore respectively. 
However, there are some some worrying points to take note of- please see paragraph 3 below. 

3. Issuance price and sufficient cash on hand to avoid dilution 
(i) One unknown factor of concern to me is how low the rights issue of units will get priced. The illustrative example used  in the presentation materials states that this is S$0.82 per unit. Obviously, if one is going to issue at S$0.82 per unit when the market price is only S$0.805, this rights issue will never work. Why would one subscribe to a higher priced rights issue when one can get it from the market at a lower price?
Extracted from "Reponses to Questions from Unit-holders" by LREIT Management-1st March 2022

(ii) The other worrying part is that to acquire the remaining 68.2% in JEM, LREIT will need to raise financing of S$1,790Mil. This is an enormous eye popping sum. The elephant in the room is how much is the share of contribution for retail investors like us who do not have deep pockets. From the above extract, it seems that 40% (S$718Mil) of the required funds will need contribution from all unitholders (excluding the Sponsor). If including the sponsor's share and the recent approval to issue up to 1,265 Mil units, price of new units can go down to S$0.752 per unit.

(iii) Last but not least, for retail investors who entered at S$0.90 per unit at the beginning of the year and no longer has any spare cash, it will not be fair if latter institutional investors or existing investors managed to get new units at say S$0.752 per unit. Retail investors thus need to commence raising cash on hand position to prepare and participate in the upcoming preferential retail tranche rights issue. 
 
Parting Thoughts
Based on the above, the JEM acquisition can be either a curse or a blessing in disguise depending on when one bought into LREIT. Personally, I think that the current price of S$0.805 per unit seems to be relatively more attractive to some of the other retail & office REITs out there on SGX. There will also be recurring tax savings of S$5.6 million per annum due to the restructuring of the fully acquired GEM into the REIT structure. I do not mind earning a 6.2% distribution yield annually while waiting for capital appreciation upsides. 

Sunday, 5 December 2021

Investment Portfolios Updates- S$619k (3 Dec'21)- Equity Portfolios Facing Challenge of Omicron COVID Variant

The stock markets tanked recently due to the Omicron variant. I have sold off 42,000 units of my SPH REITs under my Portfolios to raise cash level at the start of the week. Subsequently, prices of local bank stocks and REITs dropped further and I took the opportunity to buy into more OCBC and Mapletree Industrial Trust while retaining some cash. My investment approach is still primarily an income focused strategy using cash account (Portfolio 1) supplemented by my Portfolio 2 opened with Maybank Kim Eng and leveraging on their Margin facilities-current projected dividend income is +S$44.6K per annum. For me, no point in timing the market by selling a major part of the portfolio as it is better to stay invested in order to continue to receive dividends and not missed out on opportunities such as new M&A announcements.  

1. Portfolio 1- Stocks held in SGX Central Depository
Not much action here except for selling off of SPH REITs to buy into 1,000 OCBC shares while retaining cash of around S$10K here from the sales.

2. Portfolio 2- Margin purchased securities
(i) The past 2 months has been rather interesting. I took a calculated risk with my margin account by buying into SPH shares after the announcement of Keppel Corp proposed acquisition at S$2.01, figuring that the market pricing then at around S$1.90-S$1.93 range, offers the most probable upsides with S$2K in profits expected with the successful completion of the offer. Next, Cuscaden Peak came into the picture to start the bidding war and I closed off my margin position in SPH shares recently to walk away with +S$6K profits (S$2.34 per share exit) as I do not think there will be another 3rd party offer.

(ii) I have reduced my holdings in retails REITs such as Lendlease REIT and SPH REIT. Anti-COVID measures will hit retail badly if the Omicron strain spreads widely.  

(iii) I have also increased my holdings in Mapletree Industrial Trust. I figured that it is prudent risk management to have the backing of strong sponsor like Temasek in the event that the COVID crisis worsen and there is a need for sponsor's cash injection should the property value plummet like in 2008. 

3. Portfolio 3 (with Tiger Brokers)- Venture into higher risk as well as capital growth stocks here
However, my venture into China Alibaba continues spiraling downward non-stop with concern over forced delisting by China regulator from NYSE and I am taking a huge hit of unrealised loss of almost <S$9k> from it. I will probably do a short write-up on Alibaba in my next post. 

Basically, I think the fundamentals of Alibaba are still intact despite the crackdowns by China regulatory and the lower growth rate. Just this week, I have invested another 100 shares of Alibaba at a price of HKD121.6 per share. But I think this is the last batch of Alibaba shares that I am buying to mitigate the risk of holding excessive Alibaba stocks.

Parting thoughts
I am looking forward to receiving further dividends in December 2021 for further re-investments. Let's see how the market reacts next week and whether there is further blood-bath due to the Omicron variant. However, personally, I do not think Omicron will be a repeat of the 2020 March crash as current vaccine surely still must have some effects (despite reduced efficacy) on the new COVID strain and chances of world-wide lockdown again is slim. I will continue buying in piecemeal to exploit the current market decline.     

Monday, 7 June 2021

Lendlease Commercial REIT Diversification Into Suburban Shopping Mall- Additional Acquisition of JEM

Lendlease Commercial REIT ("LREIT") just announced a proposed additional acquisition of stakes in Jurong East Mall (JEM)  for S$204.1Mil from 2 funds holdings shares in it. LREIT has also offered up to another S$178.2Mil to other 3rd party investors in the Lendlease Asian Retail Investment Fund 3 Limited for up to another 19.8% interest stake if they are keen to sell off their stakes. This will raise LREIT's overall stake in JEM from 3.75% (purchased in Oct''20) to 31.8%. In a way, LREIT seems to be struggling to obtain a 51% majority stake in JEM due to the different external unit-holders holding a single completed property.  

Some key highlights to note:

1. Future M&A exercise going forward is expected to progress at a snail's pace similar to current situation since IPO
One thing that I do not like about the way Lendlease group funded its developments in Singapore is the use of several funds to hold a single development project with multiple major stakeholders taking part in it. This is similar for its current Singapore holdings such as Parkway Parade and Paya Lebar Mall & offices.

Hence to do a 100% acquisition of a single property at any one time is almost impossible due to different investment objectives of the shareholders in each of the investment fund holdings stakes. JEM is a perfect example of a bite size acquisition gradually over time to buy out 3rd party stakes if they decided to offload it at different periods in the future.

Such piece-meal acquisition is no doubt a waste of money as professional fees such as legal fees and valuation fees will need to be incurred again and again albeit is of a small amount relative to the overall valuation of the piece-meal purchase considerations.

2. The JEM acquisition move beneficial to LREIT?
Yes. this acquisition of additional stakes in JEM is expected to be 3.6% DPU accretive. The acquisition is expected to be funded by proceeds from its recent issuance of S$200Mil of perpetual securities, existing cash balances and debt facilities. 

2(i) Perhaps the best part of JEM is that its office component is 100% fully leased to our Ministry of National Development on a 30 years lease. Currently, 24 years of the lease remains. Taking into account its other office portfolio Sky Italia in Milan (also leased to a strong tenant), its office portfolio will provide resilient streams of rental income even during economic downturns. 

The office components post acquisition will mean LREIT having a 28% business segment that is resilient to major economic crisis. This is a hidden gem in the JEM acquisition.

2(ii) JEM's suburban retail mall has established itself as one of the dominant retail mall in Western Singapore with a direct access to Jurong East MRT station. JEM is well tenanted with a high overall committed occupancy of 99.7% as at 31 March 2021. Essentail services trade mix such as F&B services, supermarket and hypermarket account for 58% of its Net Lettable Area. 
Breakdown of New Portfolio by Asset After Acquisition

Breakdown of Portfolio by Asset Segment After Acquisition


The acquisition of JEM thus allows better portfolio diversification from its crown jewel 313@Somerset at Orchard Road which in theory should bring the expected risk premiums down from the current market valuation.
 
3. Changes in LREIT Senior Management from 1st June 2021-Good or Bad?
LREIT's chairman, Mr Anthony Lombardo has stepped down as chairman to become the Group CEO of Lendlease Group with effect from 1 June 2021. However, he will remain on the board of LREIT as a non-executive director. 

Ms Ng Hsueh Ling will take over as chairman of LREIT. She has been the Singapore MD and chief investment officer at Lendlease since 2017 and is also the key executive of Lendlease Retail. Ms Ng was also previously the CEO of Keppel REIT's manager and also ex-CEO of Ascendas Korea & Japan just before joining Lendlease group. 

Good to see LREIT is still in good hands and as a matter of fact, even stronger connection to its Australian sponsor from the designation change.

Parting Thoughts
Based on projected forward dividend yield (over next 12mths) of at least 7.1%, the current market valuation of S$0.77 per unit appears to be still giving a good return considering LREIT's main portfolio components are focusing on providing retail space and also office properties backed by superstar tenants in Milan and Singapore.