Showing posts with label Dasin Retail Trust. Show all posts

Wednesday, 4 December 2024

Possible Stock Market Price Manipulation by Dasin Retail Trust Non-Executive Director and Ex-CEO of Trustee Manager.

Wow, another shocking news released by the current management of Dasin Retail Trust ("DRT") on 2nd December 2024. Police reports, reports to Monetary Authority of Singapore and Singapore Stock Exchange have been lodged after the current management discovered "certain documents" in the office previously occupied by DRT's ex-CEO of the Trustee, Ms Wang Qiu. I wonder whether there are any more cans of worms hidden by the previous management team and the non-executive director Zhang Zhongmin.

There have been too many bad news over the past 2 years from DRT:

Parting Thoughts
I am glad that I have sold off all my DRT units by end of August 2022. For all we know, DRT maybe virtually worthless now albeit the market trading price at S$0.033 per unit as at 3 December 2024 (Tuesday). 

Sunday, 3 September 2023

REITS and Dividend Investment Strategy Extremely Dangerous!

Haiz, just saw another video by a renowned YouTuber roasting REITS and dividend investment approach. First REIT, Manulife US REIT, Prime REIT, Keppel Pacific Oak, Dasin Retail and Parkwaylife REIT were all quoted as perfect examples of why it is a bad idea to be invested in REITs for dividends (think a few weeks ago, he also mentioned that investing in local banks DBS, UOB and OCBC is extremely dangerous). Apparently, stock picking is frowned upon and branded as extremely dangerous with potential huge loss of invested capital. Index funds such as SPY500 or even REITS ETFs are the best way to invest for common folks as asserted by the YouTuber. I will just make a few quick highlights of my thoughts:

1. Most retail investors are not silly and practice adequate risk diversification.
I have not seen fellow investors with First REIT or Manulife US REIT making up 50% or 100% of their portfolio. If one has adequate diversification and holding on to a basket of REITs, it is as good as buying into a REIT ETF. Even if a REIT went underwater, one would be able to quickly recover from such losses. 

2. Index Funds like SPY500 are the safest and highest proven return track record than stock picking?
I think you will be very surprised to hear that from 2000 to 2009, SPY500 index actually performed badly and returned a negative 9% (inclusive of dividends).  I was surprised to hear that too from Gregory Van, the CEO of Endowus on one of the YouTube videos. This has a bearing on point 3 below.

3. Index investing does not allow one to have recurring cash distribution without hurting capital at the worst market sentiment period.
As alluded to point 2, for those retail investors like myself who needs frequent cash distributions, using Index funds like SPY500 as strategy will mean selling part of the units at the worst possible time during lousiest market sentiment to raise cash-I think this is a very bad idea. 

Parting thoughts
I think that everyone has their own unique needs when they craft out their investment strategies and approaches. Investing in REITs and local banks to me will still form the core of my investment. This is not to say that I disagree with index investing. For the record, I have been using SPY500 as an investment avenue for my CPF ordinary account funds since late last year and derive good realised returns during the recent rally where I sold them off. I do recognize the excellent risk diversification with an index investment that is broadly diversified into hundreds of top companies and sectors with a long term proven historical return. 

Tuesday, 22 August 2023

Dasin Retail Trust Trading Price Possibly Being Manipulated By An Unknown Individual Investor- Investors Beware!

Hi Folks, for those who are trading in Dasin Retail Trust ("DRT"), please be very careful. SGX Regulators have put up a notice that they have observed an individual investor who have pushed up DRT unit price by 46% during an intra-day low of S$0.063 per unit to S$0.092 per unit on 16th August 2023. There were various instances of possible price manipulation over the past month to maintain its price despite the bank loans default notice served by the bankers of DRT. 
SGX regulators have referred the matter to the relevant authorities for their necessary action. Do tread with caution for those who are bargain hunting in DRT. Price may crash or trading may get suspended in the worst case scenario for DRT unit-holders. Take care and have a great week ahead!

Tuesday, 4 July 2023

Dasin Retail Trust Valuation Dropped By 23%-Auto Trigger Breach Of All Offshore Facilities Covenants.

I was stupefied to see that Dasin Retail Trust ("Dasin") announced a trading suspension on 3 July 2023. Upon delving in for a deeper look, I realised that Dasin had also earlier released a valuation report by Jones Lang LaSalle which announced a shocking 23% (-S$350Mil) plunge in fair valuation of its investment properties as at 31 December 2022 relative to FY2021. In FY2021, S$127Mil were already written down. While more and more cans of worms surfaced, I did not expect the end of Dasin to come so soon as the management seems to be able to get special short term extension time and time again of loan facilities from its bankers for the past 2 years. But alas, this 23% plunge in valuation maybe the final straw that breaks the camel's back- it means an  automatic breach of the gearing ratio, interest coverage ratio and loan to valuation ratio which Dasin is obliged to maintain under its Offshore Facilities. 

Worst Not Over
I reckon that the 23% plunge in fair valuation is just the tip of the ice-berg. It was reported in various online media that a number of shopping malls in China are now facing existential crisis despite the re-opening of China post COVID. 

The offshore bankers may finally decide to throw in the towel and press for the liquidation of Dasin to try to recover whatever they could from the bad debt. The fire-sales of the shopping malls portfolio of Dasin may lead to another 50% plunge in valuation. 

Parting Thoughts
If the trading suspension does not get lifted anytime soon, it will mean that Dasin is on its way to face the same tragic fate as Eagle Hospitality Trust. The attempt to raise funds by selling one or more malls has been mentioned again and again by the management of Dasin but no actual corporate action has materialized thus far. It does not help that its Sponsor (Zhongshan Dasin Real Estate Co.,Ltd) is facing financial woes and will be unable to rescue Dasin unlike the case of Manulife US REIT. Worst is that the sponsor & the current manager (Sino-Ocean) are having infighting- law suit has been filed- over the control of Dasin.  

Tuesday, 25 April 2023

Dasin Retail Trust On Verge Of Collapse-The Can Of Worms Finally Got Revealed With Sponsor In Deep "Sheep"!

Wow....Dasin Retail Trust ("DRT") which has been keeping a low profile lately released not just one but three bombshells to investors on April 24, 2023. The gist of the announcements is that Zhongshan Dasin Real Estate Co.,Ltd , the Sponsor, of DRT is facing a myriad of law suits (a whopping 113 cases at least) of approximately S$338Mil against it since 2020. This piece of pertinent information I believed must have been well-known to the syndicated bankers hence their reluctance to re-finance the syndicated loans unless DRT reduces the quantum of the loan, as they need to cut down on their credit risk exposure. In addition, I reckon that the Sponsor has also been deliberately withholding this information from the Trustee-Manager of DRT in order to prevent a confidence crisis which will lead to a domino chain effect collapse that will eventually affect DRT adversely. There were also at least 9 existing equity freezes against the Sponsor's equity interests in some of its subsidiaries due to construction project contract disputes. The Sponsor of DRT is currently also listed on the "Blacklist of Defaulted Parties". This revelation is too drama and deserved to be filmed into a financial disaster movie to warn retail investors the danger of buying into Chinese companies.

1. With this can of worms officially open, how on earth is DRT going to get the syndicated lenders to re-finance its expired bank loans?
DRT tried to end this off optimistically by commenting that there is still no clear evidence that this can of worms, opened at this particular juncture, has any effect on the perception of its syndicated lenders.  

2. Valuation woes for DRT-S$652Mil of investment property valuation vaporised into thin air within 2 years?
In 2021, S$127Mil were written down. This got worst in 2022- there was a sudden sharp decline of -S$525Mil (-23%) in independent valuation of all its shopping malls portfolio as at December 31, 2022. This effectively means net equity of DRT dropped by an astounding -50%. One of the reasons was due to the cancellation of the Xiaolan Master Lease and E-Colour Master Lease due to related company default of rental payment. Other factors like negative rental reversion as well as higher vacancy rates led to the severe plunge in valuation of its investment properties.

The key question is this, even with an adjustment of -23% to fair valuation, is anyone certain that the remaining valuation can be trusted? Is it really worth this amount or actually another 50%-60% write down needs to be buffered in especially if the bankers exercised their rights and ask for a creditor liquidation of all assets at firesales prices. As with all fire-sales like what happened to Eagle Hospitality Trust, the bankers will get most of the proceeds with very little left-over (or none at all) for DRT unitholders and other creditors.

3. Other woes
One of DRT major anchor tenants, Carrefour China, has gone for early termination of its 20 years lease from December 28, 2014 of 191,000sqft at Ocean Metro Mall. Ever since the 2nd half of 2021, Carrefour China has not paid the rent of S$1.4Mil as at 31 March 2023. This is also complicated by a counter-claim by Carrefour China against DRT of S$1.43Mil for reimbursement of renovation costs.

This begs the question of can we even trust the financials of DRT and that there are no more defaulters?

Summary thoughts
Originally in Sep 2021, I was thinking that there is a high return potential from taking calculated risk into DRT as investors have been punishing it unduly and its unit price will eventually bounce back to at least S$0.70-S$0.80 per unit. I can only heave a sigh of relief that I have long exited my various small bite-size foray into DRT in 2022 after the many continuous red-flag signals. Personally, I think that this is a real classic case of catching a falling knife along with many major surprises hidden by its management and Sponsor. DRT is in a race to the bottom and there is the possibility that one can end up in a death spiral quickly with DRT. 

Friday, 3 March 2023

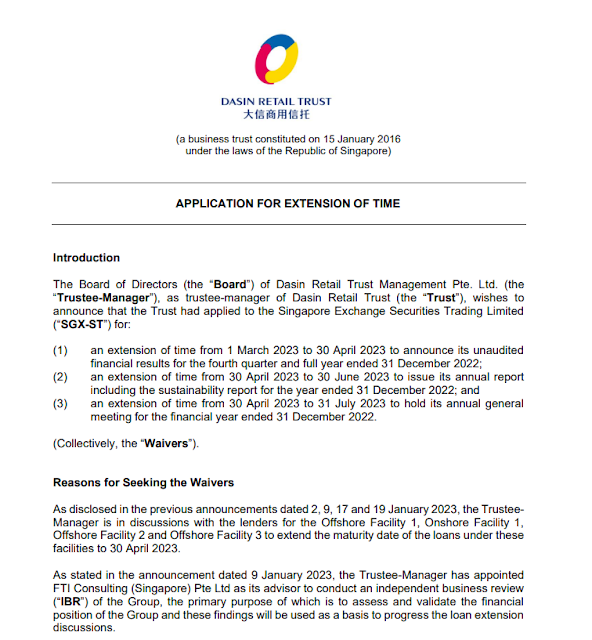
Dasin Retail Trust Applied to SGX For Extension Of FY2022 Financial Release- Going Concern Issue Unresolved.

On 1st March 2023, Dasin Retail Trust ("DRT") has indirectly admitted that it is on the verge of financial collapse. It just could not release its full year financial results for FY2022 by March 2023 and has requested an extension from the Singapore Stock Exchange. The main stumbling block for accounting is that the DRT management does not know whether to release the financial statements on a going concern or non-going concern basis while pending further "extension negotitation" from all its bankers with regard to its debt restructuring plan by 30 April 2023. Yes, DRT has been asking for extension from its bankers again and again but to no avail...seems more like buying time before their eventual dismal. Luso International Banking Limited has already fired the first salvo of shots and issue their letter of demand to DRT for default of bank loan. Till now, we have not seen any concrete plan from its White Knights (a "reputable" Chinese Entity currently and not sure what happened to another rescue plan the year before) .
Extract of 1st March 2023 Announcement
Parting thoughts
Will DRT survive its debt crisis? Will the White Knight rescue materalise besides empty talks and memorandum of understanding? Well, it seems to be a situation of high risk and high return for those seeking to exploit the current uncertainty and buying into DRT. As at 2 March 2023 (Thursday), unit price has dropped below S$0.200 per unit to S$0.195 per unit.

Friday, 20 January 2023

Dasin Retail Trust In Deep Trouble- Letter of Demand Received From Banker For Default of Loan.

Dasin Retail Trust ("DRT") found itself currently in hot soup when one of its bankers, through its lawyers, issued a statutory demand letter to its management. The demand letter dated 10 January 2023 declared that DRT is openly in default of the facility agreement entered into on 15 December 2022 for USD13.1Mil. This first firing of shot by Luso International Banking Limited may complicate the syndicated loan extension by other banks (yes, DRT has already applied for numerous extension of its syndicated loans as it has been unable to repay the debt) and sent DRT into an upcoming forced liquidation and fire-sales of all its investment properties. 


What on earth is happening to DRT with its endless pleas to bankers for loan extension?
The syndicated bankers are not willing to continue lending to DRT unless they do a partial repayment of the total sum to pare down on debt level. DRT management thus have been struggling to find a way to raise capital to reduce part of its debt in order to keep their bankers happy and ink a deal for long term loan renewal instead of the current knives being dangled at its neck with a short 3 months to 6 months of extension.

The recent trouble with Luso Bank seems to suggest that the actual cashflow of DRT is not as healthy as it seems. Back during the half year results release, DRT did not declare any distributions by giving the reason that it needs to be prudent on cashflow in view of continued uncertainties arising from COVID-19 situation in China. Apparently, its business operations situation must have worsened in its 2nd half of the financial year.

Parting Thoughts
I am glad that I have sold off all my DRT units by end of August 2022 as I had enough of the poor management as well as a lack of transparency and timely release of pertinent information. Personally, I am very skeptical of the Net Asset Value of S$1.25 per unit reported by DRT as at 30 June 2022 in consideration of worsening future cashflow from its business operations and higher present value discount rate in view of higher interest rate environment. As at 20 January 2023, its price has declined 6% from a day earlier and is trading at S$0.230 per unit after the release of the news.

For all we know, DRT units may well be already worthless especially in the event that its investment properties fair value needs to be adjusted by more than 50%. An upcoming fire-sales is the perfect storm that DRT need to watch out.

Monday, 15 August 2022

Dasin Retail Trust And Investors In Trouble- Loss of S$56.4 Mil for 1st Half of 2022 And No Distribution Being Paid Out Red Flag.

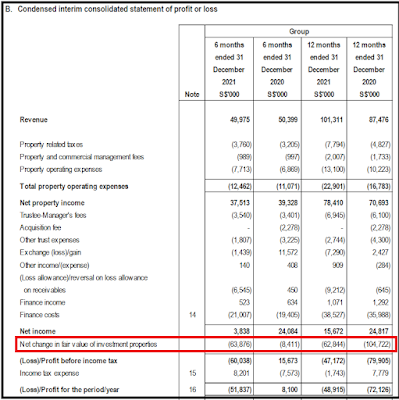
Dasin Retail Trust ("DRT") just released a shocking set of 1H 2022 results whereby its investment properties valuation went down another <S$64Mil> for the 6mths period ending 30 June 2022. This is not including the <S$62.8Mil> written down taken for the previous financial year ending 31 Dec 2021. The total of <S$126.8Mil> of fair valuation being written down within a year makes one wonder about the real valuation of their balance sheet items. DRT also took a <S$11.4Mil> allowance hit for the 1H 2022 due to impairment of trade receivables from tenants. Notwithstanding the aforesaid mentioned, the worst news was that the management of DRT decided not to pay out a single cent of earnings in distribution for its 1st half using the pretext of prudent working capital management in the face of potential worsening of COVID outbreak in China.
Worsening financial health and unable to get back long outstanding debts owed by tenants.
For me, the danger signs of DRT in either bankruptcy or forced liquidation has been increasing and the last straw is the lack of a single cent of distribution for 1H 2022. I will be bailing out of DRT and withdrawing the bulk of my funds-leaving only S$500 to S$600 in capital (in the event that DRT survived the imminent business crisis). S$751Mil of loans remain due by 31 December 2022 even after so many rounds of loan extension by the bankers. Outstanding debts allowances has also ballooned to <S$11.4Mil>.
Sales of investment properties to raise cash to partially repay bank loan demanded by bankers
The management of DRT has been unable to conclude the sales of some of their shopping malls to raise cash despite only about 3 more months left in the loan extension. Extremely slow execution means that the potential buyer is also having doubts with regard to the quality of the assets being put up for sales. DRT could be on its way to a rights issue or forced liquidation of assets at firesales price if the bankers decided to take action to mitigate their risk exposure.

Parting thoughts
From the perspective of minimizing risk of total losses of capital, I have drastically reduced my stake in DRT by selling off 21,000 units immediately. Personally, I think that DRT management has neither been very transparent in the handling of its syndicated loan re-financing exercise nor timely in its routine operational updates. I also have serious reservation on the declared Net Asset Value of S$1.25 per unit asserted by the management. S$1.25 per unit may seemed like a lot of buffer and room for any black swan event or financial fraud. However, from the collapse of Eagle Hospitality Trust we can draw some parallel of what else may happen. The subsequent long drawn restructuring process ended up in the Trust becoming beyond saving. DRT may well be worthless if either the restructuring process drags on or the realised valuation of the investment properties is only at 50% of its current value posted on its statement of financial position- there is now a distinct high probability based on the recent turn of event. All the very best to other contrarian retail investors still holding on to DRT.  

Sunday, 3 July 2022

Investment Portfolios Updates- S$630k (1 July'22)- Uncertainty in US Office REITs Occupancy and Mounting Losses from Keppel DC REIT

The last 2 months has been a blood bath for my investment portfolios in banking stocks and REITs. The net assets for investment thus went down to S$630k from the S$640K during my last review at the end of April'22. The good thing about being an income focused investor is that I am not too worried about the fluctuations in valuation due to market volatility as well as unrealised losses. My only concern is whether the stream of passive income from dividends/distributions from investee companies will be drastically impacted if there are fundamental changes to the business. Expected dividends per annum now approximates S$60K at gross level and S$51.2K at the net level after accounting for financing charges from utilization of my margin facility with Maybank.

The COVID downturn that happened 2 years back was another creature altogether with devastating economic lockdowns leading to an almost immediate more than 50% cut in dividends & distributions. I believe that the upcoming recession will not lead to such drastic cut in dividends & distributions and that my current portfolio can ride out any incoming headwinds.  

1. Portfolio 1- Stocks held in SGX Central Depository 
(Note: This portfolio is designed to provide immediate dividends for use (if required) as it is under my own CDP account and the dividends credited goes directly to my bank account.)

The only adjustment I made here was to acquire additional units of the undervalued United Hampshire US REIT which focuses on grocery retail tenants that has proven itself to be resilient even during the COVID crisis. On 9 June 2022, it was announced that the REIT will be acquiring Upland Square Shopping Center in Montgomery, Pennsylvania for US$85.7Mil. This DPU accretive deal will push up future annual distribution yield to 10.38% based on previous closing price of US$0.610 per unit. Please see "United Hampshire US REIT Acquired New Grocery Anchored Shopping Center- Improved Forward Distribution Yield Of 10.38% Per Annum".

2. Portfolio 2- Margin purchased securities
(Note: My margin purchased securities has grown to a sufficient scale to sustain itself and also to repay annual financing charges as well as to gradually pay down the margin loan through dividends generated.) 
My data centre REITs and US office REITs performed horrendously. UOB and OCBC stock price also took a beating during this dark period. I have sold off a substantial portion of my UOB and OCBC stocks to take profits and also to reduce my leverage by S$10k. I have also bought additional S$10K worth of Keppel DC REIT when its price plummeted to below S$2 per unit (at S$1.94 per unit in June'22). 

For US Office REITs, a number of analysts have high targeted prices for Prime US REIT, Keppel Pacific Oak REIT and Manulife US REIT. However, I am not as optimistic at all as I am seeing trends of decreasing occupancy in some of their quarterly operations reporting. The post COVID economy has escalated the remote working culture that sees possibility of a permanent decrease in required office space by companies.  As such, I have not made additional investments into the US Office REITS albeit the crazy low prices- one could end up catching a falling knife.  Please see "Manulife US REIT High Distribution Yield of 8.67%- Rosy Future Or Just A Value Trap?".

3. Portfolio 3 (with Tiger Brokers)- Venture into higher risk as well as capital growth stocks here
(i) Added 400 more shares of Alibaba (HKEX 9988) at an average cost of HKD83 per share.  


(iii) Dasin Retail Trust has good news recently on 20 June 2022. Its bankers has allowed it a 6 months syndicated loan extension (instead of the previous 3 mths) while it explores sales of its 2 biggest shopping malls to pare down debt. Investors thus get to see another distribution from Dasin for the 6mths ending 30 June 2022.

In addition, it was reported that on 22 June 2022, 50 million units of Dasin Retail Trust representing 6.3% of total units, changed hands at a premium of S$0.345 per unit relative to the average of S$0.30 market transactions per unit. On 3rd June 2022, Harvest Private Wealth Thematic Fund has also increased its stake in Dasin to 8.45%. Current distribution yield hovers around 16% with NAV of S$1.41 per unit.

Summary:
I look forward to the upcoming dividends and distributions in Q3 2022. For now, I think that I will be adopting a wait and see stance and will be building up my cash reserves on hand and also paring down my margin loan to prepare for the worsening economic downturn due to the relentless increasing of borrowing rates by the US Federal Reserve in their fight against inflation..

Monday, 21 March 2022

Dasin Retail Trust Unable To Renew Syndicated Bank Loans For Long Term- Forced to Sell 2 Shopping Malls in Guangdong Province.

Dasin Retail Trust ("Dasin") made a shocking announcement on Sunday (20th March 2022) that it has entered into a non-binding memorandum of understanding ("MOU") with Wuhu Yuanche Bisheng investment Centre ("Purchaser") to explore the sales of Shiqi Metro Mall and Xiaolan Metro Mall in Guandong Province. This was a big surprise to me as instead of announcing whether the current syndicated loan (that has expired on 19th March 2022) has been extended for another 3 months, it went on to announce this first. Anyway, this is a sure sign that the syndicated loans bankers must have some serious concern on the entire Dasin for them to be only willing to give short-term extensions for the past 2 rounds and after another 3 months, no progress has been made. I will put up some points to take note of here on the various uncertainties still plaguing Dasin in spite of the upcoming sales of investment properties to raise cash for loan repayment. 
1. Syndicated bank loans default and unit-holders still entitled to the payout on 30 March 2022? 
The key issue currently is whether Dasin Retail Trust is in default of bank loans. A default will mean that the distribution being declared for 2nd half FY2021 cannot be paid out on 30 March 2022. Bank loans usually have extra terms and conditions imposed on the entity upon default. This is exactly what had happened to the last distributions which were being withheld due to objection by the bankers of the demised Eagle Hospitality Trust.

This pertinent question went unanswered as at 22 March 2022, 10.15am. I am flabbergasted by the lack of inquiries by our SGX regulatory team and have written in to SGX to raise my concern on the lack of transparency and the lack of prompt disclosure by the management team of Dasin. 

2. Sales proceeds to be use to repay Dasin's existing syndicated loans and working capital.
The net proceeds from the sale of the properties shall be used to repay the Trust's existing syndicated loans and the remainder if any for working capital purposes. The million dollar question here are:

(i) What is the sales price of the 2 properties given the seemingly urgency to offload them? 
(ii) How tight is the timeline to repay the syndicated bank loans? Till now no disclosure by the management of Dasin. 

3. Why sell 2 properties? Isn't the syndicated loans due only S$500 Mil?
Extract of Loan Payable Summary from 31 Dec 2021 FS
The bad news here is that while S$499.5Mil of bank loan is already due, another S$105.7Mil is due in September 2022; S$132.9Mil is due on 15 July 2022 and another S$17.6Mil due on 28 September 2022. 

Hence a total of S$755.7Mil of loans are either already due or due within 6 months. Dasin needs to sell at least 2 properties urgently to get out of the loan default mess.

4. Estimated sales proceed from divestment of the 2 malls
Extraction from valuation report from Jones Lang Lasalle
The total valuation of Xiaolan Metro Mall and Shiqi Metro Mall are RMB4,836,700,000 (S$1,015Mil).
Since it was mentioned in the recent MOU announcement that the Purchaser will grant Dasin put option for shares in the Special Purpose Vehicle created to acquire the 2 properties, I presume an estimated S$760Mil will be in hard cash so as to repay the bank loan while the remaining S$255Mil will be in a mixture of shares and cash to Dasin.
Parting thoughts
Overall, Dasin may end up in a distressed sales of not just 2 malls but perhaps all of its shopping malls at firesales price if the above divestment does not go through. Personally, I thought that the new Trust Manager, Sino-Ocean, seems to have done a lot to prevent a firesales of Dasin's investment properties by tapping on its networking to arrange a suitable deal. At the same time, I am apprehensive of the reason why Sino-Ocean did not propose a direct capital injection into Dasin with its partner but instead come up with such a financing structure. I smelled a rat somewhere which Sino-Ocean and the syndicated bankers are not revealing on why the syndicated bank loans failed to be renewed for the longer term of 2 to 3 years. 

Last but not least, Dasin is trading at just 0.225 times of its net asset value of S$1.40 as at 31 December 2021. So if the above deal pulls through at a close enough price to the Jones Lang Lasalle valuation, it is tantamount to the unlocking of a huge potential upside for existing unit-holders.  Of course, whether Dasin is investible or on its final death bed at this juncture is an enigma by itself....so beware.

P.S: Please see my previous posting on Dasin Retail Trust

Saturday, 12 March 2022

Dasin Retail Trust 15.4% Distribution Yield Per Annum- Typical Value Trap Or A Hidden Gem?

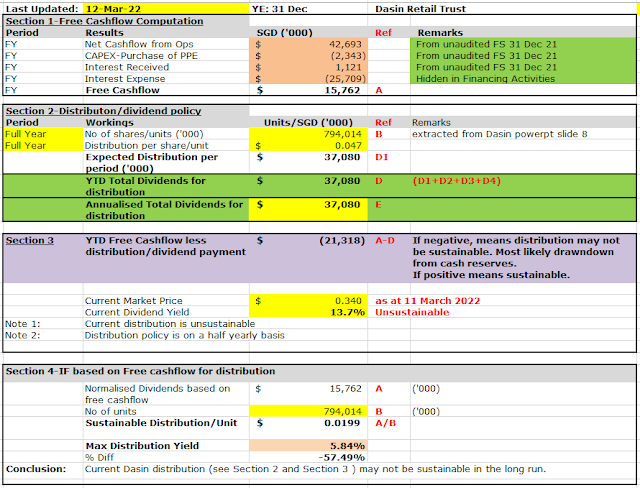
Dasin Retail Trust ("Dasin") S$500Mil syndicated bank loan is still in limbo despite the past 2 loan extensions- latest extension being given is from 20 December 2021 till 19 March 2022. Once again, there is not much news or disclosure from the Senior Management of Dasin with regard to the status of the syndicated bank loan albeit the deadline of 19th March 2022 fast approaching. The unit price of Dasin has been severely punished by the market and has dropped from its 52 weeks high of S$0.765 per unit to S$0.310 at its lowest point due to the high possibility of bank loan default. As at 11 March 2022 (Friday), the unit price of Dasin recovered slightly back to S$0.340 per unit. The late payment of distribution for the 1st half of FY2021 as well as the repeated failures to renew the syndicated bank loan for the long term have dented investors' confidence and it looks like Dasin will keep trading well below its NAV of S$1.40 per unit for a very long time. In addition, the free cashflow analysis which I came up with seems to be pointing to an unsustainable current distribution rate from Dasin in the long run (I will elaborate this point later on).
1. Dasin Retail Trust 15.4% Distribution Yield Per Annum- Typical Value Trap Or A Hidden Gem?
First and foremost, the super high +15.4% distribution yield is due to distribution waiver by the substantial unit-holders. The income waiver over the past few years end on FY2021. Going forward, there will no longer be waived since the business is deemed to have stabilized. Without the income waiver by the sponsor, the distribution yield will only be at +13.7%. This may still appear high but there are 4 main worrying points to take note in case one thinks that Dasin at its current price is a hidden gem and cash cow.

1(a) Worrisome plunge in fair valuation of its shopping malls for 2 consecutive years even as COVID brought under control in China in 2021
In FY2021, fair value of its shopping malls dropped by <S$62.8Mil>. In FY2020, this fair valuation was <S$105Mil>. Total fair valuation decline over the past 2 years combined is <S$167.8Mil>. Since the valuation methodology is based on discounted future cashflow by Jones Lang LaSalle, this means that expected future cashflow has plunged. This maybe attributable to higher interest rate and also lower occupancy rate [please see 1(b) below].

1(b) Occupancy rate of its mall has dropped further
As at 31 Dec 2021, occupancy rate of the shopping malls have dropped to 93.9% relative to 96.5% as at 31 Dec 2020. This is strange considering that by FY2021, the COVID situation I thought is already better managed in the whole of China. 

1(c) Is the free cashflow available for distribution sustainable on a longer term?
The free cashflow does not seemed sufficient at all and being financed from current pool of existing cash balances. This will dwindle over time. The current distribution by Dasin is unsustainable in the longer run. If based on free cashflow, the sustainable distribution yield will only be +5.84%.  This is where I find it extremely worrying. I will probably do a more in-depth analysis on this enigmatic issue if Dasin survived the upcoming bank loan default.  
 
1(d) Can't help but wonder whether the numbers reflected in its financials and presentation are reliable
In addition, I sometimes wonder whether the numbers presented in Dasin's financial are reliable. 

-Are there also as many tenants still operating in the different malls with good footfall from shoppers?

-Are there also huge unrecorded liabilities that is waiting to pounce on unsuspecting unit-holders? 

-Does the bankers have in possession certain unfavorable information that is why the refusal by some of them to to refinance the syndicated bank loan even after 2 extensions?

However, to be fair, not all signs are gloom and doom with regard to Dasin as I will further elaborate in Paragraph 2 and Paragraph 3 below.

2. Reputable new trust manager and major shareholder-Sino Ocean


Sino-Ocean Capital is listed on the HKSE. So at least there is a glimmer of hope that the bankers will be willing to re-finance the loan given the better reputation and financial position of Sino-Ocean.

3. NAV of Dasin is at S$1.40 per unit- Market Price/NAV ratio of an incredulous 0.243
If one look out the latest China Retail Focused REIT/BizTrust Comparison by Vince on REIT-TIREMENT, we can do a rough comparative benchmark to similar retail REITs as follow: 
-BHG Retail- 0.59 
-Sasseur REIT- 0.88

If we are conservative, we can just use the lower BHG Retail REIT's ratio of 0.59 as reference benchmark. So, if Dasin managed to survive the bank loan renewal crisis, then its fair market value may have a potential upside of recovering to S$0.826 per unit. This is a whopping 147% potential upside in capital appreciation. Of course, this is just a speculation as I am somehow unable to figure out the root cause of the low free cashflow for Dasin as alluded to paragraph 1(c) as aforesaid mentioned.  This is also subject to the reliability of the financial figures being provided by Dasin with no hidden surprises.
Parting thoughts
The free cashflow evaluation seems to be pointing to a future cut in distribution to unit-holders as it is not sustainable in the longer run since it is being drawn down from available cash and leverage.  Anyway, this intriguing issue is not important right now. The upcoming deadline for renewal of the bank loan is perhaps the crux issue for Dasin now as it will determine whether there will be an immediate rights issue to repay the syndicated bank loan or a forced liquidation of investment properties. Saying that, there is also the possibility that the end of Dasin is once again postponed by the bankers should they choose to kick the can down the road for another 3 months extension on 19th March 2022.

Tuesday, 14 December 2021

Dasin Retail Trust On The Verge Of Bankruptcy Declaration? Will It Be Suspended From Trading on SGX?

This is a follow up on my previous post on Dasin Retail Trust ("Dasin") on 18th September 2021 with regard to its debt crisis of S$500Mil since the syndicated bankers were willing to only grant a short term extension of 5 months from July 2021. The day of reckoning for Dasin approaches this week with the bank loan officially being in default on 19th December 2021 if it is unable to secure support from the syndicated bankers. Up till today, there is still no news being released by Dasin's new Trust Manager, Sino Ocean on SGX. Dasin's senior management has been silent since the last announcement made to the public on 7th November 2021 on the change in new Trust Manager. Unit prices for Dasin also dropped sharply and is now near its all time low at S$0.375 per unit in stark contrast to S$0.785 per unit during its peak this year. The silence for so many weeks in the face of imminent loan default is deafening. Are we witnessing the calm before the storm?
1. Taking calculated risk
I am still holding on to my small stake in Dasin Retail Trust as my investment thesis is that since the new Trust Manager, Sino Ocean which took over is a listed company on the Hong Kong Stock Exchange and well-known, the bankers will be willing to grant a long term extension of the due bank loan instead of rolling into a default and proceeding with creditor winding up process. Forced sales of investment properties is not going to be good for all stakeholders. Its current dividend yield is close to +14.2% based on its last unit price of S$0.375 per unit as at 14 December 2021.
2. Liquidation stress testing of realisable assets to repay bank loans and Unitholders
I have written in to the Customer Relation Officer on their website but till now have not received any reply on the status of its bank loan negotiation. In the worst case scenario, we have to assume that the fair value of the investment properties in Dasin's books have been severely inflated. If distressed selling price is at a discount of <-47.3%> of its last disclosed numbers, then this will mean a total loss for current investors-pls see below screenshot for illustrative simulation model. Not impossible given the case of Eagle Hospitality Trust. Also, given that China property debt crisis from Evergrande- if not managed well- may lead to a case of economic meltdown in the entire China market across all sectors. However, I am keeping my fingers crossed that the discounted selling price is at most only 40% off the last valuation in order to recoup back some of the investment costs. 
Parting thoughts
I have no idea how my tiny foray into Dasin will turn out. My investment thesis may turn out to be totally wrong. If so, this will be the 2nd SGX listed Trust (within this 2 years) that collapsed with investors losing all of their investments. The only good thing about Dasin is that the results will be known quickly by next Monday (20th Dec 2021) latest. It will either increase by maybe 50% from good news on renewal of bank loan or be suspended indefinitely due to default of bank loan when the announcement is released.


Please also see my previous posts on Dasin:

Wednesday, 13 October 2021

Dasin Retail Trust Bounced Back To Life with 22% Valuation Improvement- Will It Survive the Debt Crisis With Sino-Ocean Capital Taking Over As New Trust Manager?

Dasin Retail Trust ("Dasin") has been on a roller coaster ride since my last posting on 18 September 2021. When Dasin made a shocking announcement on 28th September 2021 that its half year distribution payment has been postponed to 4th October 2021 instead of 28 September 2021 itself, this sparked off a fierce selling frenzy by many unit-holders to get rid of their units fearing the worst had happened. The SGX regulator  immediately raised a query to ask Dasin to give more detailed clarifications with regard  to the actual reason for the delay. Price at one point dropped to  S$0.380 per unit from S$0.415 per unit.  Dasin's NAV as at half year reporting was S$1.46 per unit. It was totally disastrous as Dasin entered into one of its darkest chapters since its listing on SGX.  

1. Dasin Management team should have planned better for the half yearly distribution and not caused market panic
The false alarm started with Dasin management team being extremely secretive on the reason for the delay other than it was due to "technical issues" delay on 28 September 2021. The mind blogging term "technical issues" thus lead to widespread panic as investors feared that either Dasin has run out of cash or some bank facilities covenants has been breached which led to immediate default with bankers closing in. 

It was only after SGX regulator started querying before Dasin management came out to explain (on 1st October 2021) that the delay was due to COVID-19 measures that slowed down the verification work from a bank in Macau that was transferring funds back to Singapore.

2. Dasin bounced back with Sino-Ocean Group (listed on HKE) taking over as the new Trust Manager
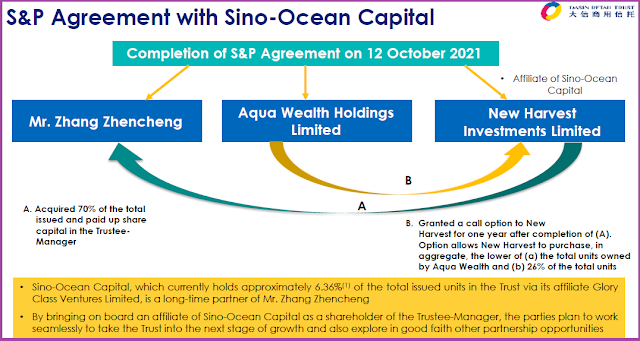
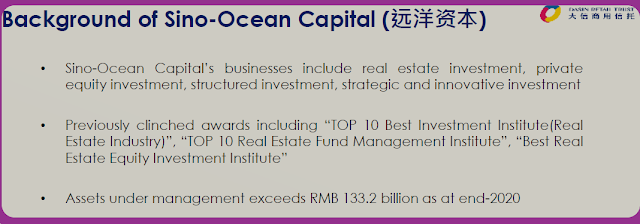
On 12th October 2021, Dasin announced the successful completion of sales of shares of the Trust's manager from the Founder, Mr Zhang Zhencheng to Sino-Ocean. Sino-Ocean. Capital’s businesses include real estate investment, private equity investment, structured investment, strategic and innovative investment. It has clinched numerous awards such as “Top 10 Best Investment Institute (Real Estate Industry)”, “Top 10 Real Estate Fund Management Institute”, “Best Real Estate Equity Investment Institute”. As at the end of 2020, its assets under management exceeds RMB 133.2 billion.

With the financial backing and reputation of Sino-Ocean Group, the risk of non-renewal of offshore bank loans by the syndicated banks to Dasin has been significantly (albeit probability of non-renewal is still existent) reduced. As a result, Dasin roared back to life on 13th October 2021 with prices hitting intra-day high of S$0.580 per unit at one time. Its price has since gone down to S$0.470 per unit. Nevertheless, this is still an impressive 22% surge in market valuation within 3 weeks.  

3. Parting thoughts
The next step for the new Trust Manager, Sino-Ocean, would be to engage the bankers with regard to the final negotiation for the S$500Mil bank loans that are due for repayment by 19th December 2021 which lead to a current ratio of less than 1 for Dasin. If the long term banking facilities renewal hurdle is cleared, I reckon that there is a potential upside of 40%-50% increase in unit price back to S$0.70 per unit, which was the price before the sudden collapse from 16th June 2021 onwards due to the impending repayment date of the offshore borrowings expiring on 18th July 2021 at that juncture (it was eventually extended but only till 19th December 2021). Saying that, many investors are still scarred by the bad track record of previous S-chips listed on SGX. 

Note:

Sunday, 3 October 2021

Investment Portfolios Updates- (1 Oct'21)- Added More Alibaba Group Holdings And Keppel DC REIT


1. Portfolio 1- CDP held stocks
I have sold off all my stocks in Global Investment Limited (except for the odd lot of 1 share) as it has gained over 30% in terms of capital return. While the share-buy back helps to increase its share price, I do not like it as its management seems to have run out of idea on what assets to invest in and the dividend yield has gone down drastically. I have used the proceeds to switch to Keppel DC REIT and also Mapletree North Asia Commercial Trust. 


2. Portfolio 2- Margin purchased securities
I have invested into Keppel Pacific Oak REIT in view of the better performance among US office REITs and future growth potential. Manulife US REIT was extremely disappointing in terms of its recent results as well as too highly leveraged.

In addition, I have also taken up positions in SPH in early August 2021 as there is visibility of increase in its price by 10% upon completion of the Keppel Corp's offer. Given that Keppel Corp and SPH are all owned by government linked companies, I figured that probability of the deal going through is rather high with less risk. Even if the deal does not go through, I can live with holding on to SPH as its student accommodation business can be further monetized via a REIT offer. Woodleigh shopping mall and Seletar Mall can also be sold into SPH REIT.


3. Portfolio 3 (with Tiger Brokers)- Venture into higher risk as well as capital growth stocks here
While my main approach in investment is towards an income generation strategy as evident from my portfolio 1 and portfolio 2 above, I have also set aside some funds for capital growth. Hopefully, the returns from 1 of these will be multiple fold as a booster to my overall portfolio. 

For Alibaba, I have been adding on to it over the past few months- please see: "The Alibaba Fiasco- Catching A Falling Knife?"

As for Dasin Retail Trust, this is a high risk high reward counter. Basically, its current liability exceeded current assets as the bankers are not willing to renew the Trust's bank borrowings but only extend it till 19 December 2021. Its market price thus has dropped significantly to only S$0.410 per unit at the time of my purchase. My initial investment in this was S$5K as I was optimistic that its new Trust Manager being appointed is a China state owned enterprise listed on HKE and there is a huge potential to see a 100% return in investments by end of the year- please see: "Will Dasin Retail Trust Go Bankrupt And Be Put On Fire Sales? Annualised Distribution Yield at 12.9%."

However, I was flabbergasted when the Managing Director of Dasin Retail announced last week that cash distribution for the half year ended 30 June 2021 has been delayed by a week due to "technical" issue. I am not sure what is "technical" issue. But it may mean that there is no cash available or there is breach of banking covenants which seems to be pointing to the fact that negotiation on renewal of the bank loans are not finalized yet. Hidden skeletons may also soon start surfacing. Hence I decided to just sell off most of it and only retain a S$1K position in Dasin Retail Trust.

Saturday, 18 September 2021

Will Dasin Retail Trust Go Bankrupt And Be Put On Fire Sales? Annualised Distribution Yield at 12.9%.


Dasin Retail Trust (“Dasin”) is in financial crisis. SGX has raised queries regarding its weak balance sheet with cash on hand and other short term assets being unable to fulfill its current liabilities. Apparently, a huge sum of loan financed by local and offshore bankers had expired and granted only a temporary extension till 19 December 2021. The local China banker lender had withdrawn itself for new facilities and this left the offshore bankers shell-shocked and being placed on guard that there may be fundamental weaknesses or other “surprises” waiting to spring on them in Dasin. Not surprisingly, Dasin’s unit prices has thus plummeted from S$0.785 per unit as of beginning of the year to the current S$0.415 per unit (as at 17 September 2021) which is a whopping 47% plunge in valuation.
 
1.Quick financial recap for Dasin
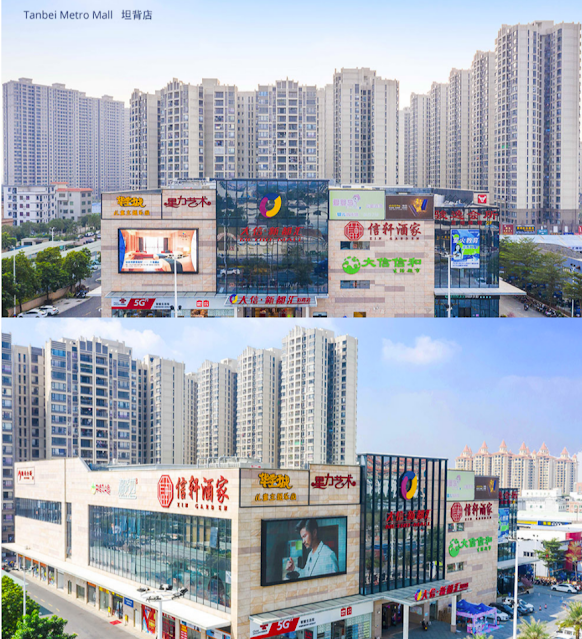
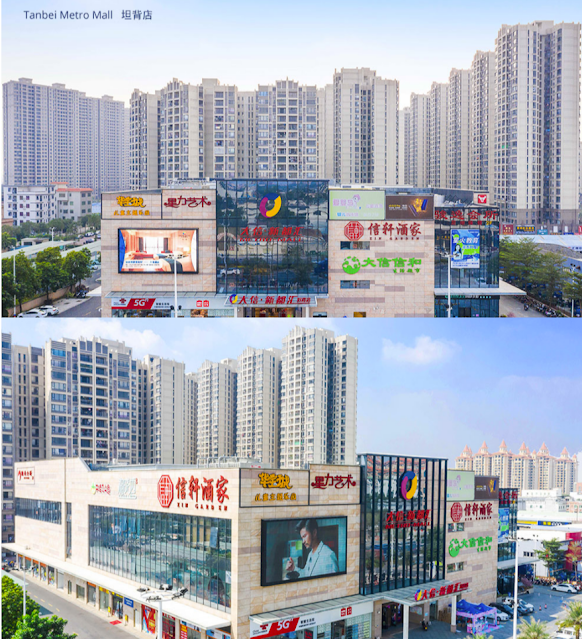
As at 30 June 2021, Dasin’s net asset value is S$1.46 per unit. DPU for the 1st half of 2021 is 2.98 cents which gives an astounding annualized yield of +14.36% at the latest closing price of S$0.415 per unit as at 17 September 2021. Take note that there is also income support for Dasin which will no longer be available from FY2022. The normalized 1st half DPU (if we were to add back the distribution waiver to some units due to this) will be 2.67 cents which still gives a dazzling annualized yield of +12.9%. The higher distribution relative to FY2020 is mainly due to recovery from covid-19 impact as well as contribution from Shunde Metro Mall and Tanbei Metro mall which were acquired in July 2020.
 
Before one rejoice, we need to delve into deeper discussion on the key going concern risk from the impact of Dasin’s maturing huge debt of S$500Mil that may result in a forced liquidation.
 
Dasin has S$422.7Mil of offshore debts and S$79.2Mil of onshore local debt that matured in July 2021-approximately S$500Mil.The bankers have extended these to 19th December 2021. Classification of these are thus “short term” which resulted in a current ratio (current assets/current liabilities) of less than 1. Since Dasin clearly does not have enough funds to repay all the loans, this will mean a default of loans and an immediate lawsuits from the lawyers representing the bankers which can lead to a forced liquidation and an unfavorable fire-sales of all shopping malls at a very low price. Unit-holders will also face suspension of trading of their units and get their liquidity stuck for 1-3 years (at least 1 year) under such adverse turn of event.
 
2. Bankers spooked by Dasin. A repeat of the Eagle Hospitality Trust Saga?
Most of the investors of Dasin are extremely worried about the reason why the consortium of banks renewed the term loans for Dasin until only 19 December 2021 and did not extend them for 3 to 5 years as per the normal practices with other REITs. There were also market talks that a local China bank pull out of the syndicated loan earlier this year which spooked the hell out of the remaining bankers.
 
It was also reported that the bankers were so filled with anxiety that they resorted to sending out personnel and officials to visit Dasin’s malls. Good news here is that the shopping malls under its portfolio seems to be packed and doing extremely well.
 
Hence it does not seemed to be another case of Eagle Hospitality Trust saga where the sponsor did a lot of magic tricks to move the money around out of cleverly engineered financial valuation of assets which resulted in many current lawsuits being filed. Dasin has also been paying out distributions for the past few years unlike Eagle Hospitality Trust which failed to even deliver its first distribution.
 
3. Other points to note- Sponsor Mr Zhang Zhencheng seems to have financial difficulties.
One interesting point to note is that Mr Zhang Zhencheng and his investment vehicle Aqua Wealth have pledged 38 Mil Dasin’s units as collateral for margin facilities with CGS-CIMB for purpose of securities trading. He has been forced by the broker to liquidate some of his Dasin’s holdings due to margin call. The fact that Mr Zhang Zhencheng did not top up additional cash to his margin account suggests that he has encountered some financial distress personally.
 
While it is true that Dasin and Mr Zhang’s Aqua Wealth are different legal entities, the implication here, in terms of corporate control environment, is that it leads to higher risk or pressure of possible financial misstatement in order to ensure the financials of Dasin looks well. Investors have this lingering doubt that things are not as rosy as reported for the 1st half results and there are cans of worms that may surface soon. Many failed business such as Eagle Hospitality Trust reported unrecorded liabilities only when special accountants were appointed to scrub through their books.
 
In addition, once we add in exorbitant default interest rates on bank loans as well as professional service firms such as liquidator and lawyers, a huge chunk of the net assets will be burnt up quickly to feed these hungry sharks which may result in little or none being left for the unit-holders.
 
4. Light at the end of the tunnel?
The good news here is that Mr Zhang Zhencheng is a smart man. He has pulled in a HKE listed investment holding company Sino-Ocean Capital (specializes in property investment and development activities in China) to take up a 70% stake in Dasin’s Manager. It has also granted an option to Sino-Ocean Capital to buy up to 26% of the units owned by Aqua Wealth. Sino-Ocean already held on to 6.36% of Dasin which will make it one of the biggest holder of up to 32.36% if the option is exercised.
 
Sino-Ocean is a state owned enterprise in China which thus placed it in an entirely different league with other S-chips listed on SGX (which were beset by corporate governance and accounting problems).
 
It was reported that the entry of Sino-Ocean was instrumental in the bankers agreeing to extend the original loan facilities maturing 18 July 2021 to 19 December 2021. The new Trust Manager is working with the bankers to secure a longer term syndicated loan. Anyway, 3 months left for negotiation with bankers and we will know the fate of Dasin soon.
 
Parting Thoughts
So the key question at the end of the day is whether Dasin will survive this loan crisis. Phillip Securities, in July 2021, has issued a price target of S$0.780 per unit for Dasin which is an 88% potential upside. Personally, I think that this is a very risky time to enter into Dasin unless there are more information being released. Sino-Ocean Capital also has not exercised their option to acquire more units in Dasin hence they may still be doing their own due diligence and are uncertain. Henceforth, there may still be bigger surprises that are unrevealed yet.