Showing posts with label SingMedical. Show all posts

Saturday, 29 October 2022

Investment Portfolios Updates- S$522k (28 Oct'22)- Investing During Bear Market Turmoil.

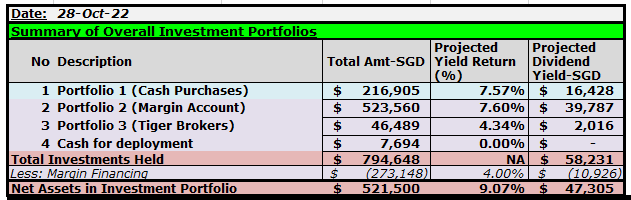
My net investments market value plummeted dramatically from S$613K to S$522K (a loss of S$91k) within a short span of 2 months. Gross investment before margin financing went down S$918K to S$795K (a decline of S$123K). I still vividly recalled being made "famous" by some retail investors during the March 2020 COVID crisis (whereby I faced an even worst decline) when my blog was published by those individuals on Hardware Zone forum as a good lesson to all on the danger of using margin financing despite them not knowing anything about my overall financial position and contingency plan in place. In addition, as an income focused investor, I am more concerned with the resiliency of dividend/distributions in my portfolios during bear market rather than the market value. I only have this to say about the use of margin financing: if one does not have any strategy, self-discipline or contingency plans in terms of managing leverage in different scenarios, then it is best to stay far away from it.

Anyway, the various global stock markets performance have been going up and down as if they are playing a game of Yoyo. The last 2 weeks has been extraordinary volatile with ferocious & rapid sell off in SREITs to 52 weeks record low- I was simply stunned by the brutalities of investors who kept dumping their units as if there is no tomorrow. For this round of market turmoil, I am glad that my SREIT holdings such as Capitaland Integrated Commercial Trust and Keppel DC REIT continued to report good results despite the great fear instilled by the relentless increase in borrowing rates. In spite of the volatility, I have continued investing during this dark period and also make some minor changes to my portfolio which I should elaborate further below.

1. Portfolio 1- Stocks held in SGX Central Depository 
(Note: This portfolio is designed to provide immediate dividends for use (if required) as it is under my own CDP account and the dividends credited goes directly to my bank account.)
2 main updates here:
(i) I have purchased Digicore REIT. Personally, I find that its price has fallen till a very ridiculous level with distribution yield of over 6.5%.

(ii) Selling off 10,000 units of Keppel Data Centre ("KDC") REIT and switching to another badly beaten down REIT- pls refer to "Keppel DC REIT Unit Price Dropping Like Flies- 43% Decline From S$3 Per Unit To S$1.70 Per Unit". A number of folks have requested me to reveal the identity of the "badly beaten" down REIT: I have actually used the proceeds from KDC to buy into United Hampshire US REIT which has declined sharply but with a higher distribution yield.

2. Portfolio 2- Margin purchased securities
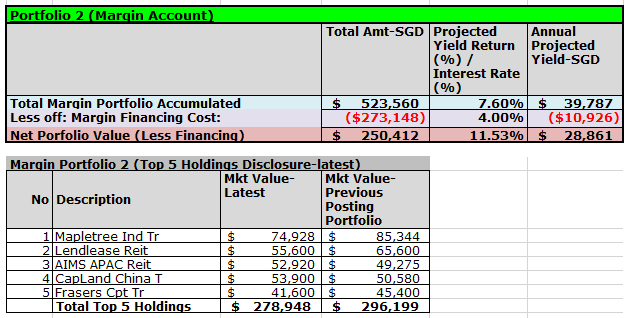
(Note: My margin purchased securities has grown to a sufficient scale to sustain itself and also to repay annual financing charges as well as to gradually pay down the margin loan through dividends generated.) 
I have taken profits by selling down the bulk of my banking stocks OCBC and UOB (while retaining some small stakes in my margin portfolio) and reducing my margin borrowing by S$31K (from S$304K to S$273K). While it is true that rising interest rate does benefit banks but the problem here is that if a severe recession with numerous job losses (we already seen the radical 900,000 job retrenchment exercise being announced by Credit Suisse), default of banks loans as well as decrease in loans granted will mean worsening results for the bankers. I decided not to take the risk and to lock into the profits. 

In addition, I have made further investments into Capitaland China Trust and also AIMS APAC REIT.

3. Portfolio 3 (with Tiger Brokers)- Venture into higher risk as well as capital growth stocks here
Main updates here:
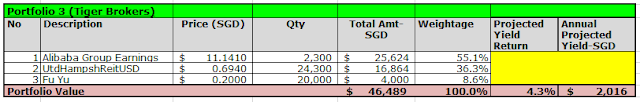
(i) I continued to accumulate some Alibaba stocks (where many expert investors are cursing & swearing at it and showing off that they are right in predicting its dismal performance) as its price keep dropping. I will be holding on to it for now despite the higher political & economic risks associated with a pivot towards a socialism economic model. Please see "Alibaba Plunged 12% And Hit All Time Low of HKD61 Per Share- Time To Sell Off And Exit Alibaba Mayhem?"

(ii) sold off SingMedical whereby its directors made a privatization offer. I am lamenting at the low ball offer being made and have sold off my stakes directly. Please see "Singapore Medical Group-Directors Made Low Ball General Offer For Privatisation At Only 37 Cents Per Share".

(iii) I have also ventured into investments into S&P 500 initially here but have since sold it off to raise the level of cash to wait for good opportunities during this market turmoil.

Summary
Given the recent good results announced by the various SREITs (except for US office REITs), I expect dividends to continue rolling in over the next few months.

Wednesday, 14 September 2022

Singapore Medical Group-Directors Made Low Ball General Offer For Privatisation At Only 37 Cents Per Share.

The privatisation offer for Singapore Medical Group ("SMG") finally materialised after a few years of waiting. Unfortunately, the offer price of S$0.37 per share was only a 19% premium to the average price of S$0.310 over the past 3 years.  This is a very sad exit outcome for all retail investors as SMG has dropped from S$0.490 mid-2019 and languished ever since then. If based on median PE of different medical groups, the PE is around 20 times plus which worked out to a fair value of S$0.516 per share instead of the pathetic S$0.37 per share being proposed by the Offeror. This is no doubt a very low ball offer by the Offeror, TLW Success Pte Ltd, to buyout existing shareholders. For longer term focused investors, there is an alternative offer of 1 for 1 share in the new investment holding Company being offered in lieu of cash consideration. However, liquidity and lack of regulator direct supervision will be key issues for those who opted for taking up the new share option in TLW in lieu of cash, as upon SMG being privatised, it will be delisted from the SGX.
 
1. Offeror background- Shareholders are current Chairman/Directors of SMG
Shareholders of the private consortium

c
Directors of  the current "Company"- SMG
As seen from above, the new company is formed by the existing SMG Non-Executive Chairman, CEO and another Executive Directors. Those bigger shareholders like the Korean Medical Group CHA and Silver Mines Global Limited have undertaken to take up the new shares consideration instead of cash electives with a long term focused view.

2. Rationale for the offer per Dr Beng Teck Liang (Executive Director and CEO) and his offeror TLW.
(a) Uncertainty in the short to medium term
SMG faces significant headwinds compromising a challenging marco-economic and operating environment driven by operational cost increases and shortage of skilled healthcare labour.

(b) Subdued historical share price performance
The Offeror is of the view that the historical price performance of the Shares has generally been relatively subdued despite the Company having consistently demonstrated a strong track record of profitability and operational execution. This includes delivering record levels of revenue and profitability for FY2021 and continued organic expansion through the opening of new clinics and by growing the number of specialist doctors within the Company. Accordingly, this has constrained the Company’s ability to utilise its Shares effectively for acquisitions or fund raising.

(c) Opportunity to realise investment in SMG at an attractive price and substantial premium
The Cash Price represents a premium of approximately 18.1%, 18.8%, 16.0% and 18.0% over the volume weighted average price ("VWAP") per Share for the one (1)-month, three (3)-month, six (6)-month and 12-month periods respectively, up to and including 8 September 2022, being the last full Market Day.

Parting thoughts
I am rather disappointed by the rationale given by TLW and the director of SMG. In 2019, Dr Beng himself and some other directors sold off a number of their shares to the Korean medical group CHA at a record price of S$0.605 per share that is not available to other shareholders. But currently, when they buy out existing shareholders, they only offer S$0.37 per share despite the growth of the revenue from S$22.9Mil in FY2013 to S$100.8Mil for FY2021 which is an impressive growth rate of 20% per annum over the past 8 years.

Personally, as a retail investor, I would not want to take up the risk of the alternative option of new shares in the Offeror's company as their management to me has a terrible track record of putting their own interest first rather than all shareholders no matter how well they sugar-coat this whole exercise. This will also subject oneself to their mercy where there are many possibilities on how they can play investors out after delisting. Will be closing off my current holdings (please see my recent investment portfolio updates) in SMG and bidding farewell to them. 

I am also sure that this is not the last time we see or hear from the soon to be ex-SMG management. They will probably re-package the business and then launch an IPO in another 3-5 years time at 2 to 3 times their cost of this buy-out. Good luck also to Dr Beng, Dr Wong and Mr Tony who seems to be ok with their reputation going down the drain with the low ball offer.     

Sunday, 11 September 2022

Singapore Medical Group Requested For Trading Halt- Privatization Or Rights Issue For Expansion?

On 9th September 2022 (Friday after trading hours), Singapore Medical Group ("SMG") requested for an immediate trading halt while awaiting an important news release to be announced by its CEO, Dr Beng Teck Liang. I have been wondering how come the share price of SMG suddenly came back to life and surged to S$0.325 per share as at 9th September 2022 when it has been trading with little volume at the range of S$0.305 per share to S$0.310 per share. In fact, it has been stuck at S$0.310 since August 2019. As usual, I reckon that information about the upcoming major change seems to have been leaked out to friends and relatives similar to what I have seen from other listed entities just right before their major business decision announcement. 

1. Upcoming major M&A or Privatisation?
I am intrigued by what will be announced by Dr Beng Teck Liang in the coming week. It could be a new M&A opportunity that perhaps need rights issue for funding or even better, it could be a privatisation exercise given that the PE ratio of SMG is way below the industry average relative to other medical groups. 

In order to unlock the undervalued business of SingMedical Group (“SMG”) which I mentioned briefly in my post on 8 July 2019, I have suggested the possible option of privatization using the example of Thomson Medical Centre which had previously been acquired by the local business tycoon Peter Lim before doing a “future relisting” on the SGX 6 years later.

2. Poor history of corporate action to close up the gap of market price to intrinsic valuation for all shareholders.
Previously, there was an exercise whereby the senior management was in talk with 3rd parties with regard to the purchase of SMG shares. However, it fell through. 

There was also a sales of shares by existing directors to the Korean Medical Group CHA at S$0.605 per share in February 2019. However, this was not extended to other shareholders. 

In short, the current management team has a poor track record of unlocking the intrinsic valuation of SMG for all shareholders. Let's hope the coming announcement will lead to a substantial increase in its share price. 

Parting thoughts
Given the poor track record of corporate action execution, I am not too optimistic for now until I gain greater clarity of what SMG intends to do. In the meantime, its dividend yield of approximately 4% to shareholders is comforting while waiting for the tree to bear fruits. 

Updates on 14 September 2022 (pls click on link below for the details of privatisation being announced:

Thursday, 27 February 2020

Undervalued Gem Singapore Medical Group Adopted Dividend Policy- Maiden Dividend Declared

Singapore Medical Group ("SMG") just announced another set of excellent financial results for FY2019. Its revenue rises 11.3% relative to prior year to a record S$94.7Mil driven by growth across all business segments. SMG also reported a 5.7% increase in net profits to a record S$13.6Mil.  However, its share price performance for the whole year was disastrous as it plummeted from an all time high of S$0.490 per share to a low of S$0.0.275 per share range despite the excellent performance of a few years for no apparent good reason. During the year, directors also sold some of their stakes to the strategic Korean Medical Group CHA for S$0.605 per share. The current share price of S$0.310 thus reflect a massive discount to its fair value using the S$0.605 as benchmark and a 100% potential upside.   

The only reason that I can think of for the poor share price performance may be attributed to investor fatigue and the perceived unfairness by retail investors in terms of the recent capital raising exercise using convertible loans at S$0.423 per new shares and sales of shares to CHA at S$0.605 per share which is only opened to the senior management staff. 

1. Announcement of Dividend Policy-Finally!
During my last posting on SMG, I have mentioned that I have written in to the senior management team of SMG for them to seriously consider the immediate roll out of a dividend policy to support the undervalued share price. I think that many shareholders may also have voiced out the same thoughts. I am glad that the Board of Directors listened to shareholders and decided to roll out a formal dividend policy to reward shareholders.
Dividend Policy announced on 24 Feb 2020
For long term investors, the dividend policy which endeavors to pay out at least 20% of yearly earnings, should be rewarding enough to stop the relentless dumping of SMG shares by existing shareholders.  At a price of S$0.310, the current payout of S$0.008 per share translates to a 2.58% dividend yield while the remaining earnings is ploughed back into the SMG business for further regional investment and expansion. 

2. How "undervalued" is SMG?
Compared to other medical groups out there, SMG is severely undervalued. The P/E ratio of most medical group such as Raffles Medical Group, Q&M Dental Group & ISEC Healthcare is around 25 times. SMG P/E ratio stands at a mere 12.6 times only- please refer to below chart on "Peer Comparisons". 

3. Summary
With the introduction of a formal dividend policy, shareholders can patiently wait on the sideline to receive dividends while waiting for price to recover to its fair valuation of S$0.605 that is, a potential 50% to 100% upside of capital gain over the next few years.

Note: I have started to re-accumulate shares in SMG due to the introduction of the dividend payout policy.  Currently holding on to 60,000 shares with plans to increase it further. But the headache now is opportunities for other higher dividend yield stocks are opening up in view of the COVID-19 worldwide outbreak. 

Please also see my previous postings on SMG:

Sunday, 19 January 2020

Is Singapore Medical Group Still An Undervalued Gem? Or Trapped in Downward Spiral Bottomless Pit?

Singapore Medical Group (“SMG”) share price has been stuck in a whirlpool of S$0.300 range for many months ever since August 2019. It all started with an offer by the Korean Medical Group, CHA, to buy out substantial number of shares from Dr Beng and his management team at S$0.605 per share. To add insult to injury, while the share price was at a high of S$0.485 per share, SMG decided to place out to CHA a S$10Mil convertible loan with conversion rights at S$0.435. Many shareholders were outraged at the unfairness of no general offer being made to them as well as the value destruction of the convertible loan pegged to a low exercise price. As a result, the massive sell off of SMG stocks from S$0.485 to S$0.300 per share commenced. What a bloodbath it had been since then for the many investors who came in at the all-time high of S$0.485 and booking in unrealised/realised losses of 38.1%.

Is SMG still an undervalued gem?
The excellent quarterly financial results announcement speaks volume of the potential of SMG. I believe that the current dramatic plunge in share price is only a temporary situation given the good financial results. However, the main problem is how long will the prevailing low market share price situation persist? The next issue is while deploying capital into SMG and playing the waiting game, there has been a drought of dividends being paid out of SMG to loyal shareholders for their sacrifice. 

There is an opportunity cost in waiting for the sun to shine once again.  If share buybacks do not work, then SMG should try paying out dividends to try to revitalise the sluggish share price performance. On 2 July 2018, there has been an announcement by SMG with regard to the implementation of a formal dividend policy but since then, there has been no updates at all.

Emailed to senior management of SMG with regard to share price in doldrums as well as dividend policy.
Since August 2019, I have been dropping emails via the general “Contact Us” email but there was no reply at all from SMG with regard to my recommendations. Earlier this year, I decided to follow up again with a last ditch effort to get past the red tapes by informing the staff behind the “Contact Us” email that I may inform the Corporate Secretary of SMG to table an additional resolution into the upcoming AGM agenda for all shareholders to discuss about dividends declaration which may make the situation awkward for the directors (albeit not my intention) if the customer service staff continue to play the ignoring tactic and not escalate my email to their senior management team. 

I was pleasantly surprised when 2 days later, Ms Wong Sian Jing (CFO of SMG) actually replied to my email. Ms Wong re-affirmed that implementing a formal dividend policy is always part of the management plan. However, SMG is cautious on the right timing to formalise such policy given that the Group is still at net current liabilities position as at 30 September 2019. The main reason for the net current liabilities are primarily due to deferred considerations arising from the business acquisitions and the CHA convertible loan that is due in less than 12months. Her management team will continue to execute its growth strategies and will update shareholders on any material development including decision on dividend payout (if any) via SGX announcement. 

Target Price of S$0.605 and parting thoughts:
Over the past few months, I have decided to sell off part of my SMG shares and realised losses as I re-deployed my capital into income generating stocks in order to increase my recurring cash-flow. However, I am still holding on to 40,000 units of SMG shares as I am still bullish on the eventual realisation of its intrinsic value into its market pricing. The fair value target should be S$0.605 based on CHA Medical Group recently paid consideration for SMG shares as well as the low PE ratio relative to SMG industry peers. This represented a 100% potential upside based on the undervalued price of S$0.300 per share. As aforesaid mentioned, main challenge is no one is exactly sure how many months (or years) one have to wait for the share price to breakout of its current whirlpool. 

Please also see my previous articles relating to Singapore Medical Group:


Monday, 8 July 2019

Will SingMedical Group Opt For Privatisation By Following The Footstep Of Thomson Medical Centre And Health Management International?


In order to unlock the undervalued business of SingMedical Group (“SMG”) which I mentioned briefly in my post on 9 June 2019, I have suggested the possible option of privatization using the example of Thomson Medical Centre which had previously been acquired by the local business tycoon Peter Lim before doing a “future relisting” on the SGX 6 years later. Thomson Medical is close to my heart as I used to be involved in part of its accounting and financial work many years back. Also interestingly, another medical group, Health Management International recently announced a privatisation initiative after years of languishing share price performance amidst good financial results.   

1. Acquisition of Thomson Medical Centre by local business tycoon Peter Lim and eventual privatization and “relisting” it on SGX.
To recap, Thomson Medical Centre (“TMC”) was founded by Dr Lim Cheng Wei Chen in 1979. It was listed on SGX in 2005 and was the fourth healthcare services provided on SGX after (i)Parkway Holdings, (ii) Raffles Medical Group and (iii) Health Management International. In 2010, Peter Lim made an offer to buyout TMC based on a valuation of approximately S$513 Mil which was a whopping 60% premium over the last traded price. TMC was subsequently delisted from SGX in January 2011.

Of course, there were some critics then who thought that Peter Lim might have overpaid for TMC by paying such a colossal premium over the business. It turns out that the astute businessman Peter Lim had the last laugh as he sold the TMC business (along with TMC Life Science) in 2017 to Rowley shareholders for S$1.9 billion which is multiple times (3.8 times) the amount he paid initially. Peter Lim’s bet on the aging population and booming healthcare services via the building up of healthcare portfolio was simply right on the spot and brilliant. Also, by injecting the assets into his public investment vehicle Rowley, Peter Lim looks set to participate further in its future growth. Rowley later changed its name to Thomson Medical Group.    

2. Health Management International partnership with private equity firm EQT and proposed privatization offer of S$0.73 per share
On 5th July’19, Health Management International (“HMI”) had also announced a proposed privatization by offering S$0.73 per share via a partnership with private equity firm EQT. This represented a premium of 24.8% over the volume-weighted average price of HMI over the last 1 mth. Existing shareholders of HMI can choose to sell their shares directly or swap them for new shares in the offeror.

One of the main reasons cited by HMI management for privatization is due to the challenges in raising capital is because it is highly dependant on the market conditions. This draws a similar parallel dilemma to what SMG is facing too, that is, rights issue at an ever declining prices due to the undervalued business by the market.

After privatization, HMI will build up the current business with new funds of up to S$150Mil from EQT for investments and acquisitions. The target is to work towards another IPO within 18 months after the initial 4 years of repackaging at a higher valuation. This is clearly another business plan that resembles the billionaire Peter Lim’s strategic investment into TMC in 2010 and the partial exit in 2017.

3. Is there the possibility that SingMedical Group will also be privatized and shareholders offered a premium to last traded price?
This is only a remote possibility at this juncture as CHA Medical Group had just provided an equity convertible loan of S$10Mil to SMG to fund new acquisitions.

However, if share prices still languish as it had been over the past 2 years despite the turnaround of its business and better financial performance by Dr Beng, future capital raising exercises will be detrimental to the shareholders of SMG as only a very low amount can be raised which forms a vicious downward cycle on the share price. The substantial shareholders will not be happy with such perpetual share price spiraling downwards after every rights issue.

SMG can choose to either work with the Korean CHA Medical Group or partnered with a private equity firm (just like HMI) to buy out the current shareholders and then do an IPO or business injection into a shell company already on SGX to realise its intrinsic value.

 4. Will retail shareholders of SingMedical Group benefit from such privatization attempt?
The answer is actually a resounding “NO” based on its past few years of excellent financial performance and also rapid business expansion. The offeror can make a low ball offer of just a token 25% more (say S$0.50 per share) than the last traded price of S$0.395 per share. However, many retail shareholders may have no choice but to take up the low offer as once the firm delisted, they may be stuck with the shares on hand with no buyers since it is no longer trading on the stock exchange.

The last valuation of SMG business was just recently concluded by CHA Medical Group valued the business at a price of S$0.605 per share. Hence “privatization offer” may not necessarily be a good thing for retail shareholders but it does enable investors to cash out at some premium if the undervaluation in market price situation has been prevailing for many years.

5. Summary
Summarising, I hope that Dr Beng and his management team will consider the implementation of a Group dividend policy as a mean to try to narrow the current significant gap between market pricing and the intrinsic value (current earning multiple benchmarking to the other medical players on SGX is way too low). If this still does not work, a strategic review of options such as privatization should be considered to unlock the intrinsic value of the SMG business.  

Please also see my previous postings on SingMedical Group:

Sunday, 9 June 2019

Sing Medical Group Déjà Vu- Undervalued Stock Price Increased 20% But Price Collapsed Again Recently


Since my last posting on the “The Enigmatic Case of Sing MedicalGroup- More Money Earned Lead to Lower Share Price” on 8 January 2019, the price of Sing Medical Group has shot up by 20% from S$0.400 to S$0.485 within 2 months. However, its share price has since plunged by 22% to a low of S$0.380 on 7 June 2019. If one had the ability to see the future using a magical crystal ball, then one would have sold off in Feb’19 at S$0.485 and then buy again when it hit S$0.380 recently and locked into the profit. If it can recover to S$0.480 level, one would have made a staggering 40% profits. Of course, I am saying this with the benefit of hindsight. I know of a retail investor who subscribed to value investing sinking in up to S$100K over the past few months into Sing Medical Group (“SMG”) and the recent plunge in stock price would have been disastrous. So, what exactly happened here for the price to have plunged so dramatically again and most importantly, the key question is whether the share price of SMG is severely undervalued again?

The very peculiar nature of Sing Medical Group share price
The strange thing is that whenever the financial results showed improvement or if it issued rights to raise funds for M&A opportunities, the share price will go the other way. The recent sharp drop in share prices maybe also due to existing shareholders punishing the management team for selling off part of their shares at SGD 0.605 to CHA, the Korean Medical Group and existing investor.

1. Excellent Q1 2019 financial results but share price tanked
The recently announced results of Sing Medical Group is excellent. Revenue increased to SGD21.6Mil  relative to SGD19.2Mil (+12.3%) on a year to year basis due mainly to growth in its Diagnostic & Aesthetics segment while Net Profit After Tax dropped <3%> in view of lower tax exemptions and lesser carried forward tax benefits. Since we cannot control statutory taxation, a better gauge would be to look at the Net Profit Before Tax which increased by 0.9% (the increased revenue is being offset by increase in marketing expenses). Despite the wonderful Q1 2019 results, the share price of Sing Medical Group tanked.

Many shareholders have been extremely disappointed with the lack of dividends being declared. Last year, the management did raise the possibility of a formal dividend policy in the new financial year but have since remained silent on this issue. Despite the high profits made, SMG has been aggressively reinvesting the proceeds into opening new clinics. A new pediatric clinic in Punggol has just been opened recently this year. A new Breast clinic and its specialist has also just come on board SMG. There are other plans to increase the number of specialists by another 7 to 8 which means revenue topline is going to continue to expand rapidly but profitability may be hit in the short term while ramping up patient loading.

2. Punishment by investors in retribution against the management for selling their shares at S$0.605 to CHA Medical Group without a general offer to other shareholders and proposed S$10Mil convertible loan to shares at a low conversion price of only S$0.423 per share.
Many existing shareholders in investment forum have been upset by the existing management selling off part of their shareholdings in SMG. CHA Medical Group has valued the shares at S$0.605. This exercise was just recently concluded. Compare S$0.605 independent valuation against the current price of S$0.380. This represented a 59% discount of the independent share valuation should the price hits S$0.605 in future.

Even for the S$10Mil convertible loan by shareholder CHA, the price of S$0.423 against the current market price of S$0.380 represented close to 10% discount for new investors entering at the current market price. This means that your investment automatically gain a 10% discount premium of S$1Mil out of S$10Mil cash injection by CHA medical group- free hard cash put in by the other shareholder to increase your margin of safety.  

3.Jinxed Fund Raising Exercises
Whenever there are rights issues or offer of convertible loans to shares, this always spell bad news for existing retail shareholders albeit improving revenue and future profits. This is because the share price will most likely plunge after this exercise. This has a lot to do with the lack of tangible returns to shareholders as alluded to point 1 above. There is thus currently an unhealthy downward spiraling cycle in its share price whenever SMG raised funds for expansion as the market seems overly risk-averse to the business of SMG. This is clearly a stark contrast to the industry PE average based on S$0.380 per share being traded.

Parting Thoughts
SMG management needs to seriously look into immediate actions to revive the share price. This is paramount as SMG will always need to give an increasingly huge discount of its intrinsic value to fund its aggressive growth initiatives which resulted in a perpetual downward cycle. I maintain my view that the share price will grow 20% by end of this year and with a potential for 50% growth in share price over the next 2-3 years if the management continued with SMG expansion. The increase in share price by 20% and then a decline of more than 20% represents good buying opportunity. I have accumulated extra SMG shares as I think that the management has been delivering and executing well on its expansion plan. The strategic partnership with CHA Korean Medical Group will also strengthen SMG.

Last but not least, at the current low share price of S$0.380, there is a probability that some existing corporate shareholders or perhaps Dr Beng himself may buy out the other shareholders and delist the undervalued SMG. After building up the medical group over the next few years, the controlling shareholders can easily go for IPO again at a better valuation to realise their investments. This is also the strategy employed by our local billionaire and business tycoon Peter Lim on Thomson Medical Group.

Pls also see my previous postings:
(i) Hidden Gem with Explosive Growth- Potential Further Upside of 25% to 50% (Part 1);

(ii) Hidden Gem with Explosive Growth- Singapore Medical Group S$10Mil Shareholder's Loan for M&A (Part 2)

Sunday, 24 February 2019

Hidden Gem with Explosive Growth- Singapore Medical Group S$10Mil Shareholder's Loan for M&A (Part 2)

The emergence of a key shareholder offering to buy out part of the shares of the current management to increase its control and the offer of  S$10 million dollars convertible loans to finance additional Merger and Acquisition opportunities has lead to some retail investors crying foul. These group of retail investors thought that the terms and conditions were unfair and detrimental to them. The market seems to have reacted slightly negatively upon the announcement of this news on 20 February 2019 hence the sharp price rally of Singapore Medical Group ("SMG") from the excellent FY 2018 results declined from a high of S$0.495 to only S$0.465 as at 23 Feb 2019.

CHA Healthcare Singapore Pte Ltd has proposed the acquisition of shares from some of the existing major shareholders and the provision of a convertible S$10 Mil Loan. CHA Singapore is an investment arm of Korean healthcare group, CHA Health Systems.  CHA Group is a large healthcare group that was established in 1960. It has 10 general and specialty hospitals and 4 medical check-up centers in South Korea. It also has 2 healthcare facilities in United States.

Proposed share purchase of 83 million vendor shares for S$50Mil or S$0.605 per share.
The S$0.605 per share is an offer made to selected existing shareholders so that CHA will hold additional stakes in SMG. This is a significant premium of 30% over the closing share price of S$0.465 recently and is actually a fair valuation of SMG which has been severely undervalued by the market relative to other medical groups PE of 25 times relative to SMG's 16 times. Upon completion of the share purchase agreement, CHA will become SMG's controlling shareholder.

With regard to the assertion by other retail investors that the CEO,Dr Beng and Chairman, Tony Tan are planning to exit SMG and selling out the other retail shareholders, this is not true. Both Dr Beng and Tony Tan are still holding on to significant shareholdings in SMG even after the completion of the share purchase agreement with CHA Healthcare Group.
Dr Beng and Mr Tony Tan are still substantial shareholders of SMG after partial sales of their stakes.  
I think that some of the existing group of retail shareholders have been over-reacting to this deal mainly because the S$0.605 is an offer made to only some shareholders and thus viewed as extremely unfair. However, legally speaking, there is nothing wrong with this deal as the Takeover code has not been triggered (less than 30% of total shares). No general offer is necessary. My thoughts are that this is actually a win win deal for all stakeholders. 

(i) Firstly, it does strengthen the strategic alliance with CHA Healthcare Group. CHA is no stranger to SMG. Since 2017 strategic private placement of S$15Mil (@S$0.50 per share), both SMG and CHA had worked closely together on regional expansion which is one of the key reasons behind the rapid and successful year on year significant growth in business. 

(ii) Secondly, the sales of the shares serve as a good reward for Dr Beng and his other management team shareholders who have contributed much to the success of SMG over the past few years. From executing the restructuring from a loss-making medical group to the current huge profits recorded, they should reap the rewards. This will only serve to motivate them to continue growing the group. S$0.605 may even have been undervalued based on the PE of 25 times for other industry peers. A point to note here is that CHA Healthcare Group will definitely ensure that Dr Beng and other key personnel continue to hold substantial stakes in SMG in order to align their interests together. Key relationships with many medical specialists are actually held by Dr Beng and his team. The success of any Medical Group also lies in the talents of the doctors that are practicing their specialties hence the retention of Dr Beng and his management team are crucial to the success of SMG.

(iii) Thirdly, there is a silver lining for all retail investors in that a real general offer may be made to all shareholders in future in the event that CHA decided to acquire the SMG business if it grew at its current pace. This is actually a strategic fit for its existing worldwide businesses.

Proposed S$10Mil Convertible Loans To Shares At Conversion Price of S$0.423
Personally, I think the conversion price of S$0.423 negotiated by Dr Beng and team with CHA is too low. But if we were to look at the broader perspective, this is a better option than calling for costly rights issue. The rationalization that I have here are from 2 angles: (1) incentivizing CHA group to take on a bigger involvement in SMG and (2) with the direct funding from CHA group on top of leftover from last year's rights issue for M&A activities, this will free up profits for the formal introduction of a dividend policy in FY2019 to benefit all shareholders. Share prices have languished also due to the lack of patience of many shareholders on getting physical and tangible returns on their investments.    

Parting Thoughts on the whole CHA deal
Risks of the business are in execution of M&A and also assuming no major fall out between Dr Beng and CHA group now that the latter has a bigger controlling stake. Liquidity of the trading of SMG are mostly very poor which means that one can get stuck holding on to too much stakes in SMG. The macro-economic conditions may also worsen and lead to losses- pls see my posting here on "Healthcare Stocks are Resilent in Earnings. Fact or Myth?"

Overall, I think that the CHA offered deals are good for SMG. Most of CHA investments in SMG are actually at S$0.50 per share (S$15Mil in 2017) and  S$0.605 per share (upcoming S$50Mil in 2019). Put it this way, if I paid S$0.605 per share and the SGX traded share price is only S$0.465 per share, I will ensure I whipped the managment hard to continue growing the business as well as introduce other measures to boost shareholders value.

Also, the additional funds on offer by CHA will help to speed up the expansion and branding of SMG into one of the leading medical groups in Pan Asia.

Note: Please see here for previous Part 1 of "Hidden Gem with Explosive Growth- Potential Further Upside of 25% to 50%".

Saturday, 23 February 2019

Hidden Gem with Explosive Growth- Potential Further Upside of 25% to 50% (Part 1)


Since my last posting on the enigmatic case of Singapore Medical Group which was grossly undervalued by the market on 8th January 2019, the stock price has soared by an amazing 20% around the announcement period of its Q4 2018 and full-year earnings. This was a big surprise to me as I was expecting the stock to only rally 20% by end of this year due to its lack of visibility among many investors. The small positions that I have initiated thus are giving me immediate unrealized returns that will take 2-3 years to achieve if I have instead invested in pure dividend yielding stocks. The headache now is deciding whether it is time to take profit or to wait for further price appreciation. I will break down my review of Singapore Medical Group ("SMG") into 2 separate postings as I wanted to cover on 2 major events which are potential future stock price catalyst that has suddenly emerged over the past week: 

(i) The explosive growth for SMG for 3 consecutive years and future outlook and the sudden surge in share price by 20% relative to the beginning of this financial year.

(ii) The emergence of a key institutional shareholder offering to buy out part of the shares of the current management to increase its control and the offer of  S$10 million dollars convertible loans to finance additional Merger and Acquisition opportunities. The market seems to have reacted slightly negatively on this news hence the sharp price rally decline from 20% to only 15% as at 23 Feb 2019 relative to the beginning of this financial year.

Explosive Growth for Singapore Medical Group For Past 3 Years

On 19 Feb 2019, SMG finally announced the long-awaited report card for its performance in Q4 2018 and full year 2018. It was an excellent set of strong results with growth of 25.1% for revenue and a 52.1% increase in net profits. Basically, SMG demonstrated that it has once again achieved double-digit growth in topline and bottom line and for 3 consecutive years. This was an extremely impressive feat and is the testament to the depth of the current senior management team in executing M&A for growth. 

Future Outlook For SMG

SMG senior management team will continue to do vertical acquisitions in women's health, pediatrics and diagnostic imaging. The directors are currently exploring opportunities to open a new breast care clinic and have identified two new specialist doctors to join them. 

In addition, SMG is currently exploring opening a new imaging centre in the western part of Singapore and they will continue to explore accretive value-driven acquisition opportunities to accelerate growth and profit trajectory.

The overseas growth strategies in Vietnam, Indonesia, and Australia continued to be in place as SMG build and position itself as a pan-Asian healthcare player. SMG will also look for avenues to grow in markets such as Malaysia, Vietnam, and Cambodia.

Valuation and Price Projection of SMG
Based on its current stock price of S$0.465 per share as at 23 February 2019 (Friday) just a few days after the results announcement, I am projecting another highly probable growth of 25% for the top line and bottom line of SMG. Hence 1 year from now, the share price should appreciate in line with the business growth (proven track record of Management team) to at least S$0.58  per share.

Another method of getting the current valuation as at this juncture is to look for similar transactions. There is actually an upcoming offer by a shareholder to increase stakes in SMG via the acquisition of part of the shareholdings of the exisiting management team. This shareholder has valued the current share price at S$0.605 per share.  

Some retail investors have been skeptical over the whole deal and also accuse the management team of having the intention to exit the SMG business through the sales of their stakes. Some were also extremely upset at the offer of a S$10 million dollars of convertible loans by this particular shareholder. They are crying foul over the terms offered and also suggesting other retail investors exit SMG due to diminishing prospect. I will delve more into this in my next posting but as one can see from the totally different views, valuation is a very tricky and judgemental subject. My personal view as of now remains that SMG will have another explosive year ahead with up to 25% to 50% further stock price appreciation.

Note: Please see here for subsequent Part 2 of "Hidden Gem with Explosive Growth- Singapore Medical Group S$10Mil Shareholder's Loan for M&A".

Tuesday, 8 January 2019

The Enigmatic Case of Sing Medical Group- More Money Earned Lead to Lower Share Price.

Singapore Medical Group (“SMG”) share prices has fallen by a whopping 44.1% from its peak of S$0.715 on 17 July 2017 to only S$0.400 as at 8 January 2019. This is despite Q3 2018 YTD revenue growth of 27.8% and net profit after tax growth of 66.7% relative to FY2017 Q3 YTD. What is even more astonishing is that the share price has languished albeit the explosive growth of revenue and net profit attributable to shareholders over the past 3 years.

Taking into account the previous rights issue at S$0.48 on 4 July 2018, investors who bought in at the current pricing of S$0.40 would have gained an immediate discount of 16.7% to the fair value of cash on hand where the bulk of the recent S$6.6Mil cash raised is still held in bank and only S$2.2Mil were utilized as at 31 Dec 2018.   

Business Activities of SMG
SMG is a multi-disciplinary specialist and primary healthcare service provider. SMG had grown significantly year on year. The 3 main medical activities of SMC are (i) Healthcare (Obstetrics & Gynecology; Women’s Fertility; Dental; Oncology; Health screening), (ii) diagnostic imaging (fast-growing segment) and (iii) Aesthetics. It has also recently ventured into pediatric services and SMG has also been aggressively growing its footprint beyond Singapore to Malaysia, Indonesia, Vietnam and Australia in the region.


Financial Performance of SMG
The last 3 years of growth for SMG from FY2016 to FY2018 has been rather explosive since the change in senior management- please see below section on the management team led by Dr Beng Teck Liang.


For FY2017, SMG net profit jumped +250% from S$2.4Mil in FY2016 to S$8.5Mil in FY2017 on revenue of S$68Mil.

For Q3 FY2018 YTD, it has achieved profits of S$ 9.984Mil relative to S$5.988Mil which is an impressive 66.7% growth. This is on the back of growth of +27.8% in revenue from S$49.2Mil in Q3 FY2017 YTD to S$62.88Mil in Q3 FY2018 YTD.

I am anticipating good results announcement for Q4 FY2018 once SMG published their final results.

Valuation Assessment-Comparison of Current Financial Benchmark to Competitors
For the purpose of the benchmarking exercise, let’s use Raffles Medical Group and Q&M as a proxy. SMG is trading at around 14 times FY18 PE relative to other Healthcare Group of approximately 25 times FY18 PE. This is a steep discount in terms of valuation based on PE in the medical services industry.

Strong And Experienced Management Team Led by CEO Dr Beng Teck Liang and Chairman Tony Tan
When Dr Beng took up a 20% stake in SMG in June 2013, the group had been recording huge losses for close to 2 years. Dr Beng was instrumental in restructuring the business through cost-cutting measures, getting good doctors to stay on and re-negotiated contracts.

Technology had featured prominently in the transformation of SMC. Dr Beng who worked before as Managing Director for Hewlett-Packard (HP) Thailand and Chief Medical Officer at Novahealth, was the one who introduced electronic medical records digitalization, a web based, cloud based Radiology Information System (RIS) as well as Picture Archiving and Communication System (PACS) into SMC.

SMG announced the appointment of Tony Tan Choon Keat as non-executive chairman on 2 December 2013. Tony has vast experience in the healthcare industry. He was the founding managing director of Parkway Holdings. During his tenure at Parkway Holdings, he made acquisitions and development by Parkway Holdings both in Singapore and overseas to build up its healthcare franchise to one of the major healthcare players in Asia region.


Future Growth
SMG planned to upscale and expand their aesthetics services to Vietnam and Indonesia markets.

Things To Watch Out For When Investing In SMG
Most investors seem not to have noticed SMG. The daily volume being traded are still razor thin. One might not be able to easily liquidate for conversion into cash if required.

In addition, SMG currently does not pay out any dividends hence this may be another reason why many investors shun it. However, it has been announced on 3 July 2018 that the Company is seriously looking into a formal dividend policy in FY2019 along with a share buy-back mandate. The risk here is that this is just verbal talk and it does not materialize.

Also, the current M&A strategy also comes with high execution risk. There will also be more rights issue given that the management seems to be very aggressive in pursuing inorganic growth.

Last but not least, it is a fallacy to think that medical earnings are resilient. The adverse impact of dwindling medical tourism has been negatively affecting all medical players such as Raffles Medical Group as well as SMG.

Parting Thoughts
I think that SMG is well positioned for another year of good growth in FY2019. Based on its PE against its peers, a conservative estimate will be that there is at least a 50% upside potential in its share price. I am projecting a 20% increase in its share price performance annually in FY2019 and FY2020 respectively due to the splendid leadership of their Board of Directors which has delivered 3 years of solid financial results. I am sure the pro-expansion mindset of SMG Senior Management team through organic and inorganic growth will steer SMG forward and turn it into a premium regional healthcare provider.