Showing posts with label SPH REIT. Show all posts

Wednesday, 12 February 2025

The End of Paragon REIT- Eaten Up By Hungry Lions!

The seemingly wonderful announcement of an offer by Cuscaden Peak to buy out the minority unit-holders of Paragon REIT at S$0.98 per unit lead to a sudden surge in its market perfromance as at 11 February 2025. While Paragon REIT soared 11.2% in a single trading day to become the best performing SREIT of the day, some unit-holders are crying poignantly as they have bought Paragon REIT at S$1.00 to S$1.10 per unit before the high interest rate environment became the norm post-COVID that leads to the downward spiral in its market unit price.

1. Hungry Lions Butchered Retail Investors
While this latest offer of S$0.98 per unit is way better than the S$0.9372 per unit offered back in 2022, it nevertheless is way undervaluing the crown jewel, Paragon shopping mall. Furthermore, it is actually a free-hold property but financial engineered into a 99 years leasehold when injected by the then SPH into SPH REIT (currently renamed Paragon REIT) and we all know that it is sitting in the prime area of Orchard Road.  

I will take it with a pinch of salt that Cuscaden is playing hero to take up the extremely risky option (as per their insinuation) of major asset enhancement initiative ("AEI") of S$300Mil to S$600Mil over 4 years hence willing to buyout the minority unit-holders due to the execution risk. The truth is that Cuscaden is a commercial organisation that seeks to maximise profits for its shareholders. Their accountants, along with their commercial team,  would have done a detailed financial projection of the future prospect to recoup back the upcoming CAPEX to achieve a favourable reward to risk outcome.  
In view of Paragon shopping mall's future outlook post AEI, I thus think that a more reasonable price would be at least 20% in premium to its NAV of S$0.915, that is, at least S$1.098 per unit.

2. Will I take up the offer or vote against the offer if vested?
Note that I do not hold any units in Paragon REIT directly but my family members held around 11,000 units since 2019. I think that most REITs investors are more interested in a decent & stable distribution yield of 5% to 6% per annum. The AEI initiative will lead to a drastic plunge in distribution for the next 3-4 years as Clementi Mall will be left doing the heavy lifting during this period. I will probably be lobbying for my family members to just accept the offer and then move on to invest in other opportunities. The only issue is that of the late payment timeline of May 2025 (even if the EGM went through). Of course, if the REITs price crash further during this period, then Paragon REIT holder will benefit from the locked in S$0.98 per unit and vice versa if market price suddenly surge if interest rate decline more rapidly than expected.
Parting Thoughts
Personally, I do not like this deal as I do not find it very attractive or compelling enough for unit-holders. It would be great if Cuscaden can revise its offer upward by another 10%. But then again, there is a lack of clear direction for the growth of Paragon REIT given that its major unit-holders seems to have bought it to strip out its remaining investment properties. So, I am leaning towards the just sell and move on to other investment opportunities albeit the non-attractive offer. 

P.S: Please see my previous other post on Paragon/SPH REIT on 2 May 2022

Monday, 2 May 2022

Take It With A Pinch Of Salt-The Reluctant Half-Baked Chain Offer for SPH REIT By New Major Shareholder Cuscaden Peak And 3 Points To Note.

I thought that the current offer price of S$0.9372 per unit for SPH REIT by Cuscaden is just a half hearted and half baked one- in fact it is forced under SGX rule to make this chain offer- so do not expect too much from it and don't waste too much time pondering over it. Cuscaden looks like it is heavily bruised from the tussle with Keppel Corp over the recent Singapore Press Holdings acquisition. While it won a great battle for taking control of Singapore Press Holdings, it had burned a big hole in its bank account and it is clear that at this particular juncture, Cuscaden is ok for it to remain listed as it is. 3 things to take note of, regarding this upcoming acquisition offer for SPH REIT:

1. The market price as at 29th April 2022 is S$0.975 per unit but chain offer price is at S$0.9372 per unit.
I had a good laugh at this. The cash offer is 3.88% lower than the last closed price. Ok, what this means is that unit-holders who are looking to sell their units are better off selling their SPH REIT units on the market rather than accepting the chain offer from Cuscaden. So why is Cuscaden making an illogical offer then? The answer is as aforesaid mentioned, because from the SPH acquisition exercise,  they now owned more than 30% of SPH REIT and SGX rule stipulated that they need to make a general offer for the rest of SPH REIT. 

Nevertheless, I would expect the unit price of SPH REIT to drop immediately to match the S$0.9372 per unit upon resumption of trading on 4th May 2022 ( Wednesday). If so, this chain offer would have destroyed much value for SPH REIT. 

2. No one knows exactly what Cuscaden intends to do with the assets acquired under SPH hence future of SPH REIT is also a big question mark.
The consortium of Cuscaden is made up of Hotel Magnate Ong Beng Seng's Hotel Properties (40%) and 2 Temasek-linked units, namely Capitaland (30%) and Mapletree (30%). Ong's lieutenant has not officially announced how the 3 parties intend to split the assets such as Student Accommodation, Seletar Mall, Woodleigh Mall etc among themselves. 

I frown upon the future of SPH REIT which remains muddy with no clear sense of direction.
3. It is a myth to believe that SPH REIT still has a solid backer with Temasek Holdings behind it. 
Now, this is the part that I personally believe is no longer the same case as Mapletree REITs, Capitaland REITS and Keppel REITs. The entry of Ong Beng Seng and his Hotel Properties holding the most individual party shares of 40% in Cuscaden means that Ong is now in the driver seat. In the event of a major crisis, there is a high probability that Temasek will not be diving in to the rescue immediately and with resources going out to other Singapore government linked REITs first.

On 29th and 30th November 2021, I have sold off all of my 44,000 units of SPH REITs at an average price of S$1 per unit mostly due to the fear of the omicron wave spreading as well as the uncertainty over SPH REIT's future. Subsequently, I have re-deployed some of the funds into Capitaland Integrated Commercial Trust instead while waiting for better visibility on Cuscaden's plan for SPH REIT.  

Parting Thoughts
In summary, I think that SPH REIT is now a totally different creature altogether relative to its former old self in-spite of holding on to the same investment properties. I hope that with the SPH acquisition completed and dust settling, the Cuscaden consortium will at least reveal more of its hidden cards on how it wants to run the newly acquired businesses.   

Sunday, 5 December 2021

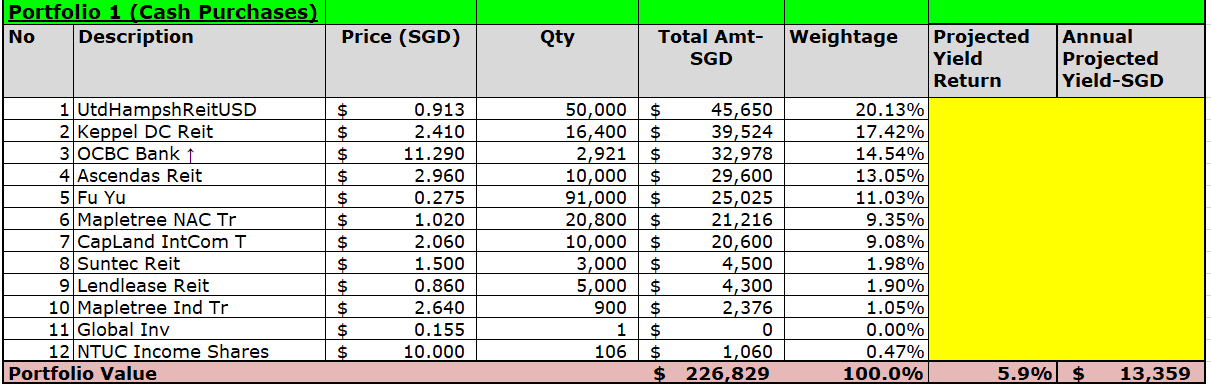
Investment Portfolios Updates- S$619k (3 Dec'21)- Equity Portfolios Facing Challenge of Omicron COVID Variant

The stock markets tanked recently due to the Omicron variant. I have sold off 42,000 units of my SPH REITs under my Portfolios to raise cash level at the start of the week. Subsequently, prices of local bank stocks and REITs dropped further and I took the opportunity to buy into more OCBC and Mapletree Industrial Trust while retaining some cash. My investment approach is still primarily an income focused strategy using cash account (Portfolio 1) supplemented by my Portfolio 2 opened with Maybank Kim Eng and leveraging on their Margin facilities-current projected dividend income is +S$44.6K per annum. For me, no point in timing the market by selling a major part of the portfolio as it is better to stay invested in order to continue to receive dividends and not missed out on opportunities such as new M&A announcements.  

1. Portfolio 1- Stocks held in SGX Central Depository
Not much action here except for selling off of SPH REITs to buy into 1,000 OCBC shares while retaining cash of around S$10K here from the sales.

2. Portfolio 2- Margin purchased securities
(i) The past 2 months has been rather interesting. I took a calculated risk with my margin account by buying into SPH shares after the announcement of Keppel Corp proposed acquisition at S$2.01, figuring that the market pricing then at around S$1.90-S$1.93 range, offers the most probable upsides with S$2K in profits expected with the successful completion of the offer. Next, Cuscaden Peak came into the picture to start the bidding war and I closed off my margin position in SPH shares recently to walk away with +S$6K profits (S$2.34 per share exit) as I do not think there will be another 3rd party offer.

(ii) I have reduced my holdings in retails REITs such as Lendlease REIT and SPH REIT. Anti-COVID measures will hit retail badly if the Omicron strain spreads widely.  

(iii) I have also increased my holdings in Mapletree Industrial Trust. I figured that it is prudent risk management to have the backing of strong sponsor like Temasek in the event that the COVID crisis worsen and there is a need for sponsor's cash injection should the property value plummet like in 2008. 

3. Portfolio 3 (with Tiger Brokers)- Venture into higher risk as well as capital growth stocks here
However, my venture into China Alibaba continues spiraling downward non-stop with concern over forced delisting by China regulator from NYSE and I am taking a huge hit of unrealised loss of almost <S$9k> from it. I will probably do a short write-up on Alibaba in my next post. 

Basically, I think the fundamentals of Alibaba are still intact despite the crackdowns by China regulatory and the lower growth rate. Just this week, I have invested another 100 shares of Alibaba at a price of HKD121.6 per share. But I think this is the last batch of Alibaba shares that I am buying to mitigate the risk of holding excessive Alibaba stocks.

Parting thoughts
I am looking forward to receiving further dividends in December 2021 for further re-investments. Let's see how the market reacts next week and whether there is further blood-bath due to the Omicron variant. However, personally, I do not think Omicron will be a repeat of the 2020 March crash as current vaccine surely still must have some effects (despite reduced efficacy) on the new COVID strain and chances of world-wide lockdown again is slim. I will continue buying in piecemeal to exploit the current market decline.     

Wednesday, 24 November 2021

Keppel Corp And Cuscaden Peak Got Whacked by SIAS Over SPH Offer.

The Securities Investor Association ("SIAS") has again stood up for retail investors by questioning the big boys Keppel Corp and Cuscaden Peak over their offer for Singapore Press Holdings ("SPH"). Talking about SIAS means also talking about Mr David Gerald, the original founder and president of SIAS. I recalled meeting the man himself over a decade ago while doing my Final Year University Project on Corporate Governance and interviewed him. He is a good man who is passionate in his drive to help retail investors. I recalled his request to my project team members then to join the SIAS as he needs "younger blood" as he is worried about the continuity of SIAS. I have utmost respect for this man. Back to the Singapore Press Holdings epic drama. SIAS has raised questions to both Keppel Corp and Cuscaden after feedbacks from retail investors:

1. Letter to Keppel Corp Senior Management
(i) Mr Gerald's letter to Keppel Corp questioned why Keppel is making it so urgent for SPH shareholders to cast their votes. Keppel had mentioned that the sooner the scheme is approved, the better it is for SPH so as to reduce any further uncertainty and instability for its various stakeholders and preserve value. 

SIAS shot back at Keppel by asking what does Keppel mean by "Uncertainty and instability" and raised the points by some retail investors that it would be fairer and easier for them to make a decision if both offers could be considered at the same time.

(ii) Keppel Corp also got shot a second time when SIAS raised another query on why is it beneficial for existing shareholders to receive Keppel units that trade at a discount to net asset value and why are SPH shareholders asked to trade their exposure to the current SPH assets for commercial properties owned by Keppel REIT. 

Personally, I think that Keppel Corp is only thinking for itself on how it can conserve cash else they would have given a cash option like what Cuscaden is offering right? But they are caught in a predicament as Keppel cannot openly admit this else it will be tantamount to saying "screw" the current SPH shareholders, we just want to minimize our cash outlay for this deal.

2. Letter to Cuscaden Peak
Cuscaden Peak (consortium made up of hotelier Ong Beng Seng, Capitaland and Mapletree) were not spared the hard questions. I think it is funny, as a matter of fact, the way SIAS did not mince their words.

(i) Firstly, SIAS raised a very good question on if Cuscaden's bid were to succeed, what is its long term plan for SPH REIT? Well, Cuscaden has been very quiet on this aspect.

(ii) Secondly, SIAS questioned the strange chain offer for SPH REIT made by Cuscaden of S$0.964 per unit given the last trading price of S$1.01 per unit as at 22 Nov 2021. The chain offer becomes lower than the recent market price? Does not make sense right? Do "surface job" must also do better right?

Parting thoughts
Market pricing hovers mostly at S$2.34 per share (after Ex-Dividend) despite the Cuscaden offer of S$2.36 in full hard cash. Probably market is pricing in uncertainties over whether all the regulatory approvals for the deal will go through. For myself, I have sold off part of my SPH holdings to take some profit while waiting for further drama to unravel and settle down. Looking forward to the replies by Keppel and Cuscaden to SIAS.

Monday, 15 November 2021

Cuscaden Peak's Superior Counter Offer For Singapore Press Holdings at S$2.40 Per Share- Goodbye Keppel Corp!

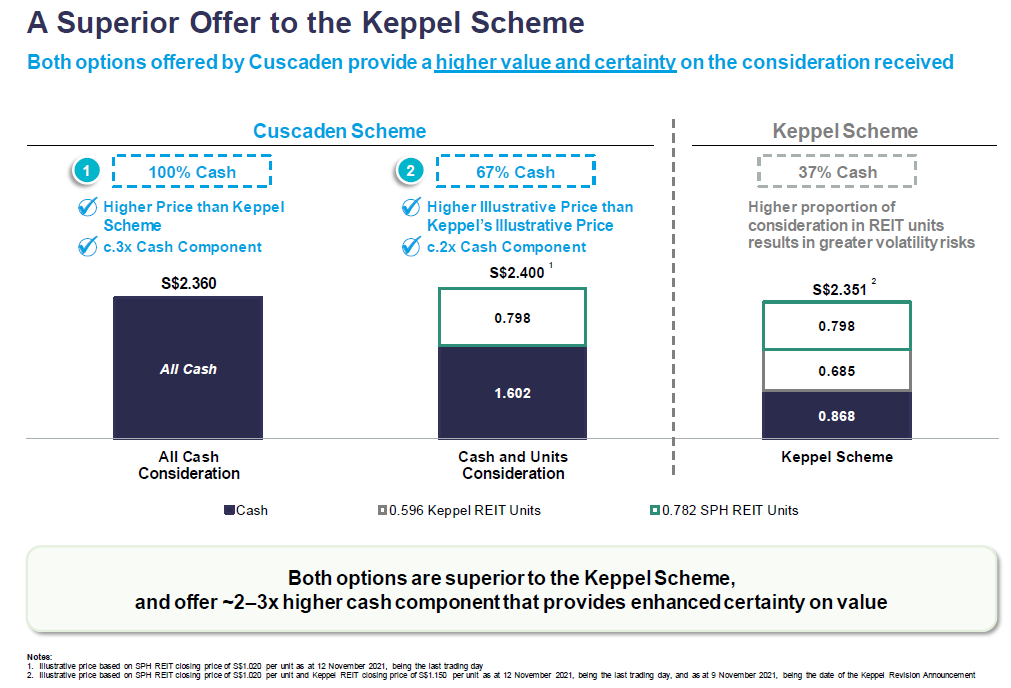
Good riddance to Keppel Corp's previous offers. Cuscaden Peak (the consortium making up of Ong Beng Seng, Capitaland and Mapletree) made a superior counter offer for Singapore Press Holdings ("SPH") today. During my last post, I mentioned that Cuscaden Peak may just trump Keppel's offer of S$2.351 per share (mixture of cash and Keppel & SPH REITs in specie) by 0.1 cent only and shareholders should not be too surprised- well, it turned out to be  way above expectation afterall as the current counter offer price on the table is S$2.360 per share (all cash) which is almost +1 cent more. I had enough of Keppel Corp's offers which were always a "hybrid" consideration of cash and REITs units. The market price of SPH, after every one of Keppel's offer, fell way below the fair value consideration.  

Moreover, Cuscaden Peak is extremely generous and provides another option for shareholders who preferred some SPH REITs to be distributed as part of the offered consideration so that they can participate through SPH REIT units in recovery upside of the retail real estate sector while receiving a significantly higher cash component than has been offered in the Keppel Scheme. 
Cuscaden's offer of 2 options to SPH Shareholders are vastly superior to Keppel Scheme.
1. Strategic mistake by Keppel Corp in their bid for SPH.
First and foremost, I think that Keppel Corp management should not have made it clear upfront that their offer of S$2.351 per share is the last and final offer. Keppel Corp may have underestimated Cuscaden Peak's deep pockets. By making a statement that they have already made a final offer, it motivated Cuscaden to just tip the bar over a little to easily trump their bid. Anyway, this is water under the bridge. 

Ultimately, Keppel Corp will walk away with S$35Mil breaking fees from SPH. After paying off legal and financial advisory fees, I expect Keppel Corp to retain a substantial part of the fees for future working capital or for special distribution to shareholders. Keppel Corp share price should shoot up once the trading halt is removed. My sense is that most of Keppel Corp retail shareholders frown upon the SPH deal in the first place. 

2. What does SPH senior management have to say about the current 2 offers on the table?
Subject to the IFA opinion and in the absence of a superior competing offer, the preliminary recommendation by the SPH Independent Directors is that SPH shareholders should vote down the Keppel Scheme and vote in FAVOUR of the Cuscaden Scheme.
Vote down Keppel Scheme first and vote for Cuscaden Scheme later
Also, SPH shareholders should take note that unlike the Keppel Scheme which is still subject to its shareholders' approval, the Cuscaden Scheme does not require the approval of Cuscaden's shareholders. All regulatory applications have been made the deal is expected to be fully completed in February 2022.

3. Other points for SPH shareholders to take note 
Shareholders who need cash and want to cash out immediately should take note that the ex-dividend date for the SPH S$0.03 per share dividend is on 22 November 2021 (Monday). 

So, if trading halt is removed and the price of SPH hits at least S$2.39 (S$2.36 offer + S$0.03 dividend) per share, then SPH shareholders can consider selling off.

On 22 November 2021, if the price of SPH is at least S$2.36 per share, then SPH shareholders can consider selling them off.

From 16th November 2021 to 21st November 2021, I expect the trading price to range between S$2.39 per share to S$2.43 per share. The worst case scenario would be that the price per share lingers way below S$2.36 per share but shareholders just have to hang on and wait till February 2022 for the deal completion to realize the full S$2.36 per share.
SPH's investment property-Seletar Mall at Sengkang Fernvale
Parting thoughts
I do not think that there will be a 3rd competing bidder at this stage since the price per share of SPH has seen such a huge jump over the past few weeks. With the transfer out of its Media business, SPH remaining property business has also come to a quick end. I think that shareholders should take this opportunity to cash out of SPH and let professional property management veterans take over the business. Alternatively, the only other option left is to vote down everything and let SPH continue its business under its current CEO....not exactly an ideal or rational case are my personal thoughts.

P.S: Fellow SPH shareholders, please share your views and thoughts on the Cuscaden Peak's new offer. Will you sell off immediately after trading halt is lifted to reduce further market risk or wait it out for a "counter-counter" offer albeit low probability? 

Please also see my previous posts on this:

Monday, 8 November 2021

Strange Chain Offer for SPH REIT By Cuscaden For S$0.964 Per Unit And Possible Leakage of Keppel Corp Counter Offer?

The Cuscaden consortium making up of Capitaland, Mapletree and Ong Beng Seng made a potential chain offer for SPH REIT on top of Singapore Press Holdings ("SPH") for S$0.964 per unit. However, current market price has surged to S$1.02 per unit. Moreover, SPH REIT was at S$1.10 and S$1.20 at one period before the COVID-19 madness. The chain offer is obviously just for show to comply with the takeover code.  Anyway, I hope that Keppel Corp will make a good counter offer for SPH. Since the news was released on 29th October 2021, the 10 days consideration period (if we assume it refers to working days), will mean an announcement soon by or before 12th Nov 2021. 

From the market price of SPH at S$2.170 per share suddenly today (8th Nov 2021), there maybe market speculation of internal news that Keppel Corp most likely will make a counter offer. Keeping my fingers crossed that there is indeed a better offer from Keppel Corp.

Note

Friday, 29 October 2021

Another Competing Offer for Singapore Press Holdings- S$2.10 PAID FULLY In CASH And Points To Note By Shareholders

Wow, I was shocked by the sudden trading halt and new announcement made by Singapore Press Holdings ("SPH") today.  Cuscaden (Consortium made up of Capitaland, Mapletree and Ong Beng Seng) announced that it has on 28 October 2021 submitted to the board of directors of SPH (the "Board") a proposal to acquire (the "Proposed Acquisition") all the issued and paid-up ordinary shares in the capital of SPH! What is even better, Cuscaden further announced that its offer of S$2.10 per share, will be paid for all in hard cash. Breaking news indeed! With the new all-cash offer on hand, I expect the share price of SPH to shoot up immediately from S$1.99 per share to at least S$2.10 per share. 
Extract of proposed offer S$2.10 all in hard cash

1.Dream come true!
Back in my previous 8th August 2021 posting, I have mentioned that shareholders need to get rid of the loss making Media segments first which will open up doors to other competing offers. Happy that the new competing offer materialize. Guess shareholders like myself do not need to take up Keppel Corp's offer of part cash along with Keppel Office REIT and SPH REIT as consideration. Getting units in odd lot as well as Keppel Office REIT are actually something that I do not want. 
Extract of previous posting on 8th August 2021

2.Safer deal for SPH shareholders- superiority to Keppel Corp's offer
The good thing about the Cuscaden deal is not just the all cash offer. The other added advantage is that the new scheme of offer will not be subject to any further shareholders' approval on the part of Cuscaden and its consortium members unlike the one from Keppel Corp.

3. Will Keppel Corp revised its offer price?
With the competing offer, there is a chance that Keppel Corp might revise its offer. Even if it did not win the acquisition, Keppel Corp will walk away with a break fees of S$34Mil from SPH. So it is a win-win situation for Keppel Corp.

4. Parting thoughts and points to take note by existing shareholders
Well, I am extremely excited by the new offer. Let's see whether there will be a bidding war between Keppel Corp and Cuscaden. Existing shareholders should not just sell off their shares immediately upon lifting of the trading halt. Please wait for the dividend ex-date of 22 November 2021 to pocket the S$0.03 dividends per share also. The S$2.10 offer will still be waiting there for picking up by shareholders. Of course, if the market price reaches S$2.13 before ex-dividend date, shareholders can consider selling off immediately. However, it maybe wise to hold first to see whether there are better counter-offer from Keppel Corp. Even better, there maybe another consortium or equity fund coming in with a 3rd bid. 

Note:

Sunday, 10 October 2021

How Much Is Singapore Press Holdings Worth Now? Disappointing Final Dividend Declaration.

Singapore Press Holdings ("SPH") final results was extremely good if we exclude the worsening performance of its media segment. Anyway, Media segment will be history to SPH soon, as shareholders has voted overwhelmingly in September 2021 to spin it off into the new proposed "company limited by guarantee" model. The final dividend declared of 3 cents per share is extremely stingy and disappointing. I have thought that they would have sweeten the Keppel Corp deal for shareholders by giving extra special dividends to keep retail shareholders happy so as to support the takeover. 

Updated Keppel Corp's Offered Consideration
Since the offer was announced on 2 August 2021, Keppel REIT's price has dropped a lot which does impact the deal being offered to SPH shareholders. Let us start to do a little bit mental acrobatics using the most recent market price of SPH, Keppel REIT and SPH REIT as at 8th October 2021 (Friday):
1. First point to note is that as the probability of the deal being crystalized (in particularly with SPH Media successfully voted to be transferred out thus meeting the first condition of the offer) has more visibility overtime, the premium based on current SPH market price has gone down significantly relative to 2 August 2021. Initially, there was a 11.65% premium which has declined to +4.26% based on current market valuation of SPH at S$1.980.


2. Nevertheless, we have to be mindful that due to upcoming dividends being declared in both SPH and SPH REIT, this will skew the valuation exercise since ex-dividend will mean a drop in equity value later on. Hence we need to normalize the numbers to account for the upcoming drop in business fair valuation due to payout of dividends. The premium if one were to buy today is still very much worth it as there is a potential +5.23% upside once the deal is being completed.

3. With the local and international COVID-19 situation improving day by day, Keppel REIT and SPH REIT market value may also go up even more. This will increase the premium of the Keppel offer to SPH shareholders.   

Parting Thoughts
Assuming that one is holding on to 10,000 shares and at an entry price of S$1.980, there will still be an upside of 5.23% (S$1K) once the deal is being approved by SPH and Keppel Corp shareholders despite the ex-dividend effect. This will mean an overall +S$1.3K upside including entitled dividends (of course, if the deal is indeed approved).

Sunday, 8 August 2021

The Keppel Corp and SPH Deal That You Need to Be Careful On- NOT Done Deal Yet.

The lightning speed of the announcement this week by Keppel Corp on the acquisition of Singapore Press Holdings Group ("SPH") caught many folks by surprise. Although I have mentioned on my 25 July 2021 post that corporate actions for SPH should eventually come as "it is an inevitable eventuality given the benefits of economies of scale", the sudden materialization of corporate action still have me reeling in surprise and my jaw dropping. Are we finally bidding a last farewell to SPH which was incorporated on 4th August 1984? Is the offer of S$2.2 billion enough to convince existing Keppel Corp and SPH shareholders to say "yes" to the deal?

1. S$2.2 billion offer by Keppel Corp is a very good deal?
Unfortunately, the answer to this is a big "No No" as evident in the current market pricing of SPH which nowhere cross the S$2.099 mark as well as the drop in the price of Keppel Corp, Keppel office REIT and SPH retail REIT. The offer sucks in a big way as it is not wholly cash being offered. Instead close to two-third of the offer is being offered via a distribution in specie with units of Keppel REIT and SPH REIT to buyout existing SPH shareholders. This is in some way similar to the current Capitaland restructuring deal.
Screenshot 1: Market Valuation of SPH Deal
Hence the extremely bad point of the deal is that the Keppel buyout is dependent on the market price of Keppel REIT and SPH REIT and if both REIT dropped in valuation, the SPH deal will be valued less. For instance, in an extreme scenario that if there is a new mutant Echo Variant COVID-19 that renders vaccine totally useless and forced another circuit breaker, Keppel REIT and in particularly, SPH REIT, might plummet in market value. 

As per screenshot 1, the current market valuation on offer has dropped to S$2.041 per share from the original announced package of S$2.099 per share as at 6th August 2021. Also it is interesting to note that SPH market price is trading at S$1.90 per share as at 6th August 2021 and 7.44% away from the new valuation of S$2.041 per share. 

2. Why is there a material deviation of 7.44% between the market valuation of S$2.041 and the last traded price of S$1.90 per share?
The reason for this is simple as the Keppel offer still has much grave uncertainties. There are 3 main hurdles to clear before the deal is concluded:
Screenshot 2: Timeline of Completion of Keppel Offer
(a) More than 50% approval of SPH shareholders need to be obtained for restructuring of Media business segment into the newly formed CLG (Company Limited by Guarantee) in September 2021 EGM. The T&C of the Keppel offer lies in that the transfer of Media assets out of SPH is first approved by the shareholders of SPH;

(b) More than 75% special resolution approval by Keppel Corp shareholders to buyout SPH shareholders at S$2.099 per share in November 2021 EGM and

(c) More than 75% special resolution approval by SPH shareholders of the S$2.099 per share offered by Keppel Corp in November 2021 AGM.  

3. How likely is the deal to go through?
Well, there are some very angry retail investors out there clamoring for blood and will oppose the deal. This is especially for those long term retail investors holding from S$4 per share era and another group which feels that this is grave undervaluation for SPH net assets- pls see below screenshots from forums.
Personally, for me, my thoughts are that the first part of the scheme requirement, that is, the media business must get transferred out of SPH will definitely go through as it only needs more than 50% of the votes of shareholders. It makes perfect sense to get rid of the loss making business unit from a commercial perspective. After that is done, I thought that there maybe a real possibility of another private equity fund coming to make an offer for the remaining SPH properties to compete with Keppel Corp. The current scheme offered by Keppel Corp contains a breaking fees levied on SPH should another party came along with a better offer. 
Screenshot 3: Break fees in event another party made a better offer

Even if there is no other offer and left with only the Keppel deal, probability of this deal going through will still be very high. Most retail owners who hold small number of shares in SPH and Keppel Corp will probably sit out any voting at EGM due to indifference to corporate governance. Only those few who felt strongly opposed to the scheme will want to come out to vote against it. The buying of shares via custodian accounts held from Saxo, Interactive Broker,  Tiger Brokers, DBS Vickers etc also makes it difficult in terms of administrative procedures for retail shareholders to try to attend AGM/EGM. As for the big boys, I have no doubt that these institutions will be voting for a "Yes" as there is much synergy to be gained from an M&A between Keppel Corp and SPH-pls see screenshot 4 below. 
Screenshot 4: Restructured Keppel Corp with SPH Integrated

Parting Thoughts:
I think that most shareholders will vote for this deal as the downside in not selling will mean that SPH will continue to be run by its current CEO Mr Umbrage. Personally, I would have preferred a SPH CEO with many years of experiences in property development or property management background instead of one with only extensive experiences from the Singapore Armed Forces only (please do not tell me that the current CEO also has much commercial NOL experience-this is irrelevant). Keppel Corp should have many of such talents in its group who can better run SPH. There is thus also much synergy in terms of manpower re-organization. 

(P.S: Note that I have acquired 14,000 shares of SPH recently from S$1.90 to $1.93 range post announcement of the Keppel offer. In the event that a black swan event occurs such that the deal does not proceed, holding on to SPH is still a relatively fair option given that it can still spin off its Student Accommodation Business into a future IPO to realize its intrinsic value. Seletar Mall and Woodleigh Mall can also be sold off into SPH REIT).  

Sunday, 25 July 2021

SPH REIT- Why One Should Invest In It Today In View Of SPH "Divestment" of Media Segment.

The million dollar question is what has SPH REIT got to do with the divestment of the upcoming Media segment from Singapore Press Holdings ("SPH")? The short answer to that is that we are now seeing the conversion of SPH to a true property management company (and to a smaller extent a developer like Capitaland and City Development from its development of Woodleigh Residences). There are 2 interesting developments arising from the ripple effect, that is, the (i) up and coming Student Accommodation business being injected and (ii) the possibility of new shareholders in the future mounting a takeover of SPH and merging its properties portfolio into their own REITs currently listed on SGX. I will elaborate a bit more on the above 2 points later in my post below. 

1. Misconception that Retail REITs is dead given that Pfizer and Moderna vaccine cannot prevent COVID infection as mentioned by some "analysts".
First and foremost, let me address this strange misconception by some of the "analysts" out there that lockdowns will be frequent and it will disrupt retail malls operations and hence huge plunge in rental income again. This is totally nonsense. We have seen from statistics present in Israel and also our local Singapore that both mRNA vaccines are extremely effective in stopping severe illness from COVID for those fully vaccinated. Yes, there is a chink in our current amour that even with 2 shots, a person might still become infected with COVID. But the difference here is that it has been scientifically proven that the incidents of moderate to severe illness for those fully vaccinated have gone down dramatically.  This means that our medical facilities will not be overwhelmed with rising COVID cases which is gradually becoming more like the normal flu.

It is also no secret that based on what the ministers have said, once the vaccination rates start to get to over 67% by 1st week of August'21, we will be moving on to a gradual opening up of our economies and targeted/selected closure of COVID clusters instead of the previous draconian closure measures. In addition, there is no doubt that we will need a 3rd shot booster soon by next year. Pfizer and Moderna are already working on a mix of current vaccine with a new Delta Variant vaccine combined to put an end to this dominant and infectious strain. 

2.  Government paying for wage subsidy and rental relief of retail tenants affected by "Heighten Alert"
 One piece of good news with recent restriction of dinning and movement is that the government has again took out money amounting to a S$1.1 billion rescue package for partial rental relief and wage subsidy. Retail REITS are thus spared from granting painful rental relief packages like last year. Although rental collected component has a small part that is dependent on retail sales of tenants, the effect will not be as drastic as the previous Circuit Breaker in 2020. 

3. SPH REIT performance has improved drastically with distribution yield being partially restored to an annualized 5.41% distribution yield. 
Gross revenue generation for SPH REIT for Q3 FY2020 has been remarkable across all its Singapore and Australian malls and improved by 22.2% year on year with a huge drop in required rental relief to eligible Singapore and Australia tenants.
The high occupancy rate of 98.4% of SPH REIT is driven by the resilience of its sub-urban malls with 100% occupancy at The Rail Mall and Clementi Mall. Also WALE of 5.4 years by NLA. This speaks volume of the strategic locations of all its Singapore and Australian malls situated at strategic locations with dominant catchments. 

Distribution yield has gradually recovered to 1.38 cents for Q3 FY2020. If we were to annualized this (remove 0.13 cents one -off non-recurring deferred prior year income)  based on S$0.925 per unit, this will be a distribution forward yield of 5.41%. If it recovers higher to pre-covid, then the distribution yield will be at least over 6.2%.
4. SPH After Divesting Media Segment- Ripple Effect on SPH REIT
As mentioned earlier, SPH will become a de-facto Property Investment and Management Group after the transfer of its Media business into a not for profit entity. There are 2 interesting ripple effect on SPH REIT here. 

(a) The student accommodation business in future maybe be injected into SPH REIT. While there is also a possibility of SPH spinning this into another REIT, there is a real possibility that SPH might just pump them into a single REIT for synergy purpose and compliance cost savings from another listing.

(b) Market talks these days have been rift that there will be new investors coming into SPH and these could include Keppel Corp, Capitaland or Mapletree Investments. This is not surprising given that these entities are ultimately owned by the Singapore Government. With the transfer of the media business out of SPH totally, there is actually no longer any good reason for there to be another property group in Singapore. It makes more sense for either Capitaland or Mapletree to come in and buyout the investment properties and then bundle them into their own existing REITs. Economies of scale and much cost savings is thus the logical future step going forward. For example, personally, I see no reason why we need to continue to keep the current CEO of SPH when there are other CEOs in Keppel Corp, Capitaland or Mapletree with the appropriate and more relevant industrial knowledge. There has been enough "umbrage" going around....time to move on and extend a golden handshake.
Parting Thoughts
What a year it had been for SPH REIT. From my last posting on SPH REIT on 23 December 2020 where I have mentioned that SPH REIT is severely undervalued by as much as 30% from its pre-COVID peak, one reader has disagreed vehemently on my valuation projection. Its current price is now at S$0.925 per unit as at 23 July 2021 with restored annualized distribution yield projected at 5.41%. 

As alluded to point 4, I think that eventually, it makes more sense to merge the entire SPH group with Capitaland, Keppel or Mapletree Investments. My personal thoughts is that it is an inevitable eventuality given the benefits of economies of scale. Personally, I will take umbrage if future corporate actions do not materialise.

Friday, 14 May 2021

Enhanced COVID measures as good as Circuit Breaker 2.0- Retail Mall REITs on firesales again?

This is shocking news-so many new measures within a day to restrict movement with effect from 16th May 2021 onwards- which is as good as a mini Circuit Breaker 2.0. All retail REITs, Frasers Centrepoint Trust, Lendlease, SPH REIT and Starhill Global began their sharp diving after lunch. Firesales 2.0 came again. Probably good time to start accumulating from today some of the retail mall REITs. Lendlease with 33% holdings in offices in Sky Italia Milan and JEM office tower will probably weather this 1 month storm better. Mapletree Commercial Trust price drop but still looks expensive with a yield that is barely 4%.

This mini CB 2.0 is going to kill retail shops again. Singapore government needs to get more vaccine supplies and increase the vaccination rates like USA and Israel. Else we will be stuck in this never ending circuit breaker.

Wednesday, 31 March 2021

Singapore Press Holdings Potential Corporate Restructuring- Possible Scenarios And Outcomes.

Singapore Press Holdings Limited (“SPH”) announces on 30 March 2021 that it is undergoing a strategic review to consider options for its various businesses as it believes firmly that it is undervalued by the market. Credit Suisse (Singapore) Limited had been appointed as its financial advisor for this purpose. This is coming straight on the heel of Capitaland. 

Scenario 1: SPH execute a same manoeuvre as Capitaland?
So will SPH also do a segregation of its property development business in Woodleigh Residences and shopping mall from its property management business of REITs and Student Accommodation, just like CapitaLand (please see my previous post)? I think not likely as the property development is a relatively small division out of the entire businesses of SPH. In addition, personally, I think shareholders will most likely laugh at the management team for being a copycat. 

Scenario 2: SPH privatize its loss making media segment and list property businesses out of altruism to shareholders
I think the best way with the highest probability of certainty in unlocking value straight away is to privatize the media business and just spin off the property arm into a new listed company call "Singapore Property Holdings". In this way, they can still retain the use of the acronym SPH. Also, for the media segment, they can choose to either (i) get government funding (since this is as good as a public good which the Singapore government will not allow shutdown despite long running mounting losses and it simply defies commercial logic) or (ii) learn from Australia and implement laws to force Facebook and Google to pay for the news from the old SPH. 

Scenario 3: Spinning off Seletar Mall into SPH REIT to unlock value in SPH
Anyway, I think the most likely outcome of the strategic review will not be something as big and drastic as what I had mentioned above. SPH will also not be able to do a public listing of its student accommodation business into a REIT as it just started some new acquisition here and needs to build up its stability. I think the most likely outcome is at most the spinning off of its suburban Seletar shopping mall into the portfolio of SPH REIT. A better bet would be to acquire more SPH REIT. Seletar shopping mall is coming off a bad year due to COVID's impact and its valuation would be lowered in the event SPH choose to sell off Seletar Mall. SPH on the other hand is still hanging on to its loss making media segment which is obviously its Achilles' heel dragging down its market pricing.

Parting thoughts:
SPH REIT share prices has been on an uptrend recently. I reckon many other investors have also foresee the possibility of the overdue spinning off of a mature asset of Seletar Mall to unlock value in SPH. Interesting move by SPH Senior Management team. I actually pray for something bigger than the selling off of Seletar Mall such as privatizing the loss making media segment and just listing the property businesses which is the real essence of the current SPH. Let's call a spade a spade.

Wednesday, 23 December 2020

SPH REIT Still Undervalued by 30% from Peak- Fear of new COVID-19 Outbreaks on Retail Landscape

SPH REIT and other retail REITs are still reeling from the mall closures and rental waivers during the worst season of the pandemic in Singapore from April'20 to May'20. Since 2017, the market valuation of SPH REIT on SGX has always been hovering between S$1.00 to S$1.10 per unit. The current unit price of S$0.840 per unit represents a 30% potential capital upside that still has not priced in much optimism on recovery but still sinking in extreme pessissim by the market. Fear is driving many investors away from SPH REIT citing potential future severe outbreak of COVID like the European countries, Korea & Japan and the end of retail at shopping mall as e-commerce (driven by e-marketplaces such as Amazon, Shopee, Qoo10 etc) continues to grow rapidly. This actually represents the best opportunity to continue scoping up units in SPH REIT while most folks are still fearful in order to reap the reward by waiting for the eventual retail recovery over the next 3-5 years. 

1. COVID Vaccines will be rolled out in early January 2021 in Singapore- First batch of vaccines received this week already. 
Singapore is the first country in Asia to receive the COVID Vaccine. As more and more vaccines became available to the general population, this allows for herd immunity (70% to 80% of population target) to be achieved without substantial fatality and thus reduces the probability of another "circuit breaker". 

The current "mutant" and more infectious UK COVID strain should not be a grave concern as the vaccines will be able to offer protection for it as per the leading CEOs of the respective vaccine developers.

2. E-commerce will end retail malls and their relevancy in Singapore?
I disagree with such belief. The retail scene is very different in Singapore compared to other countries such as European countries or the United States. Unlike in Europe and the US where cities were built around outdoor commercial streets and plazas, shopping malls in Singapore form an integral part of the urban landscape and consistently achieve high footfall especially at suburban neighborhood areas. 

Singapore is a land-scarce nation where the government controls the supply of commercial space through long-term planning policies and government land sales. This thus limit the supply of shopping mall relative to the residents living in a certain district.

In addition, shopping malls in Singapore have been adapting to shifting trends well by including more F&B outlets & educational centers into their tenant mix. Many malls are also experimenting with new retail stall concept. For example at Capitaland Funan shopping mall, the tenant Courts opened its first IoT-themed store, which retails the latest smart home, AI and voice-control technology from leading brands, incorporates interactive in-store experiential concepts and robotics. Swiss sewing machine brand Bernina’s flagship store at Funan offers a new lifestyle concept that includes themed sewing workshops, machine rental service as well as gift personalisation service.

3. SPH REIT maintained a strong balance sheet and operating financial metrics

  • One off non-recurring (touch wood-unless there is another lockdown) rental waiver of S$39.9Mil given to tenants in Singapore and Australia thus leaving FY2020 Net Property Income ("NPI") of S$182Mil. Non-recurring rental waiver thus comprises 21.9% of NPI.
  • As at year end 31 August 2020, occupancy rate remains high at 97.7%
  • As at 31 August 2020, SPH REIT’s gearing was stable at 30.5% while its debt maturities were well-staggered with no refinancing due till June 2021.
  • Net asset value per unit as at 31 August 2020 was S$0.91 per unit a decline of only 4.2%.


4. Most of the shopping malls under SPH REIT (with the exception of Paragon) has recovered to near pre-covid levels and Phase 3 launch on 28 Dec 2020 to further boost traffic.

4.1 Suburban local shopping mall (Clementi Mall etc) and Australian Shopping Malls
On 19 June 2020, the Singapore Government relaxed the COVID control measures and most businesses were allowed to resume trading. Progressively, businesses have started to show signs of recovery. With Phase 3 to commence soon on 28 December 2020, it is anticipated that dining capacity and overall shopper traffic will increase, which will in turn will benefit SPH REIT tenants’ businesses.

In the initial months when COVID-19 hit Australia, tenant sales declined in SPH REIT Australian malls in the continent. Unlike Singapore, in the cities where SPH REIT assets are located, there were no lockdowns, but there was some form of restricted trading, in particular, those with “touch points” such as cinemas and massage services. Since May 2020, both of SPH REIT’s assets in Australia started to show signs of recovery and from July 2020 onwards, tenant sales are almost back at pre-COVID-19 levels.

4.2 Paragon shopping mall in Orchard Road
Paragon’s location on Orchard Road appeals to locals as well as tourists. Its well-established premier upscale positioning continues to attract the target market from the local community. However, with the border restrictions imposed since February 2020, international tourist arrivals declined 97%. 

Without the tourists’ consumption along Orchard Road, which is the most visited free access attraction in Singapore, Paragon’s tenant sales were inevitably impacted. Paragon’s tourist visitation closely mirrors the Singapore Tourism Board’s report that about 30% of Orchard Road consumption is from tourists. 

The Medical tower of 90 specialist were also affected by the border restriction on the Medical Tourism industry and also circuit breaker which only allows essential medical procedures. However, Singapore is expected to open up gradually in 2021 to international visitors once vaccination rate improves for the general population. Personally, I expect Paragon businesses to recover close to pre-COVID levels in the 2nd half of 2022.   

5. High forward dividend yield based on $0.840 per unit price
Using 2019 quarterly dividend average of S$0.014 per unit as future operations norm, annual dividend expected is S$0.056. At current price of S$0.84, this represented a dividend yield of 6.7%-7.0% from good quality assets such as Paragon and future M&A pipeline of Seletar Mall and upcoming Woodleigh shopping mall for inorganic growth. Investors who went in now will have another capital upside potential of at least 30%. The world will not be defeated by COVID and medical advances with vaccines and better treatment will definitely lead to an eventual economic recovery. 
The Seletar Mall

Summary
The COVID-induced recession is one of the worst that the world has ever seen with economies coming to a virtual standstill. However, it also presented an opportunity to purchase retail assets at such a huge discount to their potential valuation. Buying into SPH REIT now is like buying into an Orchard Road prime property at 30% discount off. Investors who stay the course of their investment and who dare to make additional purchases this year and even early next year will see substantial returns on their retail REIT investments over the next 3-5 years. 

(P.S: On the subject of valuation, there are many variables and factors. For skeptical folks whose narrow mindset "understanding" of valuation concept is based on current known conditions only and not forward looking into the future and treat the REIT as a non-going concern and undergoing immediate liquidation, then the valuation will approximate to the last known NAV of S$0.91 per unit based on fair value of its investment properties on again known prevailing market conditions as at financial year end. A more logical valuation method would be to view the present value of net future inflow of economic benefits isn't it?)

Sunday, 10 November 2019

Singapore Press Holdings and SPH REIT Review- Media Segment Continues to Worsen But Bright Spot From Property Segment

Singapore Press Holdings ("SPH") continues to face headwind in its Media Segment. The media  business faces decline in print advertisement and circulation revenue. Worse still, the bloodletting from technological disruption has not reached the trough and its operating results is expected to deteriorate. Media revenue dropped from S$ 656Mil in FY2018 to S$ 577Mil in FY2019 which is a 12% decline. Media profit plunged from S$98.7Mil in FY2018 to S$54.7Mil which is a shocking 44.6% decline. At one point in time, its share price dipped below S$2 per share. Another round of retrenchment exercise has been announced by SPH to shave off 5% of staff in its Media Group. It has since recovered to S$2.34 as at 8 November 2019.
Extract of Business Segment Performance-Profits before taxation
Despite the pessimistic outlook for its Media Segment, there is a bright spot in SPH, that is, their Property business segment which continued to grow from strength to strength,. As overall outlook of SPH is not stable and no one knows exactly when the bottoming out of the Media business will occur, my preference is to invest only in SPH REIT until there is more clarity to SPH future projections. 

A delightful piece of good news was announced by SPH this week. 

SPH REIT Revealed Another Major Surprise- Acquisition of New Australian Super Regional Shopping Mall in Adelaide
SPH REIT announced on 7 November 2019 that it has acquired a joint venture stake from Lendlease Real Estate Investments Limited Group in Westfield Marion Shopping Centre, Adelaide, South Australia for S$637Mil. This was a major surprise to many investors and myself who thought that the recent fund raising via S$300Mil of perpetual securities was to fund the purchase of Seletar Mall from SPH. While I have previously posted  that the last December 2018 acquisition of Figtree Grove Shopping Mall would give SPH REIT management team invaluable management exposure and networking into the Australian market, I never expect that the next Australian retail acquisition to come so quickly in less than a year. 
Extract of Westfield Marion Shopping Centre Details
SPH REIT still no fate to be with Seletar Mall
I can't help but feel a tinge of sadness as Seletar Mall once again escaped from the clutch of SPH REIT, notwithstanding the surprise acquisition of a good quality Australian freehold asset. But the good news is that Seletar Mall is still in the future pipeline of SPH REIT. So too is the Woodleigh shopping mall which is under construction which bodes well for the future growth of SPH REIT.
The Seletar Mall
Parting Thoughts
SPH has been building up its Property division for a number of years to diversify away from its traditional media business and this strategy is bearing fruits. Besides the property development and retail REIT portions, another superb sub-segment is its student accommodation business which is widely viewed as extremely defensive with strong resilient earnings even in economic downturn. Unfortunately, to get a piece of student accommodation action, one would need to invest in SPH as this is not available on SPH REIT. Perhaps SPH may start another REIT in future that focuses on student accommodation.