The "New" Keppel transformation is executing right on track. M1-Simba deal collapse but Starhub now in driver seat.
Showing posts with label Keppel Ltd. Show all posts
Showing posts with label Keppel Ltd. Show all posts
Wednesday, 7 October 2026


Wednesday, 18 February 2026
Keppel Ltd Overvalued After Recent Rally and Confusing Final Dividends Reported In Media?

1. Final Dividends Is S$0.47?
The ambiguous dividends totality in most mdedia is further compounded by the Straits Time and Business Times that state that Keppel Ltd has declared a "final dividend" of S$0.47 per share. So is this referring to the overall total dividends for FY2025 or the 2nd half FINAL dividend tranche?
 |
| Extract from Business Times |
As it turns out, the news media have been rather loose in their reporting these days. S$0.47 per share should not be crafted as "Final Dividend". Rather, I think the correct wording should be "TOTAL dividend" for FY2025. This is because S$0.47 per share of "final" dividends reported by the Straits Times and Business Times actually comprises of an interim cash dividend of S$0.15 per share that was already paid out in August 2025- we thus have no choice but to deep dive into the announcements by Keppel Ltd.
 |
| Extract from Keppel Ltd Full Year Presentation Deck |
2. Special Dividends Clarification
Also, the main stream media has been rather ambiguous on the nature of the S$0.13 per share of "special" dividends. As per above extract from Keppel's presentation deck, the S$0.13 is made up of 2 components:
(i) Cash dividend of S$0.02 per share and
(ii) Dividend in-Specie of 1 KREIT unit for every 9 Keppel shares held which is equivalent to S$0.11 per share. This valuation is based on Keppel REIT's closing price of S$0.98 per unit on 3 February 2026 as well as Keppel's issued share capital of 1,801,659,827 shares as at 31 December 2025. I would think that the valuation of this from retail investor point of view would be the upcoming ex-dividend date whereby the legal obligation has been fully transferred to the hands of shareholders hence it may not be really S$0.98 per unit at that juncture. As a matter of fact, its price as at 16 February 2026 has already dropped to S$0.95 per unit.
2A. Illustrative Example of Quantum of Special Dividends
(i) Assuming one is holding on to 9,900 Keppel Ltd shares. The final dividends due after AGM approval will be S$1,881 (S$0.19 per share X 9,900 shares).
(ii) Also to further illustrate how the dividend in specie works, assuming the same 9,900 Keppel Ltd shares. So the investor would be entitled to 1,100 units of Keppel REIT (9,900 shares divided by 9). So the special dividend in specie would be S$1,078 (1,100 units X S$0.98 per unit). Add on the special cash dividends in such case, one would get cash special dividends of S$198. Hence total special dividend awarded will be S$1,296 in special cash dividend and dividend in-specie.
Total upcoming final dividends in such scenario will thus be S$3,177.
3. Ex-dividends and Payout Dates.

The ex-dividend date for the final dividend is 27 April 2026 while the pay-out date is on 8 May 2026. So, take note of these key dates if you are an investor of Keppel Ltd.
Personally, I will not buy anymore of Keppel Ltd at this juncture as I think that it is overvalued from a dividend investing strategy perspective. Its normalised dividend yield of 2.6%, as previously discussed in point 1 above, is too low for me at its current market price of S$12.68 per share. My entry price for this investment is around S$6.45. I do not think that there is any fundamental change since my first purchase as the senior management of Keppel Ltd has already announced their new strategy of fund management and focus on recurring income 2 years ago. The only exception is that Piyush has joined the board of Keppel Ltd but take note that it is a non-executive role and this seemed to be the main reason folks are chasing after Keppel Ltd. This is probably due to Piyush's stellar track record in transforming DBS before leaving it and joining Keppel Ltd- I called it the Piyush's effect.
Last but not least, the new FY2026 seems to have already another "special" dividend guaranteed for next year payout. This is because the S$1 billion cash sales proceed of M1 will only be counted towards FY2026 and Keppel Ltd management has mentioned that they will be returning back part of all successful monetisation efforts (10%-15%) in the form of special dividends to shareholders.
Ok, that's all folks! Have a great week ahead! Happy Lunar New Year to All! Huat Arh!
(P.S: Please see my previous investment thesis on Keppel Ltd back in 2024- Click link to post here)
Saturday, 1 November 2025
Investment Portfolios Updates (31 Oct 2025) - Net Investment of S$910K and Projected Annualised Passive Income of S$48K.


A rising tide lifts all boats indeed. My net investment portfolio jumped by almost +S$100K within 2 months (from S$813K to S$910K) mainly due to the rise of Alibaba AI and Cloud play as well as the revival in Singapore REITs. Gross investment is now at another record high of S$1.179Mil.
1. Portfolio 1- Stocks Held in SGX Central Depository

2. Portfolio 2- Margin Purchased Securities
(Note: My margin purchased securities has grown to a sufficient scale to sustain itself and can pay off annual financing charges as well as to gradually pay down the margin loan through the dividends generated.)

Keppel Ltd has been delivering a super impressive profit growth of 25% (if we normalise and exclude the one-off recorded loss for sales of M1) for the 9mth ending 2025. In addition, have subscribed for 5000 excess units of Keppel Date Centre REIT ("KDC") and managed to get all- please see here for the past blog post I made.
3. Portfolio 3 (with Tiger Brokers and MooMoo)
(Venture into higher risk as well as capital growth stocks here)

4. Portfolio 4 (Endowus Unit Trusts & Other Investments)

Parting Thoughts
Currently, my growth strategy investment is on Alibaba and BYD in China market. I continue to stay away from the US market (except for a small stake in United Healthcare Group). Overall, I am still committed to my dividend passive income strategy and continue to build it up gradually by increasing stakes in Unit Trusts to ensure sufficient diversification.
Ok. that's all for today Folks. Have a great week ahead!
Monday, 6 October 2025
Taking a Punt in Keppel DC REIT Rights Issue To Make Small Immediate Profit.

For my thoughts on whether I will be subscribing for this latest rights issue and key application milestone from Keppel DC REIT ("KDC"), please refer to my earlier post. Additionally, have decided to take a punt and make use of Keppel DC REIT ("KDC") rights issue exercise to try to earn some spare cash. The current market price is S$2.40 per unit as at Oct 3, 2025 (Friday) which I think is the peak price for this period. and price will start dropping from this point. Generally, by the time the new units get listed on SGX (Oct 22, 2025), the market price will commence tapering off as some investors will not feel happy with subscribed folks who are getting new KDC units at a discounted S$2.24. So the period from Oct 3, 2025 till Oct 22, 2025 will present an opportunity to maximise making the most money for immediate realisation and usage which I will further elaborate below. In fact, the probability of this one off punt making money is higher than striking the SG Toto's Group 7 prize (striking 3 numbers and winning S$10).
1. Key Factors to Consider
(a) No major changes in macro-economic outlook or market events causing sudden surge in market prices within this short period;
(b) Able to have the "lobang"(via your stock broker) to get one's hand on the exact same number of excess rights issue as the number of units that one will be selling off immediately so as to maintain the same number of holdings in KDC;
(c) No of units for immediate sell-off should be of sufficient size to make the transactional trading cost (referring to selling cost here as the rights allotment admin fees is just S$2 irrespective of size of the subscription/purchase) worth it.
(d) As alluded to 1(b), if unfortunately unable to get the full 5,000 units of excess rights, then I will re-invest the proceeds into other higher yield SREITs. I believe that KDC current 4% per unit will be easy to beat.
2. Execution of Plan and Mechanics
On the morning of Oct 6, 2025 (Monday), I have sold off 5,000 units of KDC at S$2.39 per unit for a total of S$11,950 (sold off immediately at S$2.39 bid price as I decided against queueing to sell at S$2.40 per unit).
Subsequently, I have made an excess rights application of 5,000 units of KDC at S$2.24 (totalling S$11,200) on top of my allocated allotment with my stock broker.
3. Mechanics & Targeted Profits
I am targeting for a quick profit realisation of S$750 (S$11,950 less off S$11,200) with the above maneuver by locking in the selling price of S$2.40 per unit as of Oct 6, 2025 morning.
Parting Thoughts
Overall, I have no interest in increasing my stakes in KDC by too much as it is only yielding 4% and the market price per unit is at a huge premium over its NTA per unit. Market seems to be pricing KDC as a growth stock. Hence I am taking a bet that S$2.40 per unit is the peak market price reached for this rights issuance and to sell off immediately to optimise the profit realisation.
Saturday, 30 August 2025
Investment Portfolios Updates (29 August 2025) - Net Investment of S$813K and Projected Annualised Passive Income of S$48K.


Hi Folks, welcome back to my bi-monthly investment portfolios update. With the anticipation of the long awaited lowering of US interest rates finally having a high chance of materialising after Powell's recent speech, REITs' rally became more sustainable from the expected higher distributable income from much lower financing cost. Let's keep our fingers crossed that the September 2025 first rate cut of 25 basis points happen as per anticipation- I really have enough of the roller costal ride over the past year. With the recent strong rally from REITs, my overall gross portfolios hits S$1.08Mil while net portfolios after leverage hits S$813K. This is a drastic improvement of almost +S$80K in just 2 months from the market recovery. As a mainly dividend focused strategy investor, it is not this capital gain that excites me but rather the upcoming additional cashflow expected from the lower interest rate effect on my various investment portfolios and additionally, the significant savings from my margin loan.
1. Portfolio 1- Stocks Held in SGX Central Depository

2. Portfolio 2- Margin Purchased Securities
(Note: My margin purchased securities has grown to a sufficient scale to sustain itself and can pay off annual financing charges as well as to gradually pay down the margin loan through the dividends generated.)

3. Portfolio 3 (with Tiger Brokers and MooMoo)
(Venture into higher risk as well as capital growth stocks here)

4. Portfolio 4 (Endowus Unit Trusts & Other Investments)

Parting Thoughts
Well, I am happy that the interest rate cuts from my wish list is finally materialising. Ok, that's all the updates I have for today folks. Have a great week ahead!
Sunday, 13 July 2025
Keppel Ltd Rising From The Ash- Transformation On Target and 4.39% Dividend Yield For Waiting.

Recently, the share price of Keppel Ltd finally roared back to life after being in a limbo for the past 2 years. From its share price of S$6.87 per share as at beginning of January 2025, it has now hit an improved market valuation of S$7.74 per share as at 11 July 2025. This is an impressive 12.7% capital appreciation in 2025 alone for all retail investors. Congrats to all fellow shareholders who are holding on to Keppel Ltd and have subscribed to the revised asset light model strategy which focuses now on building up recurring income from management of investment assets. For myself, Keppel Ltd has been my best performing non-banking stock with a total gain of +S$22K (including S$6.2K of dividends) which is a +27.8% return. I had been accumulating shares of Keppel Ltd from May 2023 to November 2024. I have listed below the reasons for the sudden rise in the market price of Keppel Ltd.

1. The Piyush Gupta Effect
Personally, I think that this is the main catalyst for the recent spike in the share price of Keppel Ltd. Once Keppel Ltd announced the appointment of the ex-CEO of DBS as its deputy Chairman and non-executive independent director, the market became mad with excitement. Piyush has a stellar strong track record in transforming DBS into a leading digital bank in Singapore. His experience in driving digital transformation and innovation, as well as his leadership in navigating complex business environments, is seen as a valuable asset for Keppel as it reinvents itself as a global asset manager.
Strangely enough, the share price of Keppel Ltd seems to have suddenly been re-rated by analysts and the entire market by this single announcement and the share price started soaring. Other supplementary reasons for its rise from the ash are as per below:
2. Strong Financial Results
Keppel Ltd Q1 2025 net profit rose 25% year-over-year, driven by stable infrastructure earnings and a 9% increase in asset management fees-S$96 Mil. FY 2024 profit (excluding offshore & marine) increased by 5%, with data-center margins up ~45% thanks to AI and digital infrastructure tailwinds.
3. Robust Asset Monetisation
Since FY2023, the monetisation of non-core assets has been substantial: S$347 Mil in Q1 2025 alone and S$4.8 billion cumulatively since 2020. Analysts estimate another upcoming S$550 Mil asset sale pipeline in India and Singapore.
4. Recurring Revenue and Asset Manager Pivot
Keppel’s Vision 2030 strategy has rebalanced earnings towards recurring income—from 60% in 2022 to over 80% in Q1 2025 from infrastructure, fees, and data centers.
Its commitment to manage S$200 Billion AUM by 2030 is advancing, with S$88 Billion reported end-2024, and another S$4.9 Billion raised in Q1 2025.
5. Strategic Partnerships & Capital Inflows
Keppel has secured S$2 Billion in institutional investments for data centres, education, and sustainable urban renewal funds. It has also recently partnered with Asian Infrastructure Investment Bank (“AIIB”) for a S$1.5 Billion green-infra investment program across Asia.

Parting Thoughts- Personal Views on Keppel’s Outlook.
Based on its historical annual dividends of S$ 0.34 per share and its market price of S$7.74 per share as at 11 June 2025, this is an annualized dividend yield of 4.39%. For myself as a dividend investor, this is still somewhat attractive to me taking into account Keppel’s target to grow its asset under management to S$200 Billion by 2030 and I will be holding on to my remaining shares. Saying that, from a risk management perspective, I will not be adding on to my current investment into Keppel Ltd as it already made up close to 10% of my gross portfolio value and I have in fact sold off part of my holdings last month to take some profit off the table. Hopefully, Mr Gupta will be able to put in some of his magic into enhancing further growth opportunity for Keppel Ltd for all investors. Let’s wait and see! :)
Monday, 25 November 2024
The Upcoming Acquisition of New Data Centres for Keppel DC REIT Are Not As Rosy As What Many Believes-Part 1 of 2.
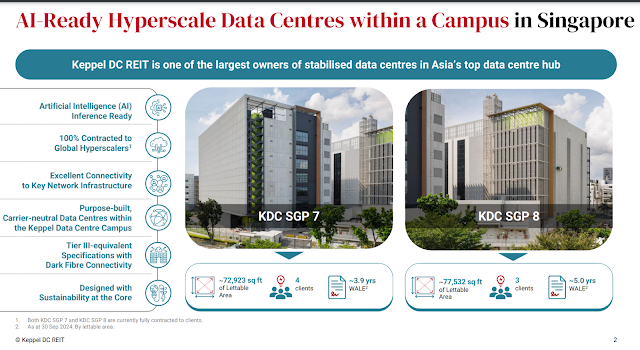
The top news for the past week, which many SREITs investors are super excited about, seems to be the acquisition of the Genting Lane Data Centres by Keppel DC REIT (“KDC”) from its Sponsor Keppel Ltd. Many analysts and also postings on social media by bloggers & YouTubers have been singing high praises over the upcoming acquisition and the associated equity fund raising of over S$1 billion in capital. The private tranche has over 3.4 times of oversubscription and I believe that the upcoming preferential offerings for retail unit-holders will be also as hot and crazy. While I think that this deal is sensible, nevertheless, I thought that it is not exactly a fantastic one and there are some key risks here that some investors seemed to have closed one eye given the hype over Generative AI and the usual strange belief that KDC can grow its distribution per unit indefinitely with many more such "upcoming fantastic acquisitions".
Things are not exactly rosy at KDC
Well, I don’t want to be a wet blanket here. I mean I am also a former firm believer that the data centre leasing business has resilient demand with tenants that will not be migrating upon expiry due to the significant challenges in moving all the data servers and that the current Tech focused world means that this is the latest hot cake that will be growing exponentially to cater to the insatiable market demand-look at the mind whopping double digit rental reversion that the Data Centres are charging their tenants upon lease renewal-KDC announced during their half year results that they have renewed a major tenant for +40% rental reversion. The prospective new leases at Genting Lane Data Centres are also asserted to be up to 10% to 20% lower than the prevailing market rate which implied more potential upsides upon their current lease tenant contract expiry.
However, folks seemed to have forgotten about (i) KDC trouble at Guangdong DC and (ii) also that its current distribution to unit-holders are on artificial life support with S$13.2Mil none-recurring distribution from the DXC settlement that the management has cleverly spread over the 1st half and 2nd half of FY2024 respectively to avoid a significant tapering off in distributions to unit-holders. (iii) In addition, the new acquisition is not a free-hold building. The ownership is only for 15 years or 25 years if the extension option is being exercised and paid for. I call these the 3 key risks of holding on to KDC which I should elaborate on further:

(i) KDC trouble at Guangdong DC
I have not heard updates from any reports that the Guangdong DC losses have been plugged. I recalled vividly that Keppel DC is still unable to collect any rental income from this DC. This is extremely bad news. We need to be surgical here. The 1st half DPU from KDC is only 4.549 cents. Normalizing this, the projected DPU for FY2024 hovers around 9.098 cents or S$0.09098 per unit. Taking into account its current market price of S$2.220 as at 22 November 2024, this implied an absurdly low distribution yield of 4.1%.
(ii) There is S$13.2Mil of DXC settlement that has been spread over the 2 halfs of FY2024
What this means is that if not for this DXC non-recurring settlement fees, the DPU for KDC will drop even lower than the already rock bottom 4.1%. Even with the recent upcoming acquisition of the Genting Lane DC which proclaims to be DPU accretive of up to +8.1% , the new projected DPU will be at a yield of 4.43%. Bear in mind that we are no longer in a zero or extreme low interest rate environment anymore unlike the last decade.
Also, this deal is being structured such that only 49% of the control of the new data centres falls under phase 1 in December 2024 while the remaining 51% will only complete in 2nd half of FY2025 (next year) so the effect of the increase of the +8.1% will not be immediate. So, this means that the yield is unfortunately still not very attractive for myself. I am expecting a yield of at least 5.5% to 6% for holding on to KDC.

Given that this deal is valued at S$1.3 Billion, this will bring the Assets Under Management ("AUM") to S$5.2 Billion. 25% of AUM of KDC will thus be under the very short tenure of 25 years which is the norm for industrial property in Singapore. What this means is that the assets value will plunge to zero and unit-holders will need to be ready for another equity fund raising to extend the tenure from government agency JTC. This brings us back again to my point that 4.43% distribution yield is extremely low as unit-holders need to prepare to plough back capital into KDC at the end of 25 years. Keppel Infrastructure also have this issue with their concessionary assets under management but at least their dividend yield of approximately 7%-8% will cover part of the capital recycling cost to unit-holders.

Summary of Part 1 of 2
Note that above are just my personal thoughts guiding myself on whether I should be subscribing for this KDC preferential offerings. You folks may have a totally different and optimistic view and that is fine. So don’t roast me for this post.
In view of the above, I think I will only be subscribing to the bare minimum based on the allotment ratio and some extra to round up the numbers. I think that there is still a possibility that the market price of KDC may decline further.
Sunday, 3 November 2024
Keppel Ltd Heavily Leveraged And Un-investable?

Keppel Ltd’s share price has pulled back from its recent high of S$6.65 in early October 2024 to the recent S$6.40 per share. It’s yearly dividends (excluding special dividends or in specie dividends) is around 33 cents to 34 cents. Hence normalised dividend yield is at around 5.3% based on its current share price of S$6.40 per share. I thought that it is a good time to accumulate more of Keppel Ltd after the recent pull-back.
The Concerns of High Debt to Equity Ratio of 0.9 Times.
Interestingly, there were some skeptics who have condemned Keppel as un-investable and unstable due to its substantial borrowings. The high gearing is due mainly to Keppel’s investment properties and property development segment as well as the infrastructure division. Nevertheless, below are 3 reasons why I would personally still invest into Keppel Ltd.
1. Shift in Business Model To Focus More on Recurring Income Instead of Capital Intensive Business
The building up of recurring income is on the right trajectory. As seen below, the recurring operating income now forms a substantial part of Keppel’s income streams-asset management and operating activities (sales of gas, electricity, telecommunication services etc amounted to S$773Mil in 2023. This is a 54% increase relative to 2022 and makes up 88% of net profit for 2023. Keppel’s strategic shift to focus on recurring income and monetisation programme will also release more funds for investments and debt repayment.

Keppel is only paying out about 60%-70% of its earnings per share as dividends to shareholders and retaining the rest for its existing businesses. For 2023, It has a diluted EPS of 49.1 cents and paying out only 34 cents as dividends.
3. Prize Jewel in Data Centres Development and Management.
Keppel has recently announced that it intends to expand its current DC capacity from 650MW to 1.2GW in the near term with an additional S$10billion funds under management growth. This will take 3-5 years as these DCs will be built from scratch at selected sites.
The DC at Genting Lane is a good illustrative example. After the development of the DC, they will monetize it by selling to Keppel DC REIT. After selling it off, Keppel will still make recurring income from the management of this investment property as Manager and also rental income from its ownership in Keppel DC REIT.

Parting Thoughts
Last but not least, Temasek Holdings holds more than 20% stake in Keppel Ltd. In the event of a full-blown financial crisis, Keppel Ltd will be able to tap on the financial might of its substantial shareholder as its final life line to avoid a fire-sales at the worst possible time. I have recently sold off S$20K of my Keppel DC REIT after its strong recovery from its record low in the past 2 years which resulted in its distribution yield dropping to only a mere 3.9% with 90%+ payout and reinvested the proceeds into Keppel Ltd.
Tuesday, 13 August 2024
Opportunity To Acquire This Quality Non-Banking Blue-Chip That Has Dropped 20% from its Peak.
I thought that now is a good opportunity to accumulate more shares of this blue-chip on SGX which has dropped 20% from its peak this year albeit the not too bad operating results. Accumulated 2 tranches at S$6.20 per share (700 shares) and S$5.93 per share (1,000 shares) on 2 Aug 2024 and 8 Aug 2024 respectively.
Please see below for my latest video on YouTube channel. Going forward, I will be posting various exclusive investment contents onto my YouTube channel only. Please subscribe to my YouTube channel also to get the latest content for sharing.
Subscribe to:
Posts (Atom)