Saturday, 15 May 2021

Singtel Reported Impairment of S$1.2 Billion- Horrible Results Expected for Full Year of FY2021 and "Strategic Review"

On 14th May 2021, Singtel announced a shocking S$1.2 billion in impairment charges for its investments in digital marketing firm Amobee (-S$589Mil), cybersecurity business Trustwave (-S$336Mil) and also Optus (-S$204Mil). Singtel used to be extremely defensive about its Amobee and Trustwave businesses and argued that the thrust towards digital investments in new business and North America market is good for Singtel in the long term. However, Singtel appears to be singing a different tune this time round with a power-point deck on "lessons learnt" from these digital investments that are now being partially written off. It should have focused on digital opportunities in Asia to leverage on its current customer base instead of focusing too much on the North American markets for its Trustwave and work with strategic partners by taking up minority stakes instead of a majority. 

S$1.2 Billion Impairment Charges

Strategic Review Commencement
Group Digital Life still facing huge losses during past 9mths till Q3 FY2021

It is quite disappointing that S$1.2 billion is wasted and thrown into the drain just like that. Apparently, Singtel had taken a bite more than it could chew. It does not have enough internal talents to pull off its digital businesses by itself.  On top of the impairment, Singtel has been throwing more good money after the bad in terms of running the business as it has always been in the red. But at least the new CEO of Singtel seems to be making a right decision to embark on a course of corrective action to try to stem the losses at the underperforming business segment. 

Any bright spots?
I think it would be hard to market an IPO off the loss making digital business in the near term. Singtel is more likely to be looking for a strategic partner to sell off a majority stake in them. 

The bright spark may lies in Singtel’s information and communications technology (ICT) arm NCS which, since 1st January 2021, operates as an autonomous business unit, reporting directly to the Group CEO to accelerate its expansion into Asia Pacific, with special focus on Australia and China. It is highly likely that Singtel will decide to spin off its former Enterprise Group NCS through an IPO to unlock intrinsic value in Singtel Group. The good thing about NCS is that it has many Singapore government IT contracts as its operations executives have good networking and understanding of the local requirements of government agencies.  

Parting thoughts
I think that the upcoming full year results for year ending 31 March 2021 is going to be super ugly for Singtel. With the departure of the former CEO and a new CEO on board, this is now a good time to clean off legacy issues and move towards "supercharging the future". 

Friday, 14 May 2021

Enhanced COVID measures as good as Circuit Breaker 2.0- Retail Mall REITs on firesales again?

This is shocking news-so many new measures within a day to restrict movement with effect from 16th May 2021 onwards- which is as good as a mini Circuit Breaker 2.0. All retail REITs, Frasers Centrepoint Trust, Lendlease, SPH REIT and Starhill Global began their sharp diving after lunch. Firesales 2.0 came again. Probably good time to start accumulating from today some of the retail mall REITs. Lendlease with 33% holdings in offices in Sky Italia Milan and JEM office tower will probably weather this 1 month storm better. Mapletree Commercial Trust price drop but still looks expensive with a yield that is barely 4%.

This mini CB 2.0 is going to kill retail shops again. Singapore government needs to get more vaccine supplies and increase the vaccination rates like USA and Israel. Else we will be stuck in this never ending circuit breaker.

Friday, 7 May 2021

Singapore Press Holdings Finally Got Blessing From Government To Get Rid Of Its Loss Making Media Segment

What a wonderful development! Singapore Press Holdings ("SPH") finally got the green light from the government to get rid of its loss making media segment. In my last post on the potential restructuring scenarios, I have been hoping for the disposal of its loss making media segment for the longest of time and it finally materialised. But still, I was quite disappointed that SPH need to waste money to appoint Credit Suisse as their "financial advisor" for the restructuring exercise. Is it not obvious that in a commercial business, loss making segment needs to be closed down or sold off instead of allowing it to fester for so many years? The essence of such a corporate restructuring actually lies in going after the various government agency/Ministry to lobby for such a move. The green light for such a daring manoeuvre can only come from the blessing of the Singapore government- you do not need an external financial advisor for this. 


The free S$80Mil cash injection and donation of SPH and SPH REIT units worth S$30Mil to the new entity as SPH's divorce settlement deal with the loss making media segment is actually a very small price to pay. SPH profitability of 1 year from its pre-COVID property business should be more than adequate to cover this hence inflicting only a tiny dent in its overall long term financials.

The only key question now is the branding of SPH going forward. With no media segment at all, does it still make sense for it to call itself "Singapore Press Holdings" when it is in fact a real-estate Group? Also, I am extremely disappointed that with the appointment of a financial advisor looking at this for 1 month on available options, they could have also added in the deal to divest Seletar Mall to SPH REIT to unlock further value. 

Sunday, 2 May 2021

Equity Portfolios Updates (30 Apr'21)- The Return of Increasing New COVID Clusters And Will It Lead To Another Singapore Lockdown?


It is worrying when the Singapore government starts to talk about a second circuit breaker is on the table if current measures to tighten the surge in local COVID does not curb it successfully.  Based on current cases, it may get worse over the next few weeks. I am awaiting the release of more findings by the Ministry of Health with regard to how effective is our COVID vaccines and how the virus managed to "break through" doctor and nurses who already got 2 full shots of the vaccines. Is it due to mutant strains whereby current vaccines are no longer effective? There is a high chance that upon the first trading day in May'21, the SGX might see a huge drop in prices due to concerns over a 2nd lockdown. I also think that various government agencies are tightening anti-COVID control measures and there will be more government announcements next week. It maybe a good idea to take some profits or do some switching into safer class of assets.

1. Portfolio 1- CDP held stocks
For my cash portfolio, not made much changes since last update. 

2. Portfolio 2- Margin purchased securities
With the announcement by DBS of a record breaking S$2 billion dollars profit, all bank counters benefitted and increase last week. I have taken advantage of this surge to sell off more of my DBS and UOB holdings to take profit and also switched into Mapletree Industrial Trust ("MIT") which is suffering from a momentary price weakness. 

MIT is targeting to grow its data centres high tech portfolio. Hence there will be more acquisition coming up. Also the Singapore government is backing MIT. I foresee further capital growth and potential of MIT to appreciate beyond S$3.30 per unit.

As for our local banks, I think OCBC is still undervalued hence I am still holding on to them. If the next week results from OCBC quarterly report is just as good as DBS and price shoot up further, I will be paring OCBC down and re-invest the proceeds into other stocks.

I have also paid down some margin to reduce the use of leverage here in view of the increasing COVID cases which have increased the macro-economic risk of our local scene.

3. Portfolio 3 (with Tiger Brokers)- Venture into high risk stocks here
The damn low commission fees of 0.08% allows investor to take up tiny bite size high risk counters at a fraction of the normal brokerage commission. This allows better risk management in the event of bankruptcy or huge capital losses of the investments. I have thus made additional investments into FSL Trust, Sabana REIT and Oceanus Group but only taking up tiny portion and diversifying them.  

The best performing counter in this portfolio is FSL Trust which has returned over 20% profits (including upcoming hefty dividend payout) in just 2 months.

For Sabana REIT, the key risk here is that the much anticipated acquisition by ESR never materialize. 

For Oceanus, the pricing of S$0.039 per share is overvalued if we looked at the historical results. However, if you believe in the 4 pillars strategy marketed by their CEO (which seems to be turning around the business with new growth segments), then there is actually tremendous growth potential here. Again, too many variables here hence I only intend to take a bite size stake in this counter. I will do a further post on Oceanus group in the future. It has a very intriguing and colorful history including possible internal sabotage which had led to the death of many of its farmed abalones and financial crisis previously.

Parting thoughts
I am looking forward to the upcoming dividends from Global Investment, FSL Trust as well as the 3 local banks in May'21 and June'21 for re-deployment.  Let's keep our fingers crossed that the COVID-19 situation can be well contained over the next few weeks to avoid another economic lockdown which will derail our recovery.   

Tuesday, 27 April 2021

Tesla Posts Net Profit for Q1 FY2021 But Is It Really Making Money?

I find it strange that many investors are betting big on Tesla even when it is in fact still suffering from operating losses. The current net profit of US$438Mil for the quarter ending 31 March 2021 is misleading. Out of these, US$518Mil are actually environmental green credits purchased by other automakers from Tesla due to regulation. Without this US$$518Mil, Tesla will be staring at a net loss from its basic operations of selling EVs just like the previous quarters.

From USD88 per share in Jan 2020, it has shot up to the current USD738 per share which is an incredible 738.64% increment despite the losses at operating level. Is a loss making venture worth so much money? Does it mean that the car market share in future of Toyota, Honda, BMW etc will all be taken over by EV from Tesla? If not, then Tesla may be in for a big correction eventually. Those who are jumping in or already made big bucks over the year from investing in Tesla, asserted that they have an eye for spotting good investment opportunities. As for me, I am staying away from Tesla for now as it is clearly not for the faint-hearted. 

Friday, 23 April 2021

How I Almost Got Into a Ponzi Scheme Trap In Singapore

Sunshine Empire is one of the most notorious ponzi schemes in Singapore in 2006 that had swindled 20,000 Singaporeans (including many retirees) out of nearly S$190Mil. It has no legitimate profit generating business mechanism and instead relied on money from new investors to pay old ones. Not everyone loses money in a ponzi scheme. Those who entered as the pioneer batch actually can make lots of money. In spite of such news being published, the general public will eventually forget about such scams and new ponzi schemes will always re-surface and succeed in hoodwinking unsuspecting people.

My recent encounter with a Property Investment Scheme in China
This scheme is being marketed by my neighbour and also an ex-colleague just before COVID. Apparently, the China government is keen to help out all chinese people overseas. This investment scheme is opened to only chinese and supported by the China government as asserted by my neighbour and also ex-colleague. The investment involves buying a package into the development of one of China's 3rd tier cities. One can get back more than 100% within a few short years and make a huge profit. Once you signed up and pay for a package, you will enter and join into an investment "family" something like MLM upline/downline system. You also then need to bring in more victims investors into your "family" to increase the rate of return of your invested packages. The China development sponsor will also bring you on live tours around the china city for one to see the infrastructure development to prove that it is not a scam. Lodgings, drinks and good food are all provided.

Good people duped into scam
Make no mistake, the people who joined are probably some of the smartest people in Singapore. Some are businessmen who run their own businesses and some are professional & well educated folks like my ex-colleague who was once an audit manager in one of the big 4 public accounting firm. They flew to China to assess for themselves and took out money to buy the packages and then went on to recruit downlines to enter into the investment scheme. As with all fly by night businesses, the China operator only marketed how much return one can get and avoid all questions on the details like how the business operate and keep trying to get you to go down to the China city to see for yourself. I think that these are all tell-tale signs that a ponzi scheme is in operations. The scammers cleverly exploited a rampant fear of missing out on a golden opportunity as well as selective entry criteria to attract investors. 

Parting thoughts
I was lucky to have rejected my neighbour and also ex-colleague in their invitations to go to China to take a further look at their new investment scheme. The last I know, they were embroiled in a lawsuit against each other (their investment "family members") for losing money over the investment scheme. 

(P.S: On a side note, I am quite curious on what happened to the mastermind of Sunshine Empire scam James Phang. Saw that he has served his sentence in Singapore and is out of prison but faced charges in Malaysia. Also not sure whether the sunshine empire investors got back part of their money.) 

Friday, 16 April 2021

The Sabana REIT Showdown Between Sponsor And Unit-Holders

I used to be a unit-holder of Sabana REIT back in 2011. I recalled its unit price dropped after IPO (@ S$1.05 per unit) and then I started accumulating units for investment. Anyway, I held onto Sabana REIT for a short time due to its high dividend yield after the decline in price post IPO. But once I observed that the previous management seems to be having trouble getting new tenants and a potential cut-back in dividends, I got extremely worried and exited towards the end of 2012. But if one has been holding on to Sabana REIT since IPO, the total returns if inclusive of dividends is actually just a loss of less than 10% albeit the unit price dropping by more than half- so still not too bad. Since the end of March'21, I have started taking up a small investment stake into Sabana REIT despite the current ongoing spat ("War" maybe a better word) between the sponsor and the rest of the unit-holders.  

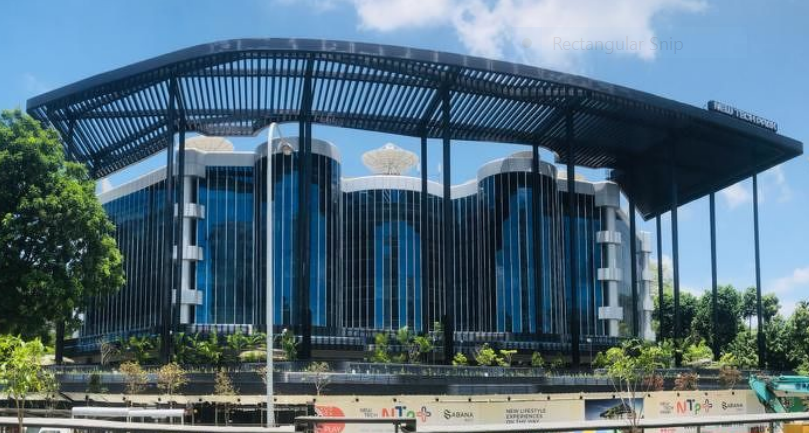
New Tech Park before the Asset Enhancement Exercise by Sabana REIT

1."Refresh Strategy" under new CEO is actually working well
Donald Han joined Sabana REIT as the new CEO in January 2018. He is a real estate veteran with over 30 years of experiences including working as the Managing Director Asia Pacific of Cushman & Wakefield and also the Managing Director of Chesterton Singapore. Donald had introduced and also implemented the "Refresh Strategy" which involves (i) disposing underperforming assets and matured assets, (ii) undertaking asset enhancement initiatives and (iii) acquisition of yield accretive assets locally or overseas. He is thus instrumental to the New Tech Park revamp- please see point 2 below. 

2. New Tech Park under "Refresh Strategy" beautifully executed as alluded to pt 1 now has a new retail F&B podium and also foodcourt at level 2 to be operationally ready by Q2 of 2021.
New Tech Park has already secured many new tenants for its retail F&B podium as well as got an operator for its 2nd level foodcourt. Good quality tenants include Collins, Wine Connection, Dutch Colony Coffee and Signature (a full range supermarket specializing in international produce).


I did a rough projection of the expect upsides to Sabana REIT unit holders for post execution of New Tech Park. This is going to increase the distribution per unit by 16.7% for FY2021 and 22.0% for FY2022 relative to FY2020 (reason being FY2021 only has around 8mths positive impact from opening of the new retail mall and foodcourt). If the market price is at S$0.40 per unit, the distribution yield is expected to be 7.17%. for FY2021 and expected to go up to 7.51% for FY2022.

Projected distribution yield after AEI at New Tech Park

Extracted from Commercial Guru for benchmarking

I estimated the rental per shop is at S$15,840 using a listing for New Tech Park new retail shop at Commercial Guru (S$19,800 per mth) and then applying a discount of 20% on S$19,800 per mth to be conservative in the projection. 25 retail units available per the news articles will thus mean S$396K additional contribution per month and S$3.168Mil for remaining 8 mths in FY2021.

Another point to note is that I have seen some people projected the yield to be up to 8%. This is not true. For FY2020 2nd half distribution, there are excess distributions due to previously withheld dividends from the 1st half as well as additional distributions in respect of prior years. Hence once you normalise the numbers, it should be only 6.15% for FY2021 at S$0.40 per unit market price. But if you included in the AEI done, this will go up to 7.05% in FY2021 and 7.51% in FY2022.

3. Potential acquisition of Sabana REIT by ESR REIT and possible 20% capital appreciation
Based on the full year results of 31 Dec 2020 released, the net asset value is worth S$0.57 per unit. This seems to be a vast improvement from the S$0.51 per unit as at 30 June 2020. Since Sabana REIT is adopting fair valuation of its investment properties, the net asset value will approximate the fair value. I reckon that there is a 20% to 40% upside if ESR REIT make a higher bid for Sabana REIT based on my entry price of S$0.39 per unit to S$0.40 per unit. 

4. Key risks holding on to Sabana REIT - The not so good parts
There are a few unstable risk factors underlying Sabana REIT despite the potential returns from distributions and capital appreciation. 

(i) Too few properties and small size 
The main key risk of holding on to Sabana REIT is that its portfolio only has 18 properties worth around S$1 billion. Any asset enhancement initiatives which needs to shut down any 1 property for such enhancement will mean down time which translates into loss of rental income generation for 1-2 years. This can be substantial in terms of the temporary losses in distribution of a single property relative to bigger REITS such as ESR with a bigger portfolio and many properties.

(ii) Sponsor ESR REIT not as prominent as some of the local REITs 
Another risk is that the sponsor is not as strong as Mapletree or Capitaland which are backed by the Singapore government. Weak sponsors will not be able to have the financial muscles to rescue them during times of financial crisis. Look at what had happened to Eagle Hospitality Trust and First REIT.  

(iii) Current minority unit-holders lead by Quartz Capital and Black Crane are very aggressive towards management of Sabana REIT.
Although I salute the efforts and leadership of the 2 fund managers in preventing low ball offers by the sponsor ESR to buyover Sabana REIT, I find their aggressive stance very troubling. Recently, they have been calling for the REIT manager to bear the cost of the failed EGM as well as asking independent directors that they do not like to resign. This constant infighting and stirring up of negative feelings of other retail unit-holders internally means management is spending more time fighting off its own unit-holders than concentrating fully to run the business. I do hope both fund managers can soften their aggressive stance and adopt a more diplomatic engagement approach to resolve the current impasse. 

(iv) REIT Manager- I think need to perform better and with more independence
My own view on this is simple. The claim that if ESR is not appointing any directors to the REIT manager means that the REIT manager is independent is nonsense to me. This is just playing with words. If you are getting your remuneration from the sponsor as a director of the REIT manager, then obviously there will be conflict of interest. The REIT manager needs to wake up and be more pro-active to doing the best for Sabana REIT. For example, during the last offer by ESR REIT, the offer values Sabana REIT at only S$0.362 per unit. This is almost a 30% discount off the 30 June 2020 Net Asset Value.

The REIT manager should have just rejected the deal or call in other bidders. I found their argument that any offer needs to be determined by unit-holders in an EGM illogical. For example, if a crazy bidder puts in a lowly bid of S$0.10 per unit pricing, does the REIT Manager still went on to call for an EGM for unit-holders to consider the low ball bid?
 
(v) Risk of ESR not offering acquisition anymore or fund managers selling off stakes leaving retail investors in a lurch
Sabana REIT as a standalone does not have much economies of scale which is a trend these days to enjoy a distinct competitive edge. At such high risk premiums due to so many unstable underlying factors as mentioned above, it will be hard for Sabana REIT to find yield accretive good properties. For many years, Sabana REIT has been languishing. The usual virtuous cycle of asset injection of yield accretive properties and then good capital appreciation of unit price which will lower its current yield for more future acquisition breaks down when we are talking about Sabana REIT. There is no better illustration than referring to its IPO price relative to current market price.

Summary
I do hope that the boxing matches between the sponsor ESR and the minority unitholders of Sabana REIT blow over soon. Both should actually give and take to resolve the current impasse which is a hindrance to the future growth of Sabana REIT.