Monday, 15 August 2022

Dasin Retail Trust And Investors In Trouble- Loss of S$56.4 Mil for 1st Half of 2022 And No Distribution Being Paid Out Red Flag.

Dasin Retail Trust ("DRT") just released a shocking set of 1H 2022 results whereby its investment properties valuation went down another <S$64Mil> for the 6mths period ending 30 June 2022. This is not including the <S$62.8Mil> written down taken for the previous financial year ending 31 Dec 2021. The total of <S$126.8Mil> of fair valuation being written down within a year makes one wonder about the real valuation of their balance sheet items. DRT also took a <S$11.4Mil> allowance hit for the 1H 2022 due to impairment of trade receivables from tenants. Notwithstanding the aforesaid mentioned, the worst news was that the management of DRT decided not to pay out a single cent of earnings in distribution for its 1st half using the pretext of prudent working capital management in the face of potential worsening of COVID outbreak in China.
Worsening financial health and unable to get back long outstanding debts owed by tenants.
For me, the danger signs of DRT in either bankruptcy or forced liquidation has been increasing and the last straw is the lack of a single cent of distribution for 1H 2022. I will be bailing out of DRT and withdrawing the bulk of my funds-leaving only S$500 to S$600 in capital (in the event that DRT survived the imminent business crisis). S$751Mil of loans remain due by 31 December 2022 even after so many rounds of loan extension by the bankers. Outstanding debts allowances has also ballooned to <S$11.4Mil>.
Sales of investment properties to raise cash to partially repay bank loan demanded by bankers
The management of DRT has been unable to conclude the sales of some of their shopping malls to raise cash despite only about 3 more months left in the loan extension. Extremely slow execution means that the potential buyer is also having doubts with regard to the quality of the assets being put up for sales. DRT could be on its way to a rights issue or forced liquidation of assets at firesales price if the bankers decided to take action to mitigate their risk exposure.

Parting thoughts
From the perspective of minimizing risk of total losses of capital, I have drastically reduced my stake in DRT by selling off 21,000 units immediately. Personally, I think that DRT management has neither been very transparent in the handling of its syndicated loan re-financing exercise nor timely in its routine operational updates. I also have serious reservation on the declared Net Asset Value of S$1.25 per unit asserted by the management. S$1.25 per unit may seemed like a lot of buffer and room for any black swan event or financial fraud. However, from the collapse of Eagle Hospitality Trust we can draw some parallel of what else may happen. The subsequent long drawn restructuring process ended up in the Trust becoming beyond saving. DRT may well be worthless if either the restructuring process drags on or the realised valuation of the investment properties is only at 50% of its current value posted on its statement of financial position- there is now a distinct high probability based on the recent turn of event. All the very best to other contrarian retail investors still holding on to DRT.  

Tuesday, 9 August 2022

Lendlease REIT Excellent Performance Post JEM Acquisition- High Distribution Forward Yield of 6.4%.

Lendlease REIT ("LREIT") announced a beautiful set of 2nd Half 2022 results post acquisition of Jurong East Mall ("JEM"). Its net property income for the same period was S$45.9Mil (increase of +S$19.4Mil or +73%) driven by the additional contributions from JEM as well as post COVID recovery of tenant sales in both 313@Somerset and also JEM itself. The tenant sales actually surpasses the pre-covid level. Distribution yield post JEM acquisition declared is S$0.01312 per unit for 31 March 2022 to 30 June 2022. Annualized yield would thus be S$ 0.05251 per unit which means a 6.4% distribution yield at the last trade price of S$0.82 per unit as at 8 August 2022. This is one of the highest distribution yield among other office and retail REITs on SGX. I also foresee further upside coming from LREIT in the next quarter announcement. A few quick highlights on LREIT:

1. Increasing DPU since listing on SGX

The above depicts the strong financial performance delivered by the management of LREIT for 2H FY2022 as well as for the entire FY2022. Note that its DPU has also been increasing since IPO. Not an easy task given the impact on COVID for the past 2 years. 

2.  25.8% of LREIT is occupied by financially stable tenants- Singapore Government and Sky
The offices portfolio of LREIT in Singapore and Italy are full leased to the Ministry of National Development ("MND") till 2044 and Sky Italia till 2032 respectively.  The MND office at JEM is subject to rental review every 5 years while Sky Complex is subject to annual rental review based on 75% of The Italian National Institute of Statistics consumer price index variation. 
From the diversified tenant base, we can see that the Singapore Government (MNC) and Broadcasting (Sky Italia) tenants made up 25.8% of the total tenants. LREIT thus continues to enjoy strong and stable cashflow from these 2 particular tenants for a long term as alluded to the above.  

3. Future upsides from upcoming Grange Road Carpark redevelopment into event space and potential acquisition of Paya Lebar Quarter Mall 
An independent cinema, hawker stalls and multiple event spaces are set to take over the 48,200 sq ft open-air carpark in Grange Road as part of major efforts to rejuvenate the Orchard Road area spearheaded by LREIT. This will be connected to the existing discovery walk linking up 313@Somerset and bring about increased in footfall and other synergies. 

Another major M&A in the form of Paya Lebar Quarter Mall is also in the future pipeline along with other Singapore properties held by its sponsor, the Lendlease Group.

Parting thoughts
Based on the current pricing of S$0.82 per unit, personally, I think it is very much undervalued by the market given the various upsides as discussed above. It is also giving out a forward distribution yield of 6.4%.

Wednesday, 3 August 2022

DigiCore REIT One Of Best Performing REITS- Price Recovery of 16% Within 1 Month But Uncertainties Still Lie Ahead.

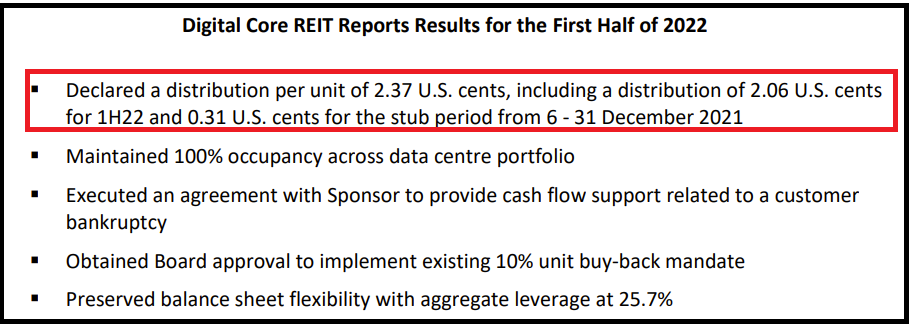
There are good news and bad news coming out of DigiCore REIT ("DC REIT"). Good news is that DC REIT has rebounded from its low of US$0.710 per unit in the July'22 bloodbath. Taking into account the recent price recovery of DC REIT to US$0.87 per unit as at 31 August 2022, this represented a +22.5% rally in market pricing which is an excellent news for all investors of DC REIT. The major bad news is that the 1st half distribution is only US$0.0206 per unit which means an annualised distribution of US$0.0412 per unit. At the price of US$0.87, this gives a distribution yield of a mere 4.74% per annum. Personally, I thought that with such a low yield at current market price, taking up business risks such as the bankruptcy of one of its major tenant is too much notwithstanding its Sponsor, Digital Realty, coming out to "guarantee" its cashflow.  
Dividend of 2.06 cents for 6mths of 1H22.
Sponsor to guarantee cashflow shortfall from future potential default by major tenant's bankruptcy
Initially, I was very excited and happy that the sponsor will make good on any loss of cashflow from the major tenant in bankruptcy. However, substance over form, this turns out to be in the form of a loan which need to be repaid eventually. DC REIT's own term for this loan is nicely crafted as a "cash flow support of shortfall". 

I have a hard time understanding the above arrangement as what is the use of having extra cash upfront but that one still need to return it to the Sponsor by 31 December 2028? Personally to me, this is just a clever financial engineering move to produce a seemingly stable stream of income for distribution at DC REIT level. It does not change the fact that DC REIT which just IPO has a potential default of rental by major tenant coming up. Money borrowed upfront from Sponsor ultimately still needs to be returned. The only consolation here is that the  "cashflow support" given is interest free. 
Extract of Cash Flow Support Agreement from the recent press release
Summary
During early July'22, when DC REIT's market price clashed due to the havoc caused by Chanos shorting data centres, I have accumulated 20,000 units of DC REIT at various batches averaging US$0.743 per unit (I have planned to acquire more units should it plunged below US$0.70 but this did not materialize). In view of the sudden August 2022 surge in DC REIT market prices which resulted in the extremely low distribution yield of less than 5% for DC REIT as well as the issue of major tenant facing bankruptcy, I have exited all my positions in DC REIT at US$0.865 per unit and took an immediate profit of US$2,440 (S$3,318). 16% realized return within a month is equivalent to waiting on capital deployed for 3 years to get the equivalent income distributions. I will be looking to re-deploy this S$20K plus in capital over the next few weeks.  


(Note: Since I am being heckled as well as being trolled online these days whenever my past few posting relating to REITs is put up on a Facebook group, I need to state here that having a liberal mind on discussion of 2 sides of a coin should never be perceived to be "filmsy" or "airy". It is also perfectly ok to disagree with my views but one should not be overly confrontational, in particularly, through harassing or trying to disconcert others with challenges or gibes.)

Wednesday, 27 July 2022

AMO Residence Over 98% Sold In A Day- Singapore Property Market Shining Bright In spite of Economic Downturn. Will You Pay S$6K To Service Your Mortgage in Outside Central Region?

AMO Residence located off Ang Mo Kio Avenue 1 ended the weekend of 23 July 2022 with 98.1% of its 372 units all sold out. The average price of units sold is at incredulous S$2,100psf. What a crazy price for Ang Mo Kio. UOL Group and its partners are now laughing all the way to the bank. I can still remember back in 2010 when Centro Residences debuted at Ang Mo Kio Centre- it was going for  an eye popping S$1,200 psf by Far East Organization during launch and many people were saying that is so exorbitant and a record price of over the psychological  barrier of up to S$1,000 psf for sub-urban area. Well, 12 years later, prices for new launch condo at Ang Mo Kio now apparently hit S$2,100 psf. This is paying close to S$2Mil for a compact 958 sqft 3 bedder unit.
Using a loan of S$1.5Mil spread over 30 years for a young couple along and assuming a 2.5% interest rate, this will mean a monthly payment of S$5.9K which means each husband and wife need to cough up around S$3K individually each month to service their mortgage. Total interest paid over 30 years will add up to S$634K.
2.5% borrowing rate simulation

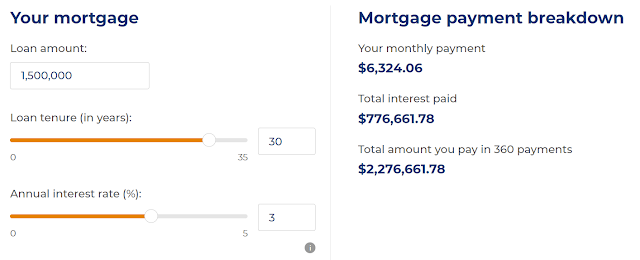
If interest rate continues to increase to say 3.0%, it will mean a monthly servicing of S$6.3K per month. Total interest rate paid over 30 years will be S$777K- I think it is time to buy more shares of DBS, UOB and OCBC listed on SGX which seems to be a better investment. 
3.0% borrowing rate simulation

Well, such pricing is not for the faint hearted folks. Down payment and stamp duties will mean half a million upfront in cash and CPF and not to mention in the current climate of rising bank borrowing rates, it certainly takes great courage to sign the option to purchase. According to property agents, the success of AMO Residence shows that "the market is hungry for attractively priced homes in good locations". Property prices is still a good hedge against inflation according to many people. I am not sure on that. However, I do hope that job losses are kept to a minimum in the upcoming economic downturn and everyone gets to keep their bread and butter. Else it will be extremely painful to support a S$6K per month mortgage. 

Tuesday, 19 July 2022

Mapletree Commercial Trust Tragic Preferential Offering Still Higher Than Market Price.

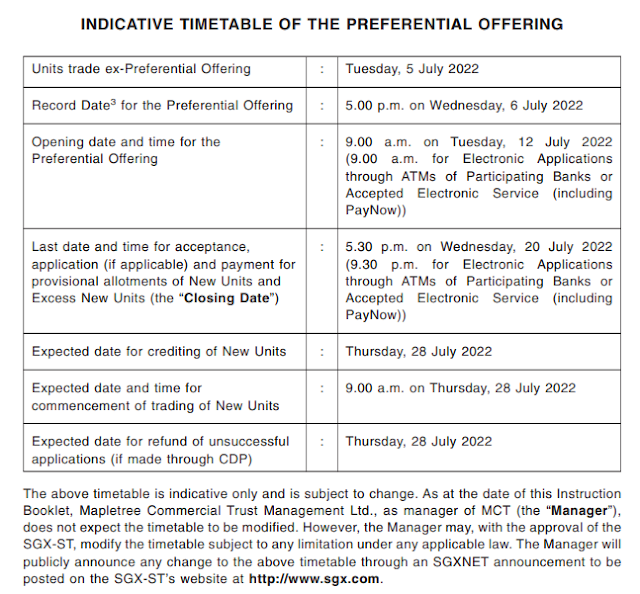
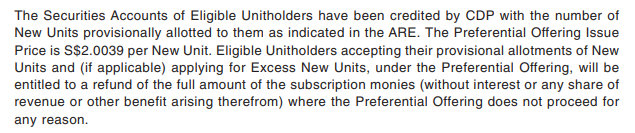
The tragic Preferential Offering exercise for Mapletree Commercial Trust ("MCT") has commenced on 12 July 2022 and will close at 5.30pm on Wednesday, 20 July 2022. The offer basis will be 306 Preferential Offering Units for every 1,000 existing MCT Units held by eligible unit-holders at the issue price of S$2.0039 per unit. It is a tragedy as the current market traded price as at 18 July 2022 is S$ 1.790 per unit hence no one in the right frame of mind will be subscribing for this particular rights issue which is at a premium of +12% to the market traded price on SGX. Mapletree Investments Pte Ltd will be taking up all the unsubscribed rights and losing as much as S$200Mil immediately in unrealised losses.  

Time table for Preferential Offering

Offered price way higher than last market trading price

While I have previously sold off my entire Mapletree North Asia Commercial Trust ("MNACT"), I am still holding on to MCT and as a matter of fact, I have been adding more units into MCT with the recent dip in pricing. With the previous January sudden outbreak of Omicron variant of COVID in Hong Kong being brought under better control, much of the restrictions previously imposed has been relaxed and this bodes well for its key asset Festival Walk acquired from MNACT. The negative rental reversion for Festival Walk should turn-around eventually.

Last but not least, I am sure that the incumbent property manager will continue to maximise the potential of all the newly acquired assets given its good track record of growing its portfolio under the management of the Mapletree branding. In addition, Mapletree Investments Pte Ltd seems to be of the view that the newly merged entity is worth at least S$2.0039 per unit and willing to undertake all the rights issue at this exorbitant price. 


(Note: Since I am being heckled as well as being trolled online these days whenever my past few posting relating to REITs is put up on a Facebook group, I need to state here that having a liberal mind on discussion of 2 sides of a coin should never be perceived to be "filmsy" or "airy". It is also perfectly ok to disagree with my views but one should not be overly confrontational, in particularly, through harassing or trying to disconcert others with challenges or gibes.)

Monday, 11 July 2022

The TikTok Hack To Partially En-cash $100 NS55 Digital Credit Actually Works.

I was initially skeptical when I read online that a TikTok user has discovered a "hack" to partially encash the NS55 $100 credit using Sheng Siong's $TM cash dispenser machine. While going grocery shopping with my wife over the last weekend, I decided to give it a try while my wife was queuing for payment at the cashier. The $TM cash dispenser at Sheng Siong gave me a heart attack for a few seconds as after the credit has been deducted, no cash came out and I instantaneously regretted not spending the money at F&B outlets directly. But to my surprise, cash was indeed eventually dispensed out of the machine after the lead time for processing and validation. So how does this work?  

Quick Background
Our Singapore government has decided to give S$100 to every current and ex-national servicemen S$100 credit to commemorate the 55th year of National Service and to recognize the contributions made by Singaporeans and permanent residents who had served the country. From July 2022 onwards, all eligible national servicemen will receive S$100 worth of NS55 credits which can be used at various merchants outlets in Singapore. 

1. First download the LifeSG App onto your mobile phone
After downloading, log in using your SingPass. Scroll down to "Benefits and support" section which is also where you can check your credit balances for SkillsFuture Credit. Go to NS55 credits (SAF) and click on "view details". There you will find the "Scan QR code to pay" button at the bottom of the screen for use later on the Sheng Siong's $TM.

2. Go to your nearest Sheng Siong outlet and locate their $ATM machine
Once you are at the machine, point towards the "PayNow" option for cash withdrawal. According to TikTok, you should only key in $90 (I am not sure whether it can go up higher but I think it is possible as long as you reserve a convenience fees of 20 cents which will be charged by Sheng Siong) The QR code will pop up. On your mobile phone LifeSG app as aforesaid mentioned in Point 1 above, tap on the "Scan QR code to pay". Then wait for the machine to dispense the cash after that. 

Parting thoughts
I thought it is rather interesting that we can en-cash the credit instead of having to spend it at retail or F&B outlets. Cash is the most practical as you choose to save it or spend it at non-participating merchants. Channel NewsAsia also reported that MINDEF has commented that "servicemen (NSmen) are free to decide how they want to use their S$100 of NS55 digital credits" and hence this approach seems legit. Let me know whether anyone of you are successful in drawing out the full $100 credit as the Tiktok video uses only S$90. :)   

Tuesday, 5 July 2022

Data Centre REITs Crashing Into The Abyss- Should You Continue Holding On To Them Or Dump Them? Is the Worst Over For Keppel DC REIT and Digital Core REIT?

My investments into Keppel DC REIT have been a horrendous experience thus far. I am currently looking at an unrealised loss of <12.79%> after the recent deep dive in market valuation. The other pure Data Centre REIT- Digital Core REIT ("DCREIT")- fares no better at its current poignant valuation of US$0.76 per unit as at 4 July 2022 and depending on your timing of purchase, one could be starring at as much as a whopping <36.7%> plunge in valuation if you have purchased it on 17 Jan 2022 at US$1.20 per unit. If you have subscribed for DCREIT during its maiden IPO and is successful in your allotment at US$0.88 per unit, then you will still be staring at a loss of <13.6%>. Given the terrible performance and worsening market sentiment, is it the time to throw in the towel and dispose of one's holdings rather than holding on to them? What exactly happen to have caused such a terrible crash in market prices for data centres?
Quick Recap
Since the beginning of Jan 2022, Keppel DC REIT has been plummeting non-stop from S$2.47 per unit to as low as S$1.90 per unit in 16th June 2022 which is a jaw dropping decline of <23%>. The main reason that everyone is aware of is the rising borrowing rates by the US Federal Reserve in its fight against inflation. However, during this same time frame, DCREIT remained in superman mode and performed a gravity defying stance that hovers above the US$1 mark per unit for the bulk of this period. There are actually another 2 developments that crop up recently which leads to the demystifying of the invincibility and relatively safe protection offered by data centre REITs. Suddenly, data centre REITs are no longer as safe as investors thought it to be. Let me further elaborate on the below:
1.  Bankruptcy of major tenant of DCREIT
Despite all the hoo-ha on the extremely long WALE of data centre REITs relative to other REIT sectors, the fact of the day is that fundamental and quality of one's tenant is of paramount importance. Even if the WALE is for 5-6 years, if any tenant goes bankrupt, the REIT will not get paid eventually. The shocking bankruptcy of DCREIT's 5th major tenant is a good example. Data Centre REITs are definitely not the same as government bonds as being asserted by some retail investors. 

2. Industry outlook for data centres severely affected recently by shock revelations of skeptics that "hyperscalers" (Google Cloud, Microsoft Azure and Amazon Web Services) are building up their own data centres to their own design rather than moving into existing ones.
Investment advisor and financier Jim Chanos has taken large short positions against data centres REITs and betting that the trio hyperscalers cloud providers (Google Cloud, Microsoft Azure and Amazon Web Services) will takeover their businesses. Ever since Jim's remarks on 29th June 2022, DCREIT price has crashed below US$0.80 per unit. Hence I think that many institutional and retail investors are now extremely worried about the future of their investments into data centre focused REITs and wondering whether the historical compressed yield of 4%-5% is viable in view of the risk profile changes in recent industrial development. 

Cloud computing is definitely growing but much of the value accruing is to the current 3 big boys of Alphabet, Microsoft and Amazon. Hence, the dynamic trio are actually not the data centre REITs biggest customers but more of their biggest competitors. The deep pocket of the trio make them  vicious rivals in the data centre business as they embark on aggressive building up of their own data centre infrastructure. The role of 3rd party data centres is more of to support the growth of the trio hyperscalers when they could not build fast enough and then turn to data centres firms to develop sites or to lease wholesale space. 

Chanos further argued that as the trio hyperscalers grow more powerful, the margins they offer will grow even lower. REITs thus suffered from technical obsolescence and will soon be in a period of declining revenue and growth. 
Parting thoughts
It seems that the domination of data centre REITs like Digital Realty, Equinix and Keppel DC REIT is coming to an end in the mid to long term. Who could have anticipated the possibility of such a development 2-3 years ago when data centres are all the rage then? Despite the significant decline in market pricing for DCREIT, I do not plan to acquire any units in DCREIT (unless it drops to below US$0.70 per unit for a 6% distribution yield to compensate for sufficient margin of safety) and will be keeping my investments in data centres to Keppel DC REIT, Ascendas REIT and Mapletree Industrial Trust backed by their well-heeled ultimate sponsor in Temasek Holdings.  

(Note: There is also a problem with some retail investors who are over-confident in their views that  one must always decide whether something is black or white/ Yes or No. The hard truth is that no one knows exactly when a spanner will be thrown into the works like the above latest development. Hence having a liberal mind on discussion of 2 sides of a coin should never be perceived to be "filmsy" or "airy". Neither should one be overly confrontational with aggressive "challenges" on others who writes about possibilities of different perspectives and things going either way.)