Saturday, 29 December 2018

Parc Botannia Review- The Condo Next To Jalan Kayu Food Heaven

Everyone in Singapore would have heard of the food heaven at Jalan Kayu which is home to the famous Thasevi roti prata. A branch of Blanco Prawn Noodle House is also located there and full of queuing customers. Have you guys heard of the famous Beach Road Prawn Noodle? Blanco and Beach Road Prawn Noodles are actually restaurants that are set up by the same Lee family (please read the history here by Dr Leslie Tay-Ï Eat I Shoot I Post"). The prawn noodle at Jalan Kayu is really superb and is a must try for all foodie! Ok, back to Parc Botannia review. The reason why I mentioned Jalan Kayu is that Parc Botannia is a stone's throw away from Jalan Kayu and one can feast on roti prata and prawn noodles daily if one choose to live in this lovely development.

(1) Location of Parc Botannia
Parc Botannia's address at Fernvale Road makes it a 10 mins brisk walk away to the Seletar Mall. This development is also just right next to Thanggam LRT station which is 1 LRT stop away from Seletar Mall and 4 LRT stops to Sengkang MRT station. There is also a plot of land designated for Park development by Npark just next to Parc Botannia (the new park sits between High Park Residences and Parc Botannia).

In addition, the Sengkang Riverside park is also near Parc Botannia or 1 LRT station away- Perfect for nature enthusiasts or folks who enjoy jogging. 

(2) More details about Parc Botannia
Tenure of Land: 99 years leasehold commencing Dec 28, 2016
Site Area: Approximately 185,095sqft
No of Units: 735 Units (spread over 4 blocks) and a childcare centre.
No of Parking Lots: 741 for residents and another 15 for childcare centre
TOP: Dec 30, 2021 (but expected TOP earlier in 2020 if construction progress is good).
Parc Botannia is being developed by joint venture partners, Sing Development and Wee Hur Development. The developers paid the winning bid of S$517.03 psf per plot ratio in September 2016 during the Singapore Government Land Sales.

(3) Internal Layout and Premium Units with Private Lift
This is one of the most efficient unit layout that I have seen despite the smaller size of the apartments relative to those launched in the area 7-8 years ago (H20 Residences, Rivertrees and Riverbank). 3 bedders are around 969 sqft but do not feel crampy as seen in the showflat. 
The high ceiling height of 2.9m certainly adds volume and exude class to the units. The developers are generous to have built in such high ceiling which is a sharp contrast to High Park Residences next door as well as many other condo ceiling heights of only 2.7m these days. 
The best units in this development are the 4 bedder Premium units as well as the 5 bedder Premium Units which comes with its own private lift. There are only a total of 3 stacks of such premium units. In addition, the premium units come with walk-in wardrobe in the master bedroom. The Master bathroom for the premium units also has 2 basins for "his" and "her" which are definitely very luxurious and posh.
Private Lift Lobby with Built in Shoe Racks/Storage
However, due to the high psf (please see "Pricing" below), getting a premium unit will set one back by an extra few hundred thousand dollars. In my opinion, getting the 958sqft 3 bedder or the 1,130sqft 4 bedder units are already value for money due to the efficient layout, high ceiling and premium fittings committed by the renowned developers, Sing Holdings and Wee Hur Holdings. 
3 Bedder Premium

4 Bedder-Typical

4 Bedder Premium with Private Lift

5 Bedder Premium with Private Lift

(4) Pricing of Parc Botannia
The average launch psf was 1,270psf. Since then, 75% of the 735 units have sold out as per the marketing agent. The remaining units are on the higher floor and may cost up to 1,350psf for high floor units. For a premium 1,249sqft unit, the price tag is thus approximately S$1.68 Mil before stamp duties.  

The strange thing about the pricing is that the developers seem to have priced the park facing units at a higher psf than the pool facing units. 

There is a current up to S$70k "Starbuy unit discount" on offer during this festive period for a limited time period. 

(5) Parting Thoughts
This is a well-conceived development by Sing Holdings and Wee Hur Holdings. There are many facilities on offer within Parc Botannia. The layout for units are very efficient and the finishing and fittings given are branded and classy. Being so close to Jalan Kayu and minutes walk away to Seletar Mall is very convenient for the residents of the development. One will certainly be enthralled when arriving home to one's personal sanctuary at Parc Botannia.

(P.S: Check out the official video here of Parc Botannia and the waterfall feature wall at the grand entrance).

Saturday, 22 December 2018

SPH REIT Still No Fate To Be Together With The Seletar Mall- But Suprised All With Australian Shopping Mall Acquisition

Many shareholders of SPH REIT have lamented over the lack of M&A for expansion. Ever since its maiden IPO, SPH REIT only had Paragon and The Clementi Mall in its portfolio. During the last AGM held on November 30, 2018, the question of why only a tiny strip of Mall, namely, The Rail Mall was acquired during the current financial year was raised. The answers given as per below screenshot on the usual rhetoric response that the asset acquired must be good quality, well located with a minimum 6% yield similar to the existing 2 malls. You can imagine the disappointment of all shareholders (including myself) that SPH REIT still has no fate to be together with The Seletar Mall that SPH is still keeping in its stable ever since its official opening in November 28, 2014. 

Why is everyone so looking forward to The Seletar Mall joining SPH REIT?
As a suburban mall located in the heart of Sengkang West, it is expected to enhance the REIT's resiliency in earnings even during an economic downturn. Currently, Paragon forms the main bulk of the earnings contribution. The Seletar Mall is expected to cost S$500Mil and will boost the earnings significantly from suburban shopping. NTUC Finest and Shaw Theatres are the current major anchor tenants. The hotpot chain Hai Di Lao also has a new branch opened in 2018 there that sees super long queues during lunch and dinner time during the weekend. 

Other retail chains such as Uniqlo and BHG are also tenants that have been there for many years since its official opening in November 2014. Other F&B tenants include Mc Donald, Starbucks, Burger King, Song Fa Ba Kut Teh. There are also many education centres such as the Learning Lab located at The Seletar Mall. 
Picture of The Seletar Mall at Sengkang West

The interior layout which is unique and have natural lightings from the roof pouring into the Mall.
Many analysts have been saying that The Seletar Mall will be up for sales to SPH REIT since 2016 but it has not materialized.

A surprised announcement of another acquisition- purchase of freehold Australian Mall
The big surprise came on Dec 18, 2018, just 2 weeks after SPH REIT mentioned that they are mulling over acquisitions which have been tough to fulfill based on their stringent checklist. SPH REIT announced that they have signed an agreement to acquire Figtree Grove Shopping Centre from Swordfish Australian Mid TC Pty Ltd for approximately A$210 Mil. 

Figtree Grove Shopping Centre is located about 3.7 km southwest of the Wollongong and 71 km southwest of Sydney. It occupies a total gross lettable area of 21,984 sqm, including facilities like a 24-hour Kmart, supermarkets, retailers and dining options. It sits on a freehold land area of 50,900 sqm. 

The proposed acquisition will be made through Figtree Holding Trust, a wholly owned sub-trust of a joint venture between SPH Reit and entities managed by Moelis Australia, an ASX-listed financial services group. SPH REIT and Moelis Australia Asset Management will pay A$175.1Mil and A$30.9 Mil for a stake of 85% and 15% respectively.


This bodes well for SPH REIT through working on a partnership with Moelis which is brokering the deal with the giant private equity fund Blackstone and providing local networking support. It also allows SPH REIT management team to get invaluable management exposure of shopping mall in Australia and pave the way for more Australian acquisitions in future pipelines. It also diversifies the geographical risk of portfolios based only in Singapore. 

Current SPH REIT valuation using Dividend Discounted Model
The Dividend Discount Model ("DDM" is a method of valuing a company's stock price based on the theory that its stock is worth the sum of all of its future dividend payments, discounted back to their present value. Since REITS payout more than 90% of its earnings as dividends, DDM will be a useful tool for us to do some mathematical valuation to see the fair value per unit expected.
P = D1 / (r -g)
P= Current Price based on summation of the infinite series;
D1= Dividend Payment per unit (S$0.055) for 1 year;
r= Cost of Equity (assume 5.5% based on 21st Dec 2018 closing price);
g= Dividend Growth Rate-Assume zero to be conservative.

From the above assumption, the valuation of SPH REIT is at S$1.00 per unit. The current price as at December 21, 2018 thus does not seem to have fully priced in the upcoming Australian acquisition and also the potential future acquisition of Seletar Mall. Further long term price catalyst includes the new Woodleigh shopping mall that SPH is developing with Kajima at Bidadari. 

Sunday, 9 December 2018

Jui Residences Review- Inspired by Heritage, Designed for Quality Living


Jui Residences is a freehold development that sits on the former National Aerated Water Company site. I used to study in a school at Geylang Bahru and as I walked to the bus stop home along Serangoon Road, it became a daily ritual to always do a stopover at National Aerated Plant and buy Kickapoo from a vending machine near its main gate. It dispensed Kickapoo cheaply at a mere 10 cents per cup and was very popular with a lot of school kids then. As a result, this development held very fond memories for me.  

Strangely, the show flat of Jui Residences is right next to Woodleigh Residences. I had applied for annual leave to visit Woodleigh Residences as I was rather fascinated by staying in an apartment that is right above a shopping mall just like Punggol Watertown Residences and Sengkang Compass Heights. I harbored hope that maybe there will be special star buys around in Woodleigh Residences given the current feeble state of our global economy. When my property agent who was showing me around told me that prices are around S$2,000++ psf,  I nearly fainted as I gasp for breath. Then the agent whispered into my ear: "Yes, I also think the prices here are crazy.....why don't I recommend you a freehold development near the area that is way cheaper than this?" So, my agent then brought me next door to the Jui Residences show flat.   

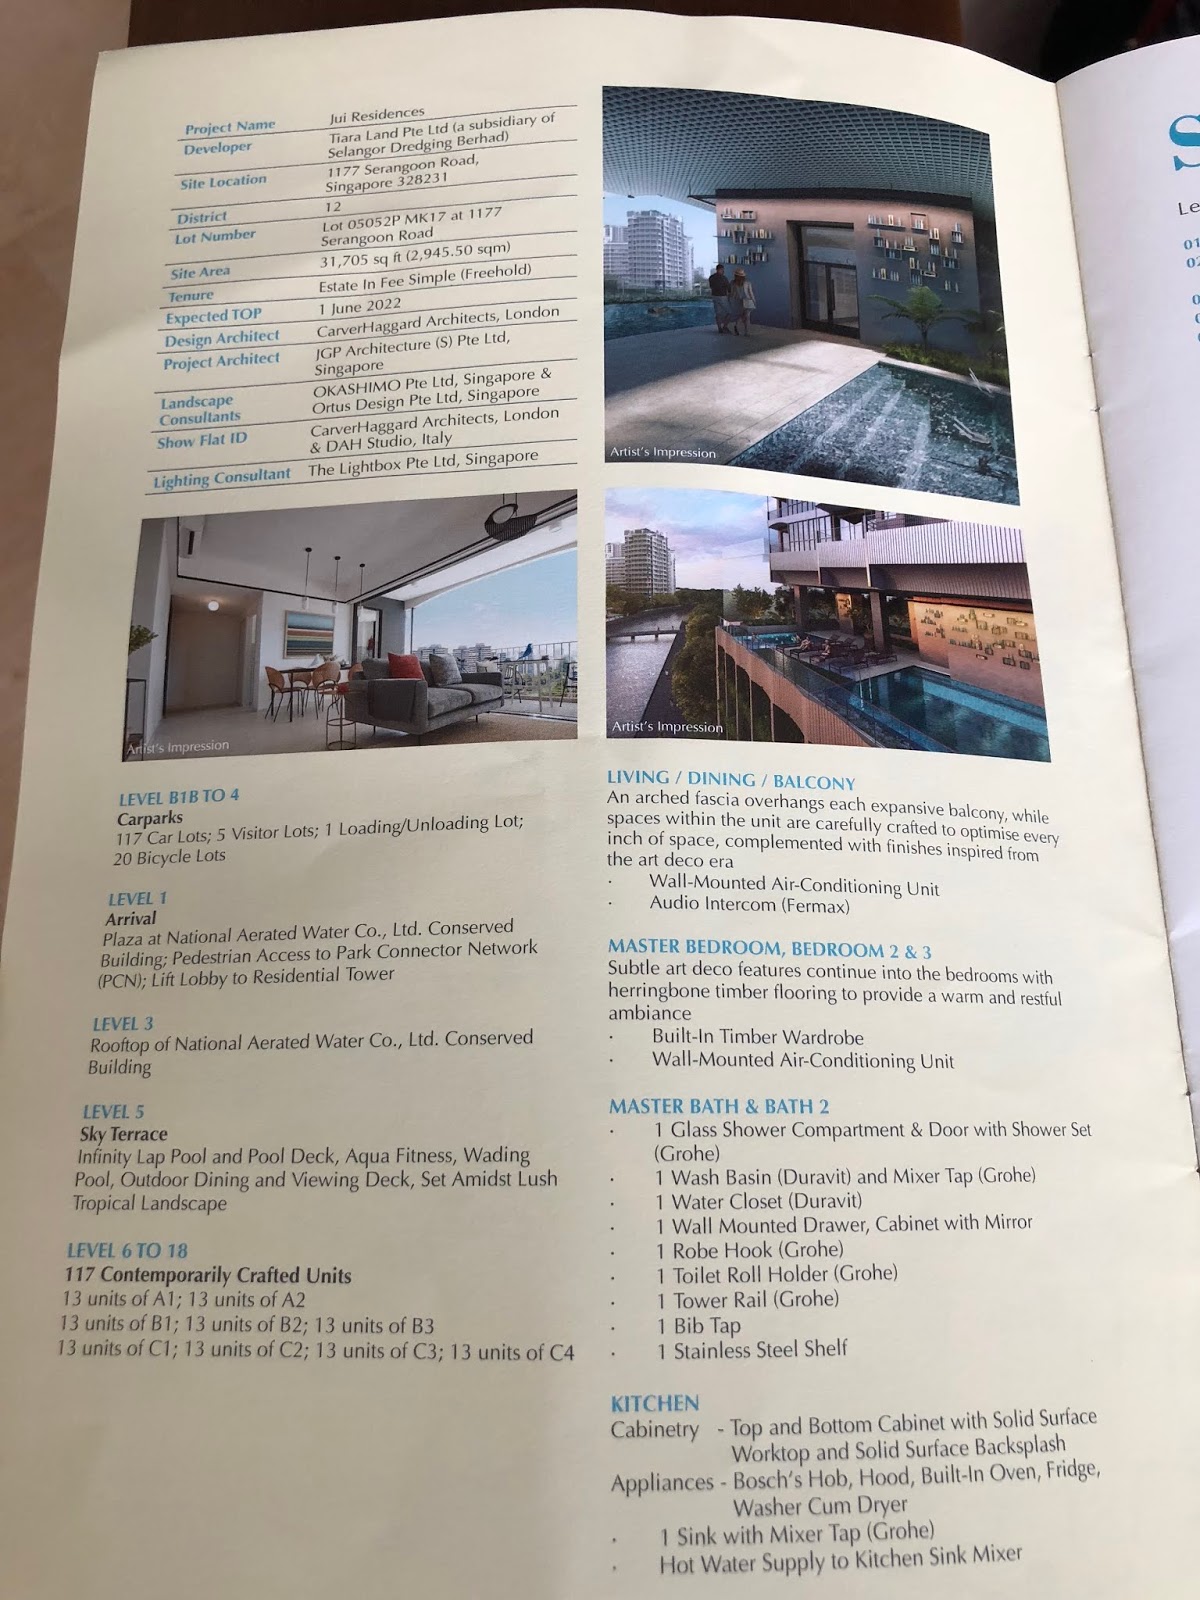
In December 2016, National Aerated Water Company sold the freehold industrial site for S$47Mil to Selangor Dredging Berhad ("SDB"). SDB paid an additional S$22.66Mil to the local authorities for intensification of usage to a residential site. The total land cost thus translates to an acquisition cost of S$785psf per plot ratio for the land area of 31,705sqft with permissible built up of 88,775sqft of gross floor area based on plot ratio of 2.8. Also, the National Aerated Water building will be partially conserved as stipulated by Urban Redevelopment Authority and integrated into the new development and kept fenceless along Serangoon Road and the river.

Location:
This is a city fringe located freehold property. Coupled with it being just next to Kallang River, residents gets to enjoy river view. Not many properties can boast being near to reservoir or waterbody and I considered it an unique gem that is away from the hustle and bustle of City life. Coming back home to this development thus allows one to enter into a mini resort ambience and at the same time enjoy the convenient location.  
Good size Infinity Lap Pool albeit small landsize.


Amenities and Facilities
There will be 117 units for one tower in this development. Carpark lot is 1 for 1 as well as an additional 5 parking lots for visitors. There will be adequate parking space from B1 to level 4 multistorey carpark. There will not be big fights over parking relative to other developments which has cut down to less than 1 for 1 ratio.

The infinity pool is the main highlight for this development. It looks very impressive and is decent sized considering the small landsize.

However, I was quite disappointed that there was no gymnasium at all. This is good in the sense that this will reduce the yearly maintenance cost. In addition, the developer will link up Jui Residences to the Kallang Park Connector hence probably they make do away with the need for treadmills since residents can just go jogging along the track. 


Units and Finishing
Overall, the layout of the apartments here is quite small. The master bedroom based on my standard are tiny. This seems to be the trending these days. If one wants to buy a 3 bedder unit, please avoid type C1, C2 and C3 which have long entrances that wasted the use of space efficiently. The best will be type C4 as illustrated in the picture above which represented the best 3 bedder layout. Type C4 is also the biggest unit in the entire development.

I do have a serious problem with the finishing given, that is, the tiles for the kitchen wall and bathrooms which I find too "Retro" and does not exude a modern contemporary feel. This maybe due to the integration with the conservation of the older industrial facade for National Aerated Water Company. But one can always choose to change the finishing during the renovation to fit one's desired theme. Rather, it is the location that cannot be altered at will.

Pricing
Pricing is around S$1,700psf and there is still some discount available from the developer. This is a freehold status development. For home buyers who wanted more value for money and do not mind buying 2nd handed projects, one can look for other older developments located closer to Boon Keng MRT direction and also Potong Pasir direction. 

Parting Thoughts
The "Jui" in the name of this project actually means "Water". This is a good city fringe located property that is beside the beautiful Kallang River. The integration with a part of Singapore history that is being earmarked for conservation further enhances the uniqueness of this freehold development.

Saturday, 17 November 2018

Asian Pay TV Trust Meltdown- Is It A Good Buy At Current Price And Is It A Good Business?

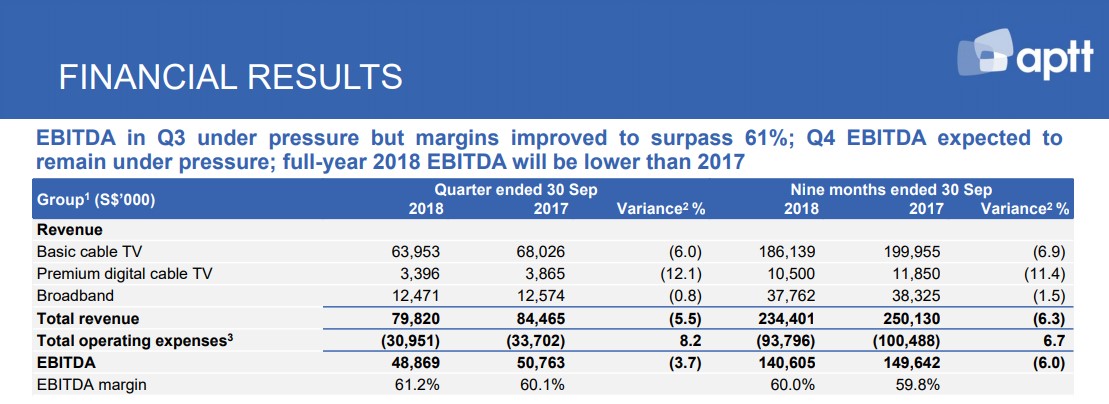
Asian Pay TV Trust (APTT) unit price plummeted this week upon the announcement by their management team that they will be cutting dividends by 80%. This was a rude shock to many of their investors who were anticipating the dividend to be cut by half only. As a result, the unit price had a meltdown and dropped to S$0.15 during an all-time low on 14 November 2018 from the previous day closing price of S$0.315. Obviously, a lot of dividend yield-seeking investors are cursing and swearing at APTT. I also know of a case of an investor who bought 100,000 shares of APTT at around $0.47 a few months back and in total held over 300,000 shares of APTT. This represented a loss of at least S$100K in the capital value of the stocks on hand due to higher acquisition price over the prior years.

Why Do Some Investors Use Net Asset Per Unit To State That APTT Is Undervalued hence keep buying non-stop?
I would also like to add on that using purely Net Asset per unit to value APTT is not a good yardstick which some investors had relied on. This is because a huge chunk of the "asset" is tied up with an intangible asset in the form of a license to operate its business in Taiwan. The valuation of an intangible asset is fraught with lots of subjectivity depending on your beliefs. For my own sensitivity analysis, I would have impaired and discounted it severely based on the ever-weakening future cash flow generation from the entire business.

Is The Worst Over For APTT?
The million dollar question that everyone keeps asking now is whether the worst is over. Most importantly, is it a good time to buy undervalued units for APTT and also whether it is still a good business to invest in?
First and foremost, my personal view is that APTT has been massively oversold. There are no significant changes in the current business environment. The results show 9mths ended 30 September 2018 revenue declining by <6.3%> and EBITDA decreasing by <6%> whereas unit prices had plunged by 50%.  I think that the fair value should be a lot higher. Also, the dividend payout after the cut is actually more sustainable. For those who dare goes in now will definitely have a higher probability of making profits. Generally, it is the entry price relative to the fair value of any type of business that determines whether the investment will turn out to be profitable.

Also, the extremely low price is actually making it an attractive offer for buy-out by existing shareholders such as Terry Gou (Hon Hai Group Chairman) or other big corporations. 

BUT personally, I need to point out that while the unit prices are currently undervalued, there are unstable elements that are shaking the fundamentals of APTT and one may not be able to sleep well at night holding on to this counter.

3 Reasons Why Low Risk Tolerance Investor Should Stay FAR Far Away From APTT:

(1) Intense Competition from Pirates and Mobile unlimited Data Plans from Taiwanese Telecoms.
Consumers today are buying lots of TV boxes with free pirated TV shows. OTT such as Netflix, Viu, Youtube Premium etc are rising in popularity. Pay TV services is a declining market. For fibre broadband, they are also facing intense competition from Taiwanese Telecom companies which are offering unlimited Data Plans on the mobile network for connection. While the services are not obsolete, the revenue APTT can generate will continue to decline gradually due to a change in consumer demand. 

(2) APTT Management Team is either exhibiting excessive optimism from previously announced results or they are unsure of their own business and industry outlook. 
I have previously pointed out in my other posts that the management keeps repeating that the ARPU decline is stabilizing. Apparently, their perception and definition of stabilization are very different from my own definition. Quarter by quarter it has been declining. I do not see anything stabilising about that aspect. 
Extract from previous QFY2018 Q2 Results Presentation
In addition, during the 2nd quarter announcement, the APTT management team mentioned that they believed the unit prices are undervalued and that they are contemplating a share-buy back. But for the recent 3rd quarter announcement, it turns out that they have cashflow issue to fund future CAPEX without incurring more debts. Hence why talk about share-buy back when they do not even have sufficient funds to maintain the previous dividends and future CAPEX? I personally find such presentation contradictory to the ground situation and have sold off all my APTT units immediately after my last post in September'18 and hence was lucky to have avoided the recent crash in the unit price.

I hope that the major institutional investors will demand for at least 1 new senior management personnel to join the current APTT management team. It is time to do a global search or look in Taiwan for someone who can effect change by bringing in new perspective to the current business. Look at Starhub Singapore, it has done well with a new CEO who has brilliantly executed a cost-cutting exercise and a joint venture for cybersecurity.

I hold a view that a solid management team is a core to sustaining and developing a business and to continue to make it relevant.

(3) Massive Debts and Rising Interest Rate Environment
S$1.4 billion debt is actually a high risk to APTT as alluded to Reason 1 above. The old perception by everybody that APTT is a defensive stock and has stable cashfllow is actually no longer valid due to the declining customer demand. Banks are known to be fair weather friends. Once the marco economic environment sours or there are further decline in operating results that lead to banker's re-assessment, there is no guarantee in the loan agreements that the bankers are obligated to continue extending the borrowings indefinitely. The billion dollar debt is not a small amount.

I am also not confident that APTT will be able to get a lower financing charge upon renewal in the face of a rising interest environment and also declining business albeit gradually, that leads to worsening risk profile. Again, I do not share the same excessive optimism of the management team of APTT. Leverage is always a double-edged sword that cuts both ways.

Parting Thoughts
The current price of S$0.167 per unit includes dividend declared. Stripped off the Q3 dividend of S$0.016 per unit and ex-dividend effect will be S$ 0.151 per unit. From the revised dividends projection of S$0.012 per unit for FY2019 and FY2020, the dividend yield thus becomes 7.95% which is fairly decent as historical excessive dividends payout will be re-deployed back into the business as CAPEX investment.

For more conservative and low-risk tolerance investors, it may be better to give APTT a miss in order to sleep better at night.  

Saturday, 10 November 2018

Singtel 1st Half 2018 Results Review And Interim Dividends Payout (6.8cents per share)

Singtel just announced its first-half results ended 30 September 2018. I actually think that it is a fairly good results being announced considering the intense competition faced by its overseas associate companies and Optus. Operating revenue surprisingly remained resilient and even grow 3% to S$8.4 billion. Margin eroded by over 21% (after normalisation from one-off gain from disposal of Netlink Trust in the previous year) mainly due to lower contributions from Airtel and Telkomsel as well as foreign currency translation losses from the effects of stronger Sing dollars against other currencies.

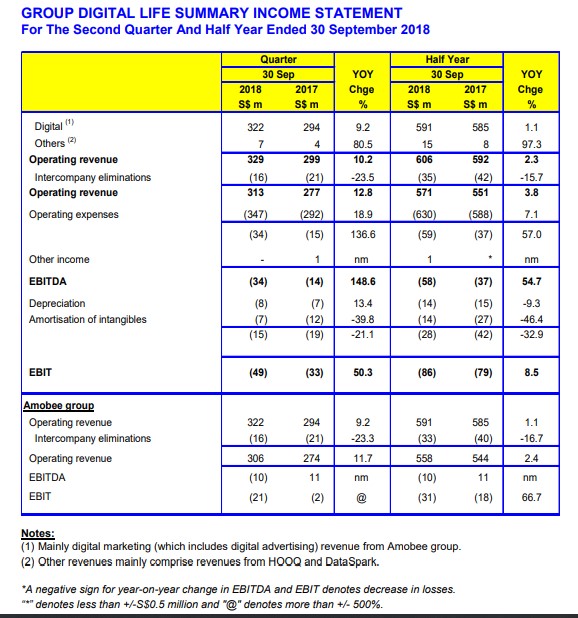
The only concern I have is that Singtel still has not stemmed the bleeding from Group Digital Life business. It continued with  a widening of losses of <S$84Mil> based on the first half results. While I understand the importance of investing in this business segment which management seems to believe that there are perceived synergy to exploit on the Group's service offerings, the results have been depressing for years. They just can't seem to breakeven despite growth in revenue.

I have previously disposed all my Singtel stocks at prices of S$3.78 level as I do not like the intense competition with TPG jumping into the Singapore market by year-end. With the sharp decline in the prices of Singtel and which I think have been oversold, I have been accumulating new Singtel shares at prices ranging from S$3.060 to S$3.180 recently. The current business model from telecom business is still relevant and Singtel has proven to be defensive in nature over these past few months with lesser trading volatility relative to other blue chips. 

An interim dividend of S$0.068 per share has been declared which represented a 2.19% yield based on the last traded price of S$3.10 per share and in line with expectation. Hence Singtel is still on track for its dividend guidance over the next 2 years of S$0.175 per share. This represents an annual yield of 5.65% which is fairly attractive while waiting for the share price to recover.  

Tuesday, 6 November 2018

Risk of Higher Interest Rates Effect On Stocks and Properties Amidst Trade War Between US And China

The stock market has been going on a see-saw ride for many months now. Just a few days ago, stock market worldwide rallied thinking that Trump will end the standoff in trade spat with China. But then on Monday, Asian markets tumbled immediately after White House economic advisor Larry Kudlow gave a clarification that the US is not likely to deal. 

In view of the great uncertainty over the resolution of the ongoing trade row, economic activities will continue to slow down albeit the full impact not being felt in Singapore yet. We remain in a perilous situation. The relentless increase in interest rates by the Federal Reserve certainly does not help the current economies.

On the stock market front, it is a fallacy to think that banks will definitely benefit from a higher interest rate and that it is a good time to buy into banking stocks. Banks may not benefit at all from interest rates rise if the volume of transactions goes down drastically, in particular in an economic recession climate. All economies and companies follow the rule of going through ups and downs. Banks such as DBS and OCBC cannot be delivering gravity-defying higher and higher record profits for every quarter.

On the Singapore property market front, an increase in interest rates in the face of ever-increasing property prices may eventually lead to a decline soon. This is because once cheap money is removed and new buyers take up more expensive property loans, they will have to fork out a lot more in terms of monthly repayment. The below illustrative (using the recent hottest property on the block-Woodleigh Residences) depicts the effects of the monthly housing loan repayment based on varying interest rates over 30 years for those who dare to venture into the private property market at this point in time.

The Hong Kong market has already been seeing signs of a housing downturn amidst the rising interest rates. Application for mortgage applications have dropped and increasing properties being let go at lower asking prices. A similar fate awaits the Singapore property market if things do not improve soon. 

For investors, this represents an extremely rare opportunity to get stocks and properties at a good deal. The moral of the story is to wait for economic events to unfurl. Recession or not, I have learned a good lesson from the 2008 global financial crisis, that is, do not go into the market immediately. Be patient and spread out available cash and accumulate assets gradually over the coming 6 mths instead of pumping all available resources into the market at this juncture as if there is no tomorrow for fear of missing the boat.

Saturday, 27 October 2018

Dead Cat Bounce and Bear Coming Out? Are We In A Recession Already?


Recent turmoil and bloodbath in the stock market are giving me a Deja Vu feel to the 2008 pre-global financial crisis. The stock market will recover with many analysts chanting just a normal correction. Then stock prices will pick up as if poised for a major rally but within a few days commence tapering off again. This dead cat bounce will happen a few times but the market never seems to be able to break out.

Our government also warned of the effects of the US-China trade war beginning to hit our economy over the next few months. 

Keeping my fingers crossed that there will be an improvement when Trump and Xi next meetup in November 2018 during the G20 Summit. Business and consumer sentiment are very fragile objects which can be shattered easily by any external economic bad news. It may go quickly south in the blink of an eye or even worse, the beginning of an economic meltdown. Probably best to keep additional liquidity on hand instead of a full deployment of all available cash into stocks at this juncture. 

Please feel free to share your thoughts and comments on the economic outlook. Thanks!